

Does the Veteran Affairs program have a minimum credit score for a VA loan?
One of the most persistent myths about VA loans is that the Department of Veterans Affairs requires a minimum credit score. This is false. The VA itself does not set a credit score minimum for the loans it guarantees. Instead, the VA empowers individual lenders to set their own credit requirements.
While most lenders typically look for a FICO score of 620 or higher, many specialize in working with veterans who have experienced financial hardship. (The data, information, or policy mentioned here may vary over time.) It's possible to find lenders willing to approve a VA loan with a score as low as 580 or even lower in some cases, especially if you have strong 'compensating factors'. (The data, information, or policy mentioned here may vary over time.)
Your credit score is simply one piece of a much larger puzzle. The VA loan program was designed to be flexible and forgiving, focusing on a veteran's overall financial picture rather than just a single number.
What is residual income and how does it help me qualify in Miami?
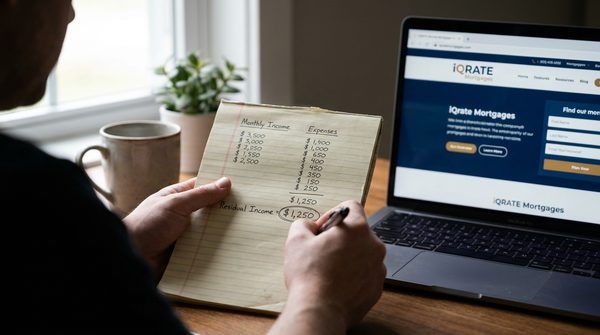
Residual income is the cornerstone of VA loan underwriting and the primary reason why veterans with higher debt can still get approved. It's the amount of net income left over each month after paying major expenses, including:
- The new mortgage payment (principal, interest, taxes, and insurance)
- State and federal income taxes
- Recurring debts (car loans, student loans, credit card payments)
- Child care expenses
This remaining cash is what you use for daily living expenses like food, gas, and utilities. The VA establishes a minimum residual income guideline based on your family size and location. (The data, information, or policy mentioned here may vary over time.) A lender in Miami, for example, will use a higher residual income threshold than a lender in a lower-cost rural area because the cost of living in South Florida is higher.
Example: A Miami Veteran
Let's say a veteran in Miami has a monthly income of $6,000 and a proposed housing and debt payment of $3,500. Their DTI is high at 58%. An automated system might deny them. However, their remaining residual income is $2,500. For their family size in their region, the VA guideline might only be $1,100. Because they exceed this threshold significantly, an underwriter can see they have more than enough cash flow to live comfortably and are a low default risk, making approval possible despite the high DTI.
How can compensating factors overcome a high debt-to-income ratio?
Compensating factors are positive elements in your financial profile that help an underwriter approve a loan that falls outside standard guidelines. They demonstrate your ability and willingness to repay the mortgage, even with a low credit score or high DTI. For veterans, these factors are particularly powerful.
Key compensating factors include:
- Significant Cash Reserves: Having several months' worth of mortgage payments saved in a verifiable account shows financial stability.
- Minimal Payment Shock: If your new proposed mortgage payment is only slightly higher (or even lower) than your current rent, it shows you are already accustomed to managing that housing expense.
- Excellent Recent Credit: A perfect payment history for the last 12-24 months can outweigh older credit problems.
- Long-Term Employment: A stable job in the same field demonstrates reliable and continuous income.
- Down Payment: While VA loans don't require a down payment, making one voluntarily (e.g., 5%) significantly strengthens your file.
What is a manual underwrite and when is it required for an Orlando loan?
A manual underwrite is exactly what it sounds like: a human underwriter personally reviews your entire loan file instead of relying on an Automated Underwriting System (AUS). An AUS is a computer algorithm that gives an initial 'approve/eligible' or 'refer' decision based on data points like credit score and DTI.
A 'refer' decision from the AUS often triggers a manual underwrite. This is common for veterans applying for a loan in Orlando who have:
- A credit score below the lender's typical threshold (e.g., under 620).
- A recent major credit event, such as a bankruptcy or foreclosure.
- A high DTI ratio that exceeds the standard 41% guideline. (The data, information, or policy mentioned here may vary over time.)
- Irregular income sources, such as self-employment or commission-based pay.
A manual underwrite is a huge advantage of the VA program. It allows an experienced professional to look at the 'why' behind the numbers. They can consider your letter of explanation, your strong residual income, and your compensating factors to make a common-sense lending decision that an algorithm cannot.
How long after bankruptcy can I apply for a VA loan?
Having a past bankruptcy does not permanently bar you from using your VA loan benefit. The VA has some of the most lenient waiting periods in the mortgage industry.
- Chapter 7 Bankruptcy: You can typically apply for a VA loan just two years after the discharge date of a Chapter 7 bankruptcy. This is significantly shorter than the four-year waiting period for a conventional loan.
- Chapter 13 Bankruptcy: The guidelines are even more favorable here. You may be eligible for a VA loan after making just 12 months of on-time payments to the bankruptcy trustee. You will also need permission from the court to take on new debt.
In both scenarios, the most critical factor is demonstrating that you have re-established good credit since the bankruptcy and have not taken on any new, unmanaged debt.
Will medical collections prevent me from getting VA loan approval?
Medical debt is treated differently than consumer debt in VA underwriting. The VA recognizes that medical issues are often unexpected and can lead to collections that don't accurately reflect a person's willingness to pay their obligations. For this reason, medical collection accounts are often disregarded during the loan approval process.
If your low credit score is primarily due to medical collections, an underwriter can often overlook them, especially during a manual review. This is a significant benefit for veterans, as it prevents unforeseen health challenges from becoming a barrier to homeownership.
What steps can I take to prepare my file for a lender?
Preparing your application thoughtfully can dramatically increase your chances of approval, especially with a complex financial history. Here are the essential steps:
- Obtain Your Certificate of Eligibility (COE): This document proves to the lender that you have the required military service to qualify for the VA loan benefit.
- Gather All Financial Documents: Collect your pay stubs, W-2s, tax returns for the last two years, and bank statements. Having everything ready speeds up the process.
- Write a Letter of Explanation (LOE): If you have derogatory credit items, draft a clear and concise letter explaining the circumstances that led to the issue and the steps you've taken to resolve them.
- Check Your Residual Income: Use a simple budget to calculate your residual income. Knowing this number helps you understand what you can comfortably afford.
- Partner with a VA Loan Specialist: Don't go to just any bank. Work with a mortgage broker or lender who has deep experience with VA loans, especially manual underwriting. They know the guidelines inside and out and can advocate on your behalf.
If you're a veteran in Florida who has been told 'no' before, don't give up on the dream of homeownership. Understanding the unique, flexible guidelines of VA loans is the first step. When you're ready to partner with a specialist who can navigate these rules for you, Apply now to find your path home.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
U.S. Department of Veterans Affairs - Home Loan Guaranty
Consumer Financial Protection Bureau - What is a debt-to-income ratio?









