

The Two-Year History Rule for Variable Nursing Income
For nurses in Texas, variable income from overtime, night differentials, and holiday pay often makes up a significant portion of their total earnings. However, when you apply for a mortgage, lenders don't automatically add this income to your base salary. To use this extra pay to qualify for a larger home loan in competitive markets like Houston or Dallas, you must demonstrate a consistent history of earning it. This is known as the two-year history rule.
Lenders need to be confident that your variable income is stable and likely to continue. A single month with high overtime isn't enough. They want to see a documented track record spanning the last 24 months. This history proves that your higher earnings are a regular part of your compensation, not a temporary fluke. Without this two-year history, most lenders will only consider your base hourly rate, which can dramatically reduce your borrowing power and limit your options for buying a home in desirable neighborhoods.
This rule applies to most types of variable pay, including:
- Overtime Pay: Hours worked beyond your standard shift.
- Shift Differentials: Extra pay for working less desirable shifts like nights, weekends, or holidays.
- Charge Nurse Pay: Additional compensation for taking on supervisory responsibilities during a shift.
- On-Call Pay: Compensation for being available to work on short notice.
Failing to provide clear documentation of this two-year history is one of the most common reasons nurses get pre-approved for a much lower amount than they expect. The responsibility is on you and your mortgage officer to build a strong case that your full income is reliable.
How Lenders Average Your Overtime and Differential Pay
Once you've established a two-year history, lenders don't just take your best month and use that figure. They calculate a conservative, predictable monthly average to use for your debt-to-income (DTI) ratio. The standard method is to average your variable earnings over the past 24 months.
However, there's a critical detail: lenders will use the lower of two calculations:
- The 24-month average from your last two years' W-2s and tax returns.
- The year-to-date (YTD) average based on your most recent pay stubs.
This 'lesser of' rule protects the lender from approving a loan based on an income that is currently declining. For example, if you worked significant overtime in 2022 and 2023 but have reduced your extra hours in 2024, the lender will use the lower YTD average from 2024 for qualification. Conversely, if your overtime has been increasing, they will still rely on the more conservative 24-month average.
Let's look at a realistic example for a nurse working at a major hospital in Fort Worth:
- 2022 W-2 Overtime Earnings: $22,000
- 2023 W-2 Overtime Earnings: $26,000
- Total 24-Month Overtime: $48,000
- 24-Month Average Monthly Overtime: $48,000 / 24 months = $2,000 per month
Now, let's look at her YTD earnings as of June 30th:
- YTD Overtime on Pay Stub: $15,000
- YTD Average Monthly Overtime: $15,000 / 6 months = $2,500 per month
In this scenario, the lender will use the more conservative $2,000 per month figure for her qualifying income. Even though her recent overtime is higher, they will stick to the longer-term average. This averaged amount is then added to her base monthly salary to determine her total qualifying income.
Securing a Detailed Verification of Employment (VOE)
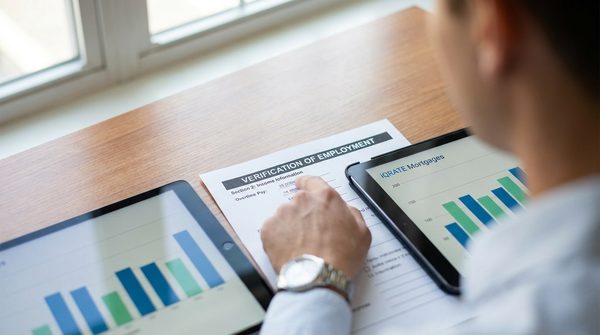
The single most important document for proving your variable income is the Verification of Employment, or VOE. Your pay stubs and W-2s are important, but the VOE is the official form your lender sends to your employer's Human Resources or payroll department. It breaks down your income in the exact format underwriters need to see. A generic or incomplete VOE can delay your loan or lead to your overtime being rejected.
A properly completed VOE for a nurse in Houston must clearly separate:
- Base Pay Rate: Your standard hourly wage.
- Guaranteed Hours: The number of hours you are scheduled to work per week (e.g., 36 or 40).
- YTD Base Earnings: Your total base pay for the current year.
- YTD Overtime Earnings: Your total overtime pay for the current year.
- YTD Differential/Bonus Earnings: All other non-base pay, clearly itemized if possible.
- Previous Year's Earnings: A breakdown of base, overtime, and bonus for the prior full year.
- Prior-Prior Year's Earnings: The same breakdown for the year before that.
- Likelihood of Continuance: A crucial field where your employer confirms if your overtime and differential pay are likely to continue. The answer must be 'Yes' or 'Likely'.
Why Your Pay Stub Isn't Enough for Fort Worth Lenders
Many nurses assume their detailed pay stubs are sufficient proof of income. While helpful, pay stubs often lack the historical context an underwriter needs. They don't show the two-year breakdown, and they don't include the employer's official confirmation that the income is stable. The VOE consolidates all this information into a standardized format that fits directly into the lender's underwriting models. A mortgage officer experienced with nurse loans will know exactly how to work with your HR department to ensure the VOE is filled out correctly the first time.
The Role of a Human Resources Letter
In some cases, a VOE might not tell the whole story, or an underwriter may have follow-up questions. This is when a formal Letter of Explanation (LOE) from your Human Resources department can be invaluable. This isn't always required, but it can be a powerful tool to clarify your income situation.
An HR letter is most useful when:
- You recently received a significant pay raise that isn't fully reflected in your YTD average.
- You switched from a salaried nursing role to an hourly-plus-overtime position within the same hospital system.
- Your hospital has a standard overtime policy for your unit that guarantees a certain level of opportunity for extra hours.
- The VOE form itself doesn't have enough space to properly break down different types of pay (e.g., on-call, charge pay, shift differential).
The letter should be on official hospital letterhead, signed by an authorized HR or payroll representative, and clearly state facts about your employment and compensation structure. It should not make promises, but rather clarify historical data and explain hospital policies that support the stability of your variable income.
Qualifying for a Mortgage After Changing Hospitals
Changing jobs is a normal part of advancing a nursing career, but it can complicate the two-year history rule. If you've been at your current hospital in Dallas for less than two years, can you still get your overtime counted? The answer is yes, but it requires more documentation.
If you moved from one hospital to another in a similar role and pay structure (e.g., floor nurse to floor nurse), lenders can often bridge the employment history. You will need to provide:
- A VOE from your current employer.
- A final VOE from your previous employer covering your time there.
- Your last pay stub from the previous job.
- W-2s from both employers covering the two-year period.
The key is demonstrating that the type of work and pay structure remained consistent. The underwriter needs to see that you left one job and immediately started a similar one, continuing your pattern of earning overtime. A gap in employment of more than 30 days can break this continuity and force the two-year clock to restart. (The data, information, or policy mentioned here may vary over time.)
If your job change involved a significant promotion or a switch to a completely different role (e.g., from bedside nursing to an administrative role with no overtime), it becomes much harder to use your previous overtime history.
Getting Per-Diem and Travel Nurse Income Counted
Qualifying with per-diem or travel nurse income is more challenging, but not impossible. These roles are inherently less stable in the eyes of an underwriter. For per-diem (PRN) nurses, lenders will still want to see a two-year history of consistent work, often with the same hospital system or agency. You'll need to show W-2s and VOEs proving you've consistently picked up shifts over that period.
For travel nurses, the process is even more complex. Your income is often a mix of a taxable hourly rate and non-taxable stipends for housing and meals. Most lenders will only count the taxable W-2 portion of your income. (The data, information, or policy mentioned here may vary over time.) To qualify using this income, you will need:
- A minimum two-year history of consistent travel nursing contracts.
- Documentation from your agency showing your contract history with minimal gaps (less than 30 days) between assignments.
- Tax returns for the past two years to show your total taxable earnings.
A skilled mortgage advisor can help structure your application to present this income in the most favorable light, but you should be prepared for extra scrutiny. The stability of your work and the history of renewed contracts are paramount.
Strengthening Your Pre-Approval with Complete Pay Data
To ensure you get pre-approved for a mortgage that reflects your true earning power as a nurse in Texas, you must be proactive. Don't simply hand over a pay stub and hope for the best. Taking these steps will result in a stronger, more reliable pre-approval.
- Gather Two Years of Documentation: Before you even speak to a lender, collect your last two years of W-2s, tax returns, and your last 30 days of pay stubs.
- Calculate Your Own Average: Do the math yourself. Calculate your 24-month average variable income so you have a realistic expectation of what a lender will use.
- Find the Right Mortgage Partner: Work with a mortgage officer or broker who explicitly states they have experience with nurse loans. Ask them directly how they handle overtime and differential pay.
- Communicate with Your HR Department: Let your HR or payroll department know that a Verification of Employment will be coming. Explain that it's crucial for the form to be filled out completely, with all income types broken down by year.
By treating your variable pay as a core part of your compensation and providing the clear, long-term documentation lenders require, you can confidently shop for a home in Houston, Dallas, or Fort Worth knowing your pre-approval is based on the full income you work so hard to earn.
If you are a nurse in Texas struggling to get your full income counted, it's important to work with a mortgage professional who understands your unique pay structure. A specialist can help you gather the right documents and present your income to underwriters correctly, maximizing your chances of approval. When you're ready to get started, Apply for a Mortgage to begin the process with a team experienced in helping nurses like you.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
Fannie Mae Selling Guide: B3-3.1-02, Variable Income
CFPB: What information do I have to provide a lender to apply for a mortgage?









