

Your First Step After Receiving PCS Orders Mid-Loan
Receiving unexpected PCS orders while you're under contract for a home in Killeen or El Paso can feel like a major setback. The first and most critical action is to communicate. Immediately inform your loan officer and real estate agent. Do not wait. This is a common scenario for military families, and mortgage professionals experienced with VA loans have established procedures to handle it.
Provide them with a copy of your official orders as soon as you have them. These documents are the proof the lender needs to adjust your file and begin the necessary steps. Early communication prevents closing delays and ensures your team can assemble the right paperwork, like a Special Power of Attorney (SPOA), to keep your purchase on track.
How a Special Power of Attorney Works for a VA Mortgage in El Paso
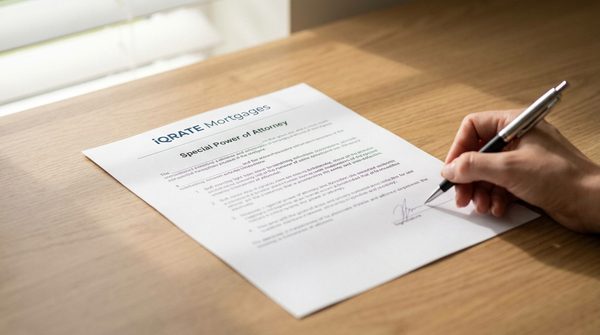
A Power of Attorney (POA) is a legal document that lets you appoint someone, called an 'attorney-in-fact', to act on your behalf. For a VA mortgage, you cannot use a generic, all-purpose POA. You need a Special Power of Attorney (SPOA) that is specifically tailored to the real estate transaction.
Here’s how it works:
- Request the SPOA from Your Lender: Your lender and the title company have specific language that must be included in the SPOA. They will provide you with the exact document or a template to use. This isn't a form you download from the internet.
- Appoint Your Attorney-in-Fact: In most cases, this will be your spouse who is co-borrowing or will be present for the closing. The SPOA grants them the specific authority to sign the mortgage note, deed of trust, and other closing documents for you.
- Proper Execution: You must sign the SPOA in the presence of a notary public. If you are on base, the Staff Judge Advocate (SJA) or a legal assistance officer can often provide this service free of charge.
This specific document ensures the transaction is legally sound and meets all requirements set by the lender, title company, and the Department of Veterans Affairs. Using a lender-approved SPOA is non-negotiable for a smooth closing in El Paso.
Can My Spouse Close on the House in Killeen Without Me?
Yes, absolutely. This is the primary purpose of the Special Power of Attorney. Once the SPOA is properly executed and approved by your lender and the title company, your spouse has the full legal authority to sign the final closing documents on your behalf.
Imagine this scenario: You are buying a home for $320,000 in Killeen to be close to Fort Cavazos. Closing is set for June 15th, but you receive orders to report to a new duty station by June 10th. With an approved SPOA, your spouse can attend the closing appointment, sign their own name where required, and then sign your name as your attorney-in-fact. The sale proceeds just as if you were there in person.
This process ensures your absence doesn't jeopardize the purchase of your family's new home.
Meeting VA Loan Occupancy Requirements When Deployed
The VA loan program is designed for primary residences, meaning the veteran must certify that they intend to occupy the property within a reasonable time, typically 60 days after closing. (The data, information, or policy mentioned here may vary over time.) So, how does this work if you're immediately deploying from your new home in El Paso?
The VA has a critical exception for active-duty service members:
- Spouse Occupancy: If you have a spouse, their occupancy of the home fulfills the requirement on your behalf. As long as your spouse moves into the home within that reasonable timeframe, you are in full compliance with VA guidelines.
- Intermittent Occupancy: If you are single, the rules are stricter. You may need to prove that you will occupy the home during periods of leave. This scenario requires a much more detailed conversation with your lender to ensure VA compliance.
For most military families, the spouse's presence is the key. Your lender will require you to sign a certification at closing stating your intent, and your spouse's move-in will be the proof needed to satisfy the underwriter and the VA.
Will My New Orders Affect My Final Loan Approval?
Generally, no. Lenders understand that PCS orders are a part of military life. Your loan approval is based on credit, assets, and—most importantly—stable, reliable income. Since your military income and employment are guaranteed to continue at your new duty station, the change in location itself doesn't threaten your loan approval.
The lender’s primary concern is confirming that your financial situation remains stable. They will ask for your PCS orders to verify the new duty station and ensure there are no negative changes to your pay, such as a loss of special duty pay that was used for qualification. As long as your income remains the same or increases, your final approval should not be affected.
Essential Military Documents the Lender Needs
To process the change and prepare for a remote closing, your lender will need a few key documents. Having these ready will speed up the process significantly.
- A Complete Copy of Your PCS Orders: This is the most important document. It officially verifies your new duty station, reporting date, and the reason for your move.
- Your Latest Leave and Earnings Statement (LES): The lender will review your LES to confirm your pay, allowances, and rank are consistent with what was used in the initial loan application.
- The Executed Special Power of Attorney (SPOA): As discussed, this must be the lender-approved version, signed by you and properly notarized.
Who Coordinates This Process From a Distance?
Navigating this process requires a knowledgeable team. Your main point of contact is your loan officer. An experienced mortgage professional, particularly one who specializes in VA loans, will act as the quarterback for the transaction.
They will:
- Communicate with the title company to get the SPOA approved.
- Work with the underwriter to clear any new conditions related to your orders.
- Coordinate with your real estate agent to ensure the closing schedule is updated.
- Guide you and your spouse on exactly what needs to be signed and when.
Working with a lender who understands the unique challenges of military life, such as sudden PCS orders for families trying to buy a home in Killeen or El Paso, is the single most important factor in ensuring a stress-free closing.
Received unexpected PCS orders? A smooth home closing is still possible. Our VA loan specialists are ready to navigate the paperwork and keep your purchase on track. Start the conversation and get the expert support you need by submitting your details to Apply now.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.









