

The Flaw in Traditional Pre-Approvals for Forecasting
For real estate team leads and brokers in Texas, the monthly pipeline meeting can feel like an exercise in guesswork. You look at a list of properties under contract, each with a pre-approval letter, and try to build a revenue forecast. Yet, week after week, deals that looked solid suddenly collapse in underwriting, leaving you with a commission gap and a frustrated agent. The fundamental problem is that a standard pre-approval is not a guarantee of funding; it is a preliminary, often automated, assessment.
Most pre-approvals are generated by an Automated Underwriting System (AUS) like Fannie Mae's Desktop Underwriter (DU) or Freddie Mac's Loan Product Advisor (LP). These systems are powerful, but they make assumptions based on the initial data provided. An AUS might issue an 'Approve/Eligible' finding for a Dallas homebuyer based on stated income and a credit pull. However, it hasn't seen the actual bank statements, tax returns, or a detailed breakdown of self-employment income. The letter provides a false sense of security, which is why a deal can fall apart when a human underwriter starts verifying the documents and discovers inconsistencies the algorithm missed.
Decoding the Commission Certainty Score
A Commission Certainty Score replaces this ambiguity with a data-driven probability. It is a proprietary metric, typically ranging from 1% to 100%, that represents the statistical likelihood of a specific loan file reaching the closing table. Instead of relying on a simple AUS finding, the score is calculated by analyzing key data points that directly correlate with underwriting success.
Key Data Points That Determine the Score
- Credit Profile Consistency: The score analyzes not just the credit score itself, but the stability of the profile. Does the borrower have a history of late payments that were recently resolved? Are there new credit inquiries that could signal additional, undisclosed debt? A clean, stable history results in a higher score.
- Income & Employment Verification Strength: A salaried W-2 employee at a major Houston corporation for ten years presents a low-risk profile. In contrast, a self-employed contractor with fluctuating income and complex business write-offs requires deeper analysis. The score weighs the quality and verifiability of the income source heavily.
- Asset Documentation Quality: The system assesses the source and seasoning of funds for the down payment and closing costs. Are the funds from a 401(k) loan, a gift from a relative, or seasoned in a checking account for over 60 days? Each source carries a different risk weight, directly impacting the certainty score. (The data, information, or policy mentioned here may vary over time.)
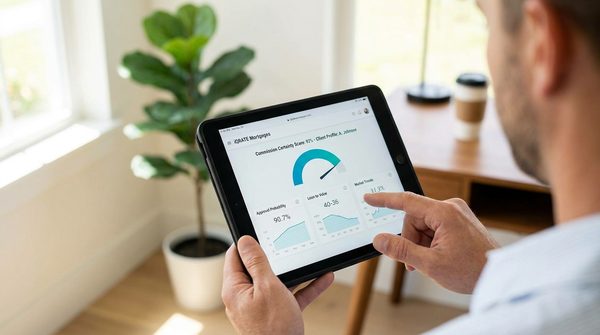
- Property Type & Complexity: A standard single-family residence in a well-established Austin suburb is straightforward. A non-warrantable condo or a property with unique zoning issues introduces variables that can complicate the appraisal and final loan approval, thus lowering the initial score.
How Lender Underwriting Impacts Closing Predictability
The lender's internal process is a massive variable in closing predictability. A large retail bank often has rigid, black-and-white underwriting guidelines. If a file deviates even slightly, it gets denied with little room for appeal. This inflexibility is a primary cause of last-minute deal collapses.
A mortgage partner who pre-underwrites files before submitting them significantly increases predictability. This involves having an experienced loan officer or processor review every document with an underwriter's mindset. They identify potential red flags—like unexplained large deposits or a recent job change—and resolve them before the file is officially submitted. This proactive approach is a core component of a high Commission Certainty Score.
For example, if a Houston buyer's file receives an initial score of 75% due to complex commission-based income, a skilled mortgage team can work to gather two years of tax returns and a detailed verification of employment to address the specific underwriting concern. As this documentation is provided and verified, the score might increase to 95%, reflecting the reduced risk and higher probability of closing.
Strategic Resource Allocation for Your Team
Imagine you are a broker in Dallas managing a team of ten agents. Your pipeline has 30 deals pending. Without a certainty score, you treat all 30 deals more or less equally. With the score, you can manage your resources with surgical precision.
You can sort your pipeline by score. The deals with a 95-100% certainty score are on a clear path to closing. They require standard follow-up. The deals in the 70-85% range are the ones that need your attention. These are viable loans that have one or two outstanding conditions. You can allocate your best transaction coordinator or have a senior agent mentor the file's owner to ensure those conditions are met swiftly.
The deals scoring below 70% are the critical ones. These are the files at high risk of falling apart. Instead of wasting weeks on a deal that was never going to close, you can intervene immediately. You can have a direct conversation with the mortgage officer to understand the core issues and decide if the deal is salvageable or if your agent's time is better spent finding a more qualified buyer.
Transforming Your Pipeline Meetings
The Commission Certainty Score changes the entire dynamic of your pipeline meetings, moving them from subjective status updates to objective, data-driven strategy sessions.
Old Question: 'How's the Johnson file going?' Agent Response: 'It's going great! They're really excited.'
New Question: 'The Johnson file in Houston has a score of 78%. The system flagged inconsistent asset documentation. What's the plan to resolve that by Friday?' Agent Response: 'The lender needs a gift letter and a source statement for the down payment funds from the buyer's father. I'm meeting him this afternoon to get it signed.'
This new approach allows you to:
- Identify Bottlenecks: Instantly see which files are stuck and why.
- Enforce Accountability: Agents and lenders have clear, measurable tasks tied to improving the score.
- Forecast with Confidence: You can create tiered revenue forecasts. For example, you can project 100% of the commission from deals over 90%, 75% from deals between 75-89%, and 50% from those below. This creates a realistic, data-backed financial picture for your brokerage.
Integrating Scoring into Your Workflow
Adopting a data-driven system requires seamless integration to avoid disrupting your team's existing processes. It also offers powerful benefits beyond simple forecasting, especially when it comes to strategic growth.
CRM Integration Process
Modern mortgage partners can integrate the Commission Certainty Score directly into your existing Customer Relationship Management (CRM) platform. This is often accomplished via an API or a dedicated web portal. The goal is to have the score appear as a field on each client's record, updated in real-time as new documents are submitted and milestones are cleared. This puts critical forecasting data where your team already spends their time, requiring no extra logins or separate spreadsheets.
Reducing New Agent Hiring Risk
Hiring a new agent is one of the biggest financial risks for a brokerage. You invest time, money, and resources with the hope of future returns. The Commission Certainty Score provides a powerful metric for evaluating a new hire's performance during their crucial first 90 days.
Instead of just measuring the number of contracts they get signed, you can measure the quality of their pipeline. A new agent in Austin who brings in three contracts with an average certainty score of 92% is demonstrating a far greater ability to identify and work with qualified buyers than an agent who brings in five contracts with an average score of 65%. This data allows you to make informed decisions about continued investment in that agent and identify specific areas where they may need more training.
Managing Real-Time Changes: The Low Appraisal Scenario
The value of a dynamic scoring system is most apparent when unforeseen problems arise. A classic deal-killer is a low appraisal. Let's say a property in Dallas is under contract for $550,000, and the buyer's loan file has a solid 95% Commission Certainty Score. Everything looks perfect.
Then, the appraisal comes in at $525,000.
Instantly, the score adjusts downward—perhaps to 60%—because the loan-to-value ratio is now out of alignment, and the original loan terms are no longer valid. However, the system doesn't just flag the problem; it illuminates the path forward. The score will only improve once a specific action is taken. The options become clear:
- The buyer brings an additional $25,000 to closing.
- The seller agrees to reduce the price to the appraised value.
- Buyer and seller negotiate a new price in the middle.
- The appraisal is successfully challenged with new comparable sales.
As soon as one of these resolutions is documented, the score recalculates, providing a real-time, accurate reflection of the deal's health. This turns a moment of panic into a structured, problem-solving opportunity, allowing brokers and agents to act decisively to save the deal.
Ready to transform your forecasting from guesswork to a predictable science? Stabilize your commission income by partnering with a team that provides data-driven certainty. Take the first step towards a more reliable pipeline and Apply now to experience the difference.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
The mortgage closing process - Consumer Financial Protection Bureau









