Written and reviewed by David Ghazaryan, Mortgage Broker, NMLS 1486726 · iQRATE Mortgages, NMLS 1862492 · 6360 S Rainbow Blvd, Las Vegas, NV · Last updated: October 24, 2026
Quick answer: In 2026, any Summerlin purchase where the loan amount is above $832,750 (the FHFA one-unit conforming limit for Clark County) is a jumbo loan. Guard-gated and golf course homes in places like The Ridges, The Summit, Red Rock Country Club, Eagle Hills and Tournament Hills qualify the same way any jumbo does, but underwriters look harder at three things: the appraisal, the full monthly housing cost (master HOA, sub-HOA, any SID and any mandatory dues) and your cash reserves. If you plan for those three before you write the offer, a Summerlin jumbo is usually a clean file.
Summerlin buyers who call our office on South Rainbow tend to ask us the same three questions. Is the house "too unique" to appraise? Do the club dues count against me? How much cash do I really need left over after closing? This guide walks through each one in plain English.
What counts as a jumbo loan in Summerlin in 2026
The line is set by the Federal Housing Finance Agency (FHFA). For 2026, the baseline conforming loan limit for a one-unit home is $832,750, and Clark County sits at that baseline. Clark County is not a "high-cost" county, so there is no high-balance tier between conforming and jumbo here like there is in parts of California.
Two things people miss:
- The limit is on the loan amount, not the price. A buyer putting a large down payment on a home in The Ridges can still end up with a conforming loan. A buyer putting less down on a home in a non-gated Summerlin village can end up in jumbo territory.
- The limit changes every year. FHFA announces the next year's number each November. If you're buying in early 2027, ask us to re-check where your loan lands.
If you want the full breakdown of how Nevada jumbo programs differ from conforming loans, start with our jumbo loan page.
Where Summerlin's guard-gated and golf homes are
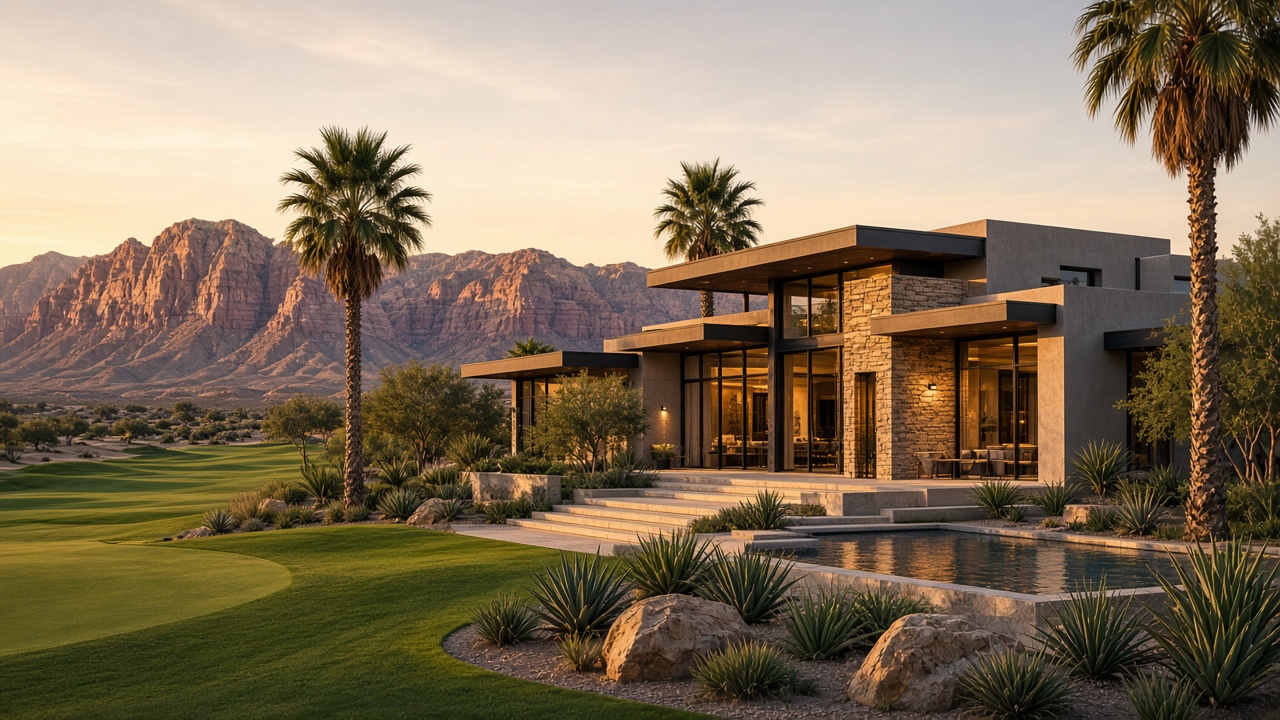
Summerlin is the Howard Hughes master-planned community along the western edge of the valley, below Red Rock Canyon National Conservation Area. The luxury inventory clusters in a handful of places:
- The Ridges. A 793-acre guard-gated village with the community's largest concentration of custom homes. Its golf course, originally a Jack Nicklaus Bear's Best layout, is being reworked as the private Amara Golf Club.
- The Summit. A 555-acre luxury neighborhood with a private, resident-only Tom Fazio course.
- Eagle Hills and Tournament Hills. Older guard-gated custom enclaves near TPC Summerlin, the private TPC Network course (licensed by the PGA TOUR), designed by Bobby Weed.
- Red Rock Country Club. A guard-gated community built around two Arnold Palmer courses, the private Mountain Course and the semi-private Arroyo Course. Worth knowing: Summerlin's own history materials note that Red Rock Country Club is not technically part of the Summerlin master plan, even though most buyers shop it as "Summerlin." That matters when we pull HOA documents, because the association structure is different.
From a loan standpoint, none of these neighborhoods is a problem. What changes is how much homework the underwriter does on the property and the monthly costs.
Why guard-gated and golf course homes get extra underwriting attention
1. The appraisal on a custom home
Custom homes with big view lots, golf frontage or one-off architecture have fewer true comparable sales. An appraiser working a home in The Ridges may have only a few closed custom sales in the last six to twelve months, and some of those may be in another enclave with different views and lot sizes.
What that means for you:
- The appraiser may need to reach further back in time or further out in distance for comps, and the underwriter will read those adjustments closely.
- Some jumbo programs require a second appraisal above a certain loan size or in certain situations. If yours does, you want to know before you remove contingencies, not after.
- If the appraisal comes in below the contract price, the lender lends off the lower number. You either renegotiate, bring more cash or change the loan structure.
We ask listing agents for recent closed sales they used to set the price, and we pass them to the appraisal management company through the proper channel. We can't influence the value, but we can make sure the appraiser has the facts.
2. Layered HOA dues and the true housing payment
Summerlin homes typically sit under one of the master associations (Summerlin North and Summerlin West are separate master associations), and most homes also pay a village or sub-association. Guard-gated neighborhoods add staffed gates and private streets on top. The underwriter counts every required monthly assessment in your debt-to-income ratio.
So when you compare two homes at a similar price, don't compare list prices. Compare the full monthly number: principal and interest, property taxes, insurance, every HOA layer, and any special assessment.
3. Special Improvement Districts (SIDs)
Parts of Summerlin sit inside Clark County Special Improvement Districts that paid for roads and infrastructure. A SID assessment is separate from both your property tax and your HOA dues, it's billed twice a year, and the remaining balance generally stays with the property when it sells. Lenders count it as part of your housing cost. We walk through how these work in our guide to Nevada SID and LID fees.
4. Club memberships
In many Summerlin-area golf communities, the club membership is sold separately from the house. If the membership is optional, most lenders don't count the dues because you're not required to pay them. If the community's documents make a membership or dues mandatory for owners, expect the underwriter to treat those dues like an HOA payment. We read the CC&Rs and the resale package early so this never shows up as a surprise in underwriting.
Down payment and reserves for a Summerlin jumbo
Jumbo programs vary by lender, so treat this as a range of what we see, not a quote.
- Down payment. Many jumbo programs top out at 80 percent of the price for a one-unit primary residence, with lower limits as the loan amount gets bigger. Some lenders offer less than 20 percent down, usually with tighter credit and reserve rules.
- Reserves. Jumbo lenders want to see money left over after closing, measured in months of your full housing payment. Jumbo lenders commonly want several months of reserves, and more as the loan size goes up or when the home is a second home or investment property. We confirm the exact number with the lender we match you to.
- Other homes you own. Many jumbo programs also add reserves for each other financed property you own, sized to that property's payment. Plenty of Summerlin buyers own a California home or a rental, so this adds up quickly.
For a deeper look, see our 2026 guide to Las Vegas jumbo down payment and reserves.
Primary home or second home?
A lot of Summerlin luxury buyers split time between Las Vegas and somewhere else. Lenders price and qualify a primary residence, a second home and an investment property differently, and you have to pick the one that's true. A primary residence means you plan to live there as your main home. A second home is one you use part of the year and don't rent out as a business. Tell us how you'll actually use the home and we'll match the program to it. Getting occupancy wrong isn't a paperwork issue; it's a misrepresentation issue.
What we'd do
If you told us today that you're shopping guard-gated or golf course homes in Summerlin, here's how we'd set it up:
- Review your file before you shop. Income, assets and credit checked up front (and sent to underwriting early when the lender allows it) so your pre-approval letter holds up in a multiple-offer situation.
- Build a "true payment" sheet for each house you're serious about, with every HOA layer, any SID balance and any mandatory dues.
- Shop the loan across our lender network for the program that fits your file: full-doc jumbo, bank statement jumbo for business owners or asset-based qualifying if most of your wealth is in investments.
- Plan for the appraisal. We gather comp support, confirm whether a second appraisal applies and set your appraisal contingency timing to match.
- Map your reserves so you know exactly which accounts count and how much you need to leave untouched.
Want us to run your numbers? Call our Las Vegas office or start on our jumbo loan page.
FAQ
What is the jumbo loan limit in Summerlin for 2026?
Summerlin is in Clark County, where the 2026 one-unit conforming loan limit is $832,750, the FHFA national baseline. Any loan above that on a one-unit home is a jumbo loan.
Do HOA dues in a guard-gated Summerlin community affect my jumbo approval?
Yes. Every required HOA assessment, including the master association, the village or sub-association and the guard-gate costs built into those dues, counts in your debt-to-income ratio. We total them before you write an offer.
Do golf club dues count against me on a jumbo loan?
Only if they're mandatory. If membership is optional, lenders generally ignore it. If the community's documents require owners to pay club dues, the underwriter will usually count them like an HOA payment.
Can a custom home in The Ridges have trouble appraising?
It can. Custom homes with unique views or architecture have fewer comparable sales, so appraisers sometimes have to reach further for comps. We give the appraiser solid sales data through the proper channel and plan your contingency timing around it.
How much cash should I have left after closing on a Summerlin jumbo?
It depends on the lender, the loan size and how many other properties you finance. Reserve rules are stated in months of your full housing payment and go up as the loan gets bigger. We'll show you the exact requirement for your scenario before you commit.
Investor loans are for business-purpose use only.
iQRATE Mortgages LLC, NMLS 1862492. Equal Housing Opportunity. Not a commitment to lend; terms subject to underwriting.