

How a VA Interest Rate Reduction Refinance Loan Works in Miami
A Veteran Affairs Interest Rate Reduction Refinance Loan, often called a 'VA Streamline', is a powerful tool exclusively for veterans who already have a VA-backed home loan. Its primary purpose is to lower your interest rate and, consequently, your monthly mortgage payment. Unlike a traditional refinance, the process in cities like Miami is significantly streamlined.
Here’s the simplified breakdown:
- Less Paperwork: Lenders typically do not require a new appraisal, income verification, or credit underwriting. The main qualification is a history of on-time mortgage payments. (The data, information, or policy mentioned here may vary over time.)
- Primary Goal: The refinance must result in a lower interest rate. The only exception is if you are refinancing from an adjustable-rate mortgage (ARM) to a fixed-rate mortgage.
- No Cash-Out: The IRRRL program does not allow you to take cash out of your home's equity. It is strictly for rate and term reduction. If you need cash, you would need to explore a VA cash-out refinance, which has different requirements.
- Occupancy Requirement: You only need to certify that you previously occupied the home. This makes the IRRRL an excellent option for veterans who have since moved and now use their property as a rental.
The core benefit is the speed and reduced documentation. A lender can see that you have a proven track record of paying your VA loan, so the VA guarantees the new loan with less friction, making it a faster and less stressful process for homeowners in busy markets like South Florida.
The 'Net Tangible Benefit' Test
To protect veterans from predatory lending, the VA requires that every IRRRL provides a 'net tangible benefit' to the borrower. This means the refinance must put you in a demonstrably better financial position. The rules are specific:
- Lowering Payments: The new payment must be lower than the previous one.
- Fixed Rate: The new loan must be a fixed-rate loan if the old one was an ARM.
- Recoupment Period: The time it takes to recoup all closing costs and fees must not exceed 36 months. This is a crucial calculation we will explore later. (The data, information, or policy mentioned here may vary over time.)
This test prevents lenders from churning loans where the benefit to the veteran is minimal, but the lender profits from fees.
What 'No-Cost' Truly Means on a VA Loan Offer in Orlando
Veterans in Orlando and across Florida are frequently targeted with mailers and ads promising a 'no-cost' or 'zero-closing-cost' VA IRRRL. This marketing is appealing but requires careful scrutiny. There is no such thing as a truly free mortgage refinance; the costs are simply paid in a different way.
Here are the two common scenarios behind a 'no-cost' offer:
- Lender Credits (Higher Interest Rate): In this model, the lender agrees to pay your closing costs for you. In exchange, they give you a slightly higher interest rate than the absolute lowest market rate available. For example, if the best rate is 5.5%, they might offer you a 'no-cost' loan at 5.875%. The extra interest you pay over the life of the loan compensates the lender for the upfront costs they covered. This can be a good option if you are short on cash, but it means a slightly smaller monthly saving.
- Rolling Costs into the Loan: This is the more common method. The closing costs are not paid by you out-of-pocket at closing. Instead, they are added to your new loan principal. If you refinance a $350,000 loan and the costs are $5,000, your new loan balance becomes $355,000. While you bring no cash to closing, your loan balance has increased.
Neither option is inherently bad, but the term 'no-cost' is misleading. It simply means no cash required at closing. You are still paying for the transaction, either through a higher long-term interest expense or a larger loan balance.
How to Calculate the Break-Even Point for Your Refinance
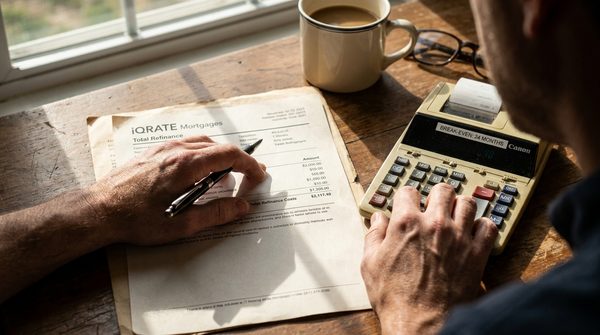
Calculating your break-even point, or recoupment period, is the single most important step in evaluating an IRRRL offer. It tells you how many months it will take for your monthly savings to cover the total cost of the refinance. If you plan to sell your home before you hit this point, the refinance will have cost you money.
The formula is straightforward:
Total Closing Costs / Monthly Savings = Months to Break Even
Let’s use a realistic example for a home in Miami:
- Current Loan Balance: $400,000
- Current Principal & Interest (P&I) Payment at 6.5%: $2,528
- New P&I Payment at 5.5%: $2,271
- Monthly Savings: $2,528 - $2,271 = $257
- Total Closing Costs (including VA Funding Fee): $6,200
Now, apply the formula:
$6,200 (Total Costs) / $257 (Monthly Savings) = 24.12 months
In this scenario, it would take you just over 24 months to recoup the costs of the refinance. If you plan on staying in your Miami home for at least two more years, this IRRRL is a financially sound decision. The VA's 36-month recoupment rule ensures you break even relatively quickly.
What Specific Closing Costs Can Be Rolled into the New Loan?
With a VA IRRRL, most of the fees associated with the transaction can be rolled into the new loan amount, which is why 'no cash to close' is so common. It’s important to understand what these fees are so you can review them on your Loan Estimate.
Common costs that can be financed include:
- VA Funding Fee: This is a mandatory fee paid to the VA to help fund the loan guarantee program. For an IRRRL, it is a flat 0.5% of the loan amount for all veterans, regardless of service history or down payment. Some veterans receiving VA disability compensation are exempt from this fee.
- Origination Fee: This is the lender's charge for processing and underwriting the loan. It is often capped at 1% of the loan amount. (The data, information, or policy mentioned here may vary over time.)
- Discount Points: These are optional fees you can pay to 'buy down' your interest rate. One point typically costs 1% of the loan amount. (The data, information, or policy mentioned here may vary over time.)
- Title Insurance and Search Fees: Costs to ensure the property title is clear and to issue a new title insurance policy for the lender. (The data, information, or policy mentioned here may vary over time.)
- Recording Fees: The fee charged by the county to officially record the new mortgage deed. (The data, information, or policy mentioned here may vary over time.)
- Credit Report Fee: A nominal fee to pull your credit history. (The data, information, or policy mentioned here may vary over time.)
It is critical to get a Loan Estimate from any lender you consider. This standardized three-page document clearly itemizes every single fee. You can compare these documents side-by-side to see which lender offers the best overall deal.
When Accepting an IRRRL Offer Is a Bad Idea
While an IRRRL is often beneficial, it's not a smart move in every situation. Accepting an offer without considering the bigger picture can be a costly mistake.
Here are scenarios where an IRRRL might be a bad idea:
- Short-Term Ownership: If you plan to sell your home in Orlando within the next year or two, you likely won't have enough time to pass your break-even point. In that case, the closing costs would exceed any savings you realized.
- Resetting the Clock on a Shorter Loan: If you are 10 years into a 30-year mortgage, refinancing into a new 30-year mortgage resets your amortization schedule. While your monthly payment will drop, you will pay significantly more in total interest over the life of the new loan. Always ask for a quote on a shorter term, like a 20-year or 15-year loan, to see if you can handle the payment.
- High Costs, Minimal Savings: If the interest rate reduction is very small (e.g., 0.25%), your monthly savings might be minimal. If the closing costs are high, it could take many years to break even, violating the VA's 36-month recoupment rule. A reputable lender would not proceed with such an offer.
- Skipping Payments Misconception: Some lenders advertise that you can 'skip one or two mortgage payments' with a refinance. You are not skipping payments; you are deferring them. The interest for those months is rolled into your new loan balance, meaning you pay interest on that interest for years to come. It’s a gimmick that increases your total cost.
How to Compare Multiple IRRRL Offers from Lenders in Florida
Shopping around is essential. A 0.25% difference in interest rate can save you thousands of dollars over the life of the loan. When comparing IRRRL offers from different lenders in Florida, focus on the official Loan Estimate document.
Here’s a checklist for an effective comparison:
- Section A: Origination Charges: Look at Box A on page 2 of the Loan Estimate. This is the lender’s direct profit. Compare this number carefully between lenders. A low interest rate might be paired with a high origination fee.
- Interest Rate vs. APR: The interest rate is used to calculate your monthly payment. The Annual Percentage Rate (APR) includes both the interest rate and most of the closing costs, expressed as a percentage. The APR is a more accurate tool for comparing the total cost of different loans.
- Discount Points: Check if the lender is charging you points to achieve the quoted rate. An offer with zero points and a 5.75% rate might be better than an offer with one point and a 5.5% rate, depending on the cost of the point and your break-even calculation.
- Lender Credits: If you are considering a 'no-cost' offer, look for lender credits in Section J of the Loan Estimate. This shows how much the lender is contributing to your closing costs.
Always ask for a Loan Estimate based on the same terms (e.g., a 30-year fixed loan with no points) from at least three different lenders to make an accurate, apples-to-apples comparison.
Can a Streamline Refinance Actually Increase My Total Loan Balance?
Yes, absolutely. This is one of the most common misunderstandings about the VA IRRRL program. Unless the lender is providing a significant credit to cover all your costs (which is rare), your loan balance will almost certainly increase if you choose to finance the closing costs.
Let’s revisit our Orlando homeowner:
- Original Loan Balance: $350,000
- Total Closing Costs (including 0.5% VA Funding Fee of $1,750): $5,000
If the homeowner rolls these costs into the new loan, their new principal balance will be $355,000. Even though their monthly payment has gone down due to the lower interest rate, they now owe more money than they did before the refinance. This is why the break-even calculation is so important. The goal is for the long-term interest savings to far outweigh the small increase in principal.
Key Questions to Ask a Lender About Their IRRRL Offer
Before you commit, arm yourself with knowledge. Treat the conversation like an interview where you are vetting the lender. Here are the crucial questions to ask:
- 'Can you please send me an official Loan Estimate? I want to review all the itemized fees.'
- 'What is the total amount of closing costs that will be rolled into my new loan balance?'
- 'Are there any discount points included in this interest rate quote?'
- 'Based on these costs and my monthly savings, what is my exact break-even point in months?'
- 'Can you show me a quote for a shorter loan term, such as 20 or 25 years, in addition to the 30-year option?'
- 'Are you escrowing my property taxes and insurance, and what is the initial escrow deposit amount?'
- 'Is your lender origination fee negotiable?'
A transparent and trustworthy loan officer will be able to answer these questions clearly and without hesitation. If they are evasive or pressure you to move forward without documentation, it is a major red flag.
If a VA Streamline Refinance sounds like the right move for you, a transparent analysis is the next step. Calculate your true savings and break-even point to make an informed decision. Apply now for a clear, honest quote.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
VA IRRRL Program | U.S. Department of Veterans Affairs
Closing Disclosure Explainer | Consumer Financial Protection Bureau









