
Why Foreign Gift Funds for a Los Angeles Home Purchase Are Scrutinized
When you're trying to secure a jumbo loan for a home in Los Angeles or Beverly Hills, the down payment is a significant hurdle. A generous gift from parents living abroad can seem like the perfect solution, but to a mortgage underwriter, it’s a major red flag. This isn't because lenders are biased against international help; it's because they are legally required to comply with federal regulations like the Bank Secrecy Act (BSA) and Anti-Money Laundering (AML) laws. These rules mandate that lenders verify the source of every dollar used in a real estate transaction to prevent illegal financial activities.
Foreign funds are inherently harder to trace. Underwriters have no easy way to verify the legitimacy of a foreign bank or the origin of the money within it. Their primary goal is to ensure the funds are not from an unapproved source and are a genuine gift, not an undisclosed loan that would affect your debt-to-income ratio.
What is the Correct Way to Transfer Money From a Foreign Account?
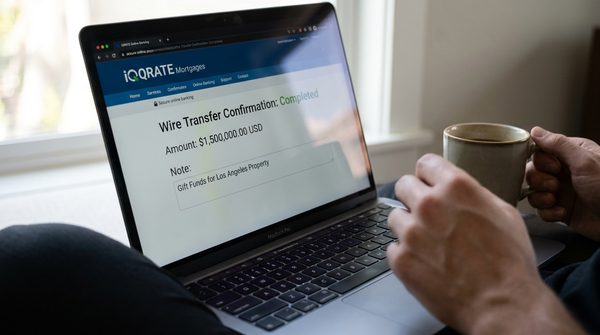
The cleanest and most acceptable method for transferring gift funds is a direct wire transfer. The money should move in a single, traceable line:
- From the Giver's Foreign Bank Account: The funds must originate directly from the account of the person gifting the money.
- To the Borrower's U.S. Bank Account: The wire must be sent directly to your (the homebuyer's) U.S.-based bank account. Do not use third-party transfer services or have the money sent to a friend or another relative first.
This creates a clear paper trail that the underwriter can follow. Avoid cash deposits at all costs. Depositing large sums of cash, especially foreign currency, is a massive red flag that is nearly impossible to source and will likely result in a loan denial.
What Specific Documents Will My Parents Need to Provide?
Documentation is everything. To get your Los Angeles mortgage approved, you must provide a complete and verifiable paper trail for the gifted funds. Your lender will request the following from your parents (the donors):
- A Copy of Their Bank Statement: This statement must show they had the funds available to gift. It should be the statement from the period just before the wire transfer was initiated.
- Evidence of the Wire Transfer: A copy of the wire receipt from their bank showing the money leaving their account, the date, and the destination account (your U.S. bank account).
- Your Corresponding Bank Statement: You will need to provide your U.S. bank statement showing the exact amount arriving as a wire deposit.
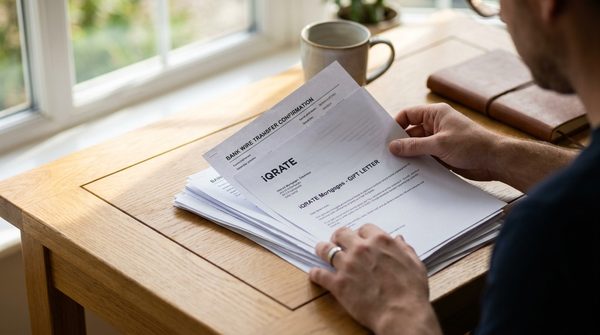
- A Signed Gift Letter: This is a non-negotiable legal document. We'll detail its specific requirements below.
Gathering these documents proactively will save you immense stress and prevent last-minute delays in your closing process.
How Long Do Funds Need to Be Seasoned in a United States Account?
'Seasoning' refers to the length of time money has been sitting in your bank account. For mortgage purposes, funds are typically considered 'seasoned' after they have been in your account for at least 60 days, covering two full bank statement cycles. (The data, information, or policy mentioned here may vary over time.)
- If the Gift is Recent (Less than 60 days): If your parents wire the money and you go into contract on a Beverly Hills home a month later, you must source the funds with all the documentation listed above.
- If the Gift is Seasoned (More than 60 days): If your parents transfer the gift well in advance and the money sits in your U.S. account for over 60 days, it becomes your asset. When the lender reviews your last two months of bank statements, the money will already be there. In this scenario, you typically do not need to provide a gift letter or trace the funds back to your parents' foreign account. Early planning is the key to this simplified approach.
What a Gift Letter Must Include for Foreign Funds
A gift letter is a formal statement confirming the money is a true gift with no expectation of repayment. For foreign gifts, this document must be flawless. It must include:
- The donor's full name, address, and contact information.
- The donor's relationship to you (e.g., 'Mother', 'Father').
- The exact gift amount in U.S. dollars.
- The date the funds were transferred.
- A clear and unambiguous statement that the funds are a gift and that no repayment is expected or implied.
- The full address of the property you are purchasing in Los Angeles.
- The donor's signature and the date.
- Your signature and the date.
Any ambiguity in this letter can cause the underwriter to treat the funds as a loan, which will negatively impact your loan eligibility.
Will We Need Translated Bank Statements for a Beverly Hills Loan?
Yes, absolutely. Any required document that is not originally in English must be accompanied by a complete and accurate translation. You cannot translate the documents yourself, nor can a friend or family member.
The translation must be performed by a certified, independent third-party translator. The translator must also provide a signed certification stating that the translation is accurate and that they are competent to translate from the original language into English. This rule applies to bank statements, legal documents, or any other piece of evidence required by the lender.
How to Avoid Loan Denial Due to Documentation Issues
Having your loan denied over paperwork is frustrating and avoidable. To ensure a smooth process when using foreign gift funds, follow this checklist:
- Plan Far in Advance: If possible, have the gift sent more than 60 days before you plan to apply for a loan to season the funds.
- Use Direct Wire Transfers Only: Insist on a bank-to-bank wire. It is the only acceptable transfer method.
- Gather All Documents Upfront: Collect the gift letter, donor's bank statement, and wire receipts before your loan application is even submitted.
- Secure Certified Translations: Do not wait until the underwriter asks. If your documents aren't in English, get them professionally translated immediately.
- Work With an Expert: A knowledgeable mortgage strategist who has experience with complex financial situations, including foreign assets, can guide you through the process, anticipate underwriter requests, and structure your file for success. If you are planning to use a gift from family abroad for your home purchase, proper guidance is essential. A mortgage strategist experienced with international fund sourcing can help structure the transaction correctly from the start to ensure a smooth and successful closing.
Navigating the complexities of foreign gift funds requires expert guidance. If you're ready to secure your Los Angeles home loan with confidence, Apply now and let our experienced team guide you.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
Fannie Mae: Gift Funds Eligibility
Consumer Financial Protection Bureau (CFPB): Documents needed for mortgage application
FinCEN: Report of Foreign Bank and Financial Accounts (FBAR)