

Eligibility Rules for Guard and Reserve Members
For members of the National Guard and Reserves, qualifying for a VA loan comes with a specific service requirement that differs from active-duty personnel. The primary rule is that you must have completed six creditable years of honorable service. This is the standard benchmark lenders and the Department of Veterans Affairs use to confirm your eligibility for this powerful home financing benefit.
However, there are important exceptions to the six-year rule. If you were called to active duty (under Title 10 or Title 32 orders), the time requirement is significantly shorter. You generally only need to have served 90 consecutive days on active duty to become eligible. This provision ensures that service members who are mobilized for federal missions gain access to the same housing benefits as their active-duty counterparts.
Your service is officially tracked through a retirement points system. Each year, your points summary statement (like NGB Form 23) is the official record that proves you had a 'good year' of service. Lenders will use this document to verify you have met the six-year threshold.
How Lenders Calculate Qualifying Income from Drill Pay
One of the most critical aspects of a VA loan application for a Guard or Reserve member is proving that your military income is stable and likely to continue. Unlike a regular salary, drill pay is periodic. Lenders must convert this into a reliable monthly figure to add to your qualifying income.
Typically, an underwriter will require your Leave and Earnings Statements (LES) for the last 12 months. They will average your total drill pay over this period to establish a consistent monthly income. For example, if your LES shows you earned $4,800 from drills and training over the past year, a lender can add $400 ($4,800 / 12) to your monthly income.
What underwriters look for:
- Consistency: They want to see that you have consistently attended drills without significant gaps.
- Likelihood of Continuance: Your remaining time on your enlistment contract is important. If you have several years left, it shows the income is likely to continue.
- Documentation: Having every LES for the past year is non-negotiable. Missing statements can delay or derail your application.
For a homebuyer in Dallas, adding even $400-$600 in verified monthly drill pay can significantly boost their purchasing power, helping them qualify for a larger loan amount in a competitive market. (The data, information, or policy mentioned here may vary over time.)
Essential Documents for Military Service Verification
To process your VA loan, you must provide a specific set of documents that prove your service history and current status. Having these prepared in advance will streamline your application and prevent unnecessary delays. Your lender will need them to request your Certificate of Eligibility (COE) and verify your income.
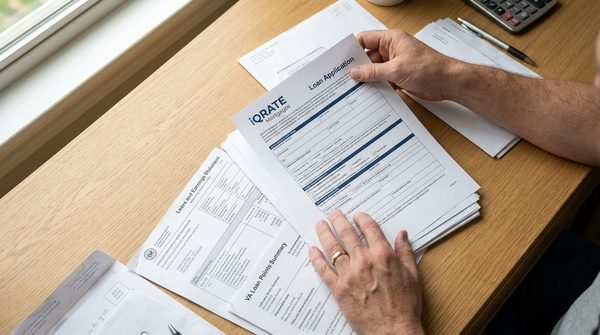
Here is a checklist of the core documents required:
- Retirement Points Statement: This is the most important document for proving six years of creditable service. For Army National Guard, this is the NGB Form 23. For Air National Guard, it's the AF Form 526. For Reserves, it will be your service-specific annual points statement (e.g., DARP Form 249-2-E for Army Reserve).
- Leave and Earnings Statements (LES): As mentioned, you will need a complete set covering the most recent 12 months to verify your drill pay.
- Statement of Service: A letter signed by your commanding officer confirming your name, Social Security number, date of entry, and the duration of your current enlistment contract. This helps prove your income is likely to continue.
- DD Form 214 (if applicable): If you have ever been activated for federal service, you will have a DD Form 214 for that period. This is essential for proving eligibility if you have fewer than six years of total service.
- Copy of Orders: If you are currently on active-duty orders, a copy of those orders will be required.
How Lenders View Your Civilian Job Income in Plano
For most Guard and Reserve members, civilian employment provides the bulk of their qualifying income. Lenders view your civilian job just as they would for any other borrower: they need to see a stable and reliable two-year work history. This demonstrates that you can consistently meet your mortgage obligations.
To verify this income, you will need to provide:
- W-2s for the past two years.
- Pay stubs covering the most recent 30 days.
- Federal tax returns for the last two years, especially if you receive bonuses, commissions, or are self-employed.
A homebuyer in Plano working in a stable industry like technology or healthcare can easily meet this requirement. However, if you have recently changed jobs, underwriters will look closely at the transition. A move for a higher salary within the same field is generally viewed favorably. Frequent job hopping in unrelated industries can be a red flag that requires a detailed letter of explanation.
The Impact of Federal Activation on Your Loan
Being called up for federal service (active duty) changes how a lender analyzes your income. During your activation period, you are treated exactly like an active-duty service member. Your income becomes a steady, predictable salary documented on your LES.
This can simplify the income verification process significantly. Instead of averaging 12 months of variable drill pay, the lender can use your current base pay, Basic Allowance for Housing (BAH), and other entitlements as your qualifying income. If you are applying for a VA loan while deployed or on active-duty orders, the process can sometimes be easier than when you are only drilling.
It is critical to provide your activation orders to the lender. These orders specify the type of duty and its duration, which confirms to the underwriter that the income is stable for the foreseeable future.
Your Certificate of Eligibility (COE): What's Different?
Every VA loan requires a Certificate of Eligibility (COE), which is the official VA document that tells the lender you are eligible for the benefit. While the purpose of the COE is the same for all service members, how it's obtained and what it shows can differ for Guard and Reserve members.
If you have completed your six years, your lender can often obtain the COE for you through the VA's automated system using your service records. However, if the system cannot automatically verify your service, you may need to submit your retirement points statement (NGB Form 23) directly to the VA to have your COE issued manually.
The COE will state your entitlement code. For many Guard and Reserve members, this code is '10'. This simply signifies your branch of service and eligibility category; it does not negatively impact your loan application in any way.
Securing a VA Loan in Fort Worth with Inconsistent Civilian Work
What if your civilian job history isn't perfect? This is a common concern, especially for those whose military duties or activations have interrupted their civilian careers. While a two-year history is the standard, VA loan guidelines are flexible and allow for compensating factors.
If you have gaps in your civilian employment, a lender in Fort Worth can still approve your loan if you can demonstrate other strengths in your financial profile. These include:
- A Strong Letter of Explanation: Clearly explain why the employment gaps occurred. For instance, a gap due to a military activation is a perfectly valid reason.
- Significant Cash Reserves: Having several months of mortgage payments saved in the bank shows you can handle financial uncertainty. (The data, information, or policy mentioned here may vary over time.)
- Excellent Credit: A high credit score indicates a history of responsible debt management.
- Low Debt-to-Income (DTI) Ratio: If your proposed mortgage payment and other debts are a small percentage of your income, it reduces the lender's risk. (The data, information, or policy mentioned here may vary over time.)
The key is to be upfront with your loan officer about your work history. A skilled mortgage professional can help you structure your application to highlight your strengths and mitigate any perceived weaknesses.
Common Application Mistakes to Avoid
Applying for a VA loan as a Guard or Reserve member involves more moving parts than a standard application. Avoiding these common mistakes can lead to a smoother, faster closing.
- Using an Outdated Points Statement: Ensure your NGB Form 23 or equivalent is the most current one available. An outdated form will be rejected.
- Forgetting to Include All Income: Don't forget to include income from military schools, annual training, or other special duty, as it can be averaged into your qualifying income.
- Not Disclosing Employment Gaps: Hiding a gap in your civilian work history will only cause problems when the underwriter discovers it. Be transparent from the start.
- Assuming All Lenders Understand Guard/Reserve Pay: Many loan officers are unfamiliar with the nuances of drill pay. Work with a mortgage professional who has specific experience with VA loans for Guard and Reserve members. Navigating the specifics of a Guard or Reserve VA loan requires expertise. A mortgage strategist experienced with military income can help assemble your documentation and present your unique financial profile effectively to lenders.
Understanding how your unique service translates into homeownership is the first step. If you're ready to see what's possible, our mortgage strategists are here to help you navigate the process. Take the next step and apply for a mortgage today to leverage your military benefits.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.









