

Austin Mortgage Insurance: FHA MIP vs. Conventional PMI
The most significant long-term cost difference between an FHA and a conventional loan is mortgage insurance. While both protect the lender if you default, they function very differently. Understanding this is the first step to figuring out which loan is cheaper for your Austin home purchase.
Let's use a realistic example: buying a $450,000 home in the Austin area.
FHA Mortgage Insurance Premium (MIP): A Two-Part Cost
FHA loans require you to pay a Mortgage Insurance Premium (MIP) regardless of your down payment size. This is a non-negotiable part of the loan program and comes in two forms:
- Upfront Mortgage Insurance Premium (UFMIP): This is a one-time fee of 1.75% of the loan amount. For our $450,000 home with a 3.5% down payment ($15,750), the base loan amount is $434,250. The UFMIP would be $7,600 ($434,250 x 1.75%), which is typically rolled into your total loan balance. Your new loan amount becomes $441,850.
- Annual MIP: This is a recurring fee, paid monthly as part of your mortgage payment. For most 30-year FHA loans with a down payment under 5%, the annual rate is 0.55% of the average loan balance for the year. (The data, information, or policy mentioned here may vary over time.) On your initial $441,850 loan, this adds approximately $202 per month to your payment.
Conventional Private Mortgage Insurance (PMI): A Temporary Expense
Conventional loans require Private Mortgage Insurance (PMI) only when you put down less than 20%. Unlike FHA MIP, PMI rates are not standardized; they vary based on your credit score, loan-to-value (LTV) ratio, and debt-to-income ratio.
A borrower with a good credit score (e.g., 740+) might pay between 0.5% and 1.0% of the loan amount annually. (The data, information, or policy mentioned here may vary over time.) Using our $450,000 home example with a 5% down payment ($22,500), the loan amount is $427,500. Assuming a PMI rate of 0.6%, the annual cost would be $2,565, or about $214 per month.
The critical difference: Conventional PMI can be canceled. Once your loan balance reaches 78% of the original home value, your lender is required to automatically terminate PMI. You can also request its removal once you reach 80% LTV, which can happen faster in an appreciating market like Round Rock.
Can You Remove FHA Mortgage Insurance?
This is a common and costly point of confusion for many homebuyers. The rules for removing FHA MIP changed in 2013, and for most borrowers today, the answer is no, not without refinancing.
- If you make a down payment of less than 10%: Your FHA MIP will last for the entire life of the loan. It never goes away. The only way to eliminate it is to sell the home or refinance into a different loan type, typically a conventional loan.
- If you make a down payment of 10% or more: Your FHA MIP will last for 11 years.
This is the FHA loan's biggest long-term drawback. That $202 monthly MIP payment in our example continues for 30 years, costing you over $72,000 in total unless you take action to refinance.
Building Home Equity Faster in Round Rock
Home equity is your financial stake in your property, and building it quickly is a key part of wealth creation. The loan you choose directly impacts the speed at which you build equity.
Let's compare our two loans on the $450,000 Round Rock home, assuming a 6.5% interest rate for both for simplicity.
FHA Loan After 5 Years:
- Initial Loan with UFMIP: $441,850
- Monthly Payment (P+I+MIP): ~$2,793 + $202 = $2,995
- Remaining Loan Balance: ~$418,500
- Principal Paid: ~$23,350
Conventional Loan After 5 Years (with 5% down):
- Initial Loan: $427,500
- Monthly Payment (P+I+PMI): ~$2,702 + $214 = $2,916
- Remaining Loan Balance: ~$404,700
- Principal Paid: ~$22,800
At first glance, the principal paid looks similar. However, the FHA borrower started with a higher loan balance due to the UFMIP being financed. The real advantage for the conventional borrower comes when PMI is removed. If home values in Round Rock appreciate and the borrower pays down the mortgage, they could potentially remove their $214 PMI payment after a few years. That extra money could then be applied directly to the principal, accelerating equity growth significantly while the FHA borrower is still stuck paying MIP.
Total Interest Paid: The Decade-Long View
Let's zoom out and look at the total cost over 10 years. This reveals the true financial impact of lifelong MIP for the $450,000 Austin home purchase scenario.
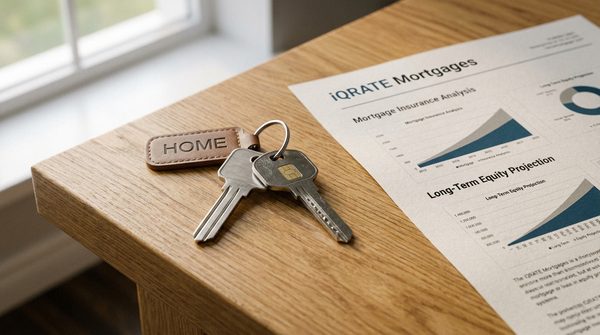
For the FHA loan with 3.5% down, the total mortgage insurance paid would be approximately $24,240, and the total out-of-pocket cost for principal, interest, and mortgage insurance would be around $359,400.
For the conventional loan with 5% down, assuming PMI is removed after six years, the total mortgage insurance paid would be about $15,408. The total out-of-pocket cost for principal, interest, and mortgage insurance would be around $339,648.
Over a decade, the conventional loan borrower in this scenario saves nearly $20,000. The savings come almost entirely from the ability to cancel PMI, whereas the FHA borrower continues to pay MIP every single month.
Are Seller Contributions Treated Differently?
Yes, and this can be a strategic factor in your offer. Seller contributions, or 'concessions', are when the seller agrees to pay some of your closing costs.
- FHA Loans: Allow the seller to contribute up to 6% of the home's sales price toward your closing costs. (The data, information, or policy mentioned here may vary over time.) For our $450,000 home, this is a maximum of $27,000.
- Conventional Loans: The limit depends on your down payment.
- Less than 10% down: 3% limit ($13,500 on our example home).
- 10% to 25% down: 6% limit.
- More than 25% down: 9% limit. (The data, information, or policy mentioned here may vary over time.)
For a first-time buyer in Pflugerville using a low down payment, FHA's higher 6% concession limit seems like an advantage. It allows you to ask for more help with closing costs. However, in a competitive market, a large concession request can make your offer less attractive than a conventional offer asking for less.
If My Credit Score Improves, Which Loan Offers Better Options?
Life happens. You might start with a lower credit score and need an FHA loan to qualify, but what happens when your score improves a few years later? This is where the refinance path becomes critical.
- FHA to Conventional Refinance: This is the most powerful move an FHA borrower can make. If your credit score has increased and you've built up enough equity (usually 20% to avoid PMI altogether), refinancing into a conventional loan is the primary way to permanently eliminate FHA MIP. This single action can save you hundreds per month and tens of thousands over the life of the loan.
- Conventional to Conventional Refinance: If you already have a conventional loan, you can refinance to get a lower interest rate or change your loan term. You aren't burdened with the need to refinance just to get rid of mortgage insurance.
Essentially, the conventional loan provides flexibility from the start, while the FHA loan often requires a future refinance to achieve its best long-term cost structure.
Which Loan Makes My Offer More Competitive to Austin Sellers?
In a fast-paced market like Austin, perception matters. Sellers and their agents often view conventional loan offers as stronger and more reliable than FHA offers.
Here’s why:
- Stricter Underwriting: Conventional loans typically have stricter credit and income requirements, giving the seller more confidence that the financing will not fall through.
- Appraisal Standards: FHA appraisals include a 'Minimum Property Standards' inspection. The appraiser must check for specific health and safety issues (like peeling paint in older homes or a faulty staircase). If issues are found, they must be repaired before the loan can close. This can cause delays or kill a deal, a risk many Austin sellers want to avoid.
- Market Competition: When a seller receives multiple offers, one with conventional financing and another with FHA financing, they often lean toward the conventional offer, seeing it as the path of least resistance to a smooth closing.
While an FHA loan is a fantastic tool for accessing homeownership, a conventional loan can give you a clear competitive edge when making an offer in Austin or Round Rock. Choosing the right loan is more than just securing a low interest rate; it's about a long-term financial strategy. If you're weighing your options in the Austin area, a detailed loan comparison can reveal the best path for your future.
Understanding these differences is key to making a smart financial decision for your Austin home. If you're ready to see which loan option best fits your specific situation, take the next step and apply now to get a personalized comparison.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
What is private mortgage insurance? - CFPB









