
What Is a Certified Property and How Does It Benefit Sellers?
A certified property is a listing that has undergone a preliminary underwriting review to confirm its eligibility for specific types of financing, primarily FHA and Conventional loans, before it even goes on the market. Think of it as a pre-approval for the house itself, not just the buyer. For a real estate agent, this is a powerful tool to address a seller's number one fear: a deal collapsing weeks into escrow because of an unforeseen property issue. (The data, information, or policy mentioned here may vary over time.)
The benefits for your seller are immediate and substantial:
- Reduced Fall-Through Risk: The most common reason deals fail after an offer is accepted is financing. By identifying and resolving potential FHA or conventional lending hurdles upfront, you remove a massive variable from the equation. This prevents the seller from having to put their home back on the market from a position of weakness.
- Stronger Negotiating Position: A certified property gives the seller confidence. They know their home qualifies for the most common loan types, which means they can hold firm on price and terms when negotiating with buyers. There's less fear that the buyer's loan will be denied due to a property condition.
- Faster Closing Times: The property-related underwriting work is already done. This can shave significant time off the typical escrow period, as the lender's underwriter has fewer items to review regarding the collateral. For a seller in Las Vegas needing to move quickly, this is a game-changer.
- Increased Buyer Confidence: Buyers, especially first-timers using FHA loans, are often nervous about the home inspection and appraisal. A 'Financing-Certified' seal of approval gives them peace of mind that the property is sound and meets stringent government-backed lending standards.
Expanding Your Buyer Pool in Las Vegas with FHA Pre-Approval
In markets like Las Vegas and Henderson, FHA loans are a critical financing tool, particularly for first-time homebuyers and those with less-than-perfect credit or a smaller down payment. However, FHA loans come with strict Minimum Property Requirements (MPRs) set by the Department of Housing and Urban Development (HUD). Many homes, especially older ones, may have minor issues that make them ineligible without the seller even knowing.
By pre-vetting a property for FHA approval, you instantly make it accessible to a much larger segment of the market. An agent for an FHA-pre-approved buyer can submit an offer with confidence, knowing the property won't be flagged for common FHA deal-killers. This proactive approach eliminates a major barrier and signals to the entire buyer community that your listing is ready for a smooth transaction. You are no longer just marketing a house; you are marketing a solution and a high-certainty closing.
Documentation Needed for Listing Certification
Getting a listing financially certified is a straightforward process that relies on gathering key property documents. Having these ready will expedite the review and ensure a smooth process. While every property is unique, the core documentation needed typically includes:
- Property Disclosures: The seller's completed Real Property Disclosure form.
- HOA Documents: If the property is in a Homeowners Association, the full HOA packet is crucial. This includes the budget, bylaws, and any pending litigation. This is especially important for FHA condo approvals, as the entire project must be HUD-approved.
- Preliminary Title Report: This shows any liens or encumbrances on the property.
- Recent Repair Invoices: Documentation for any major work done, such as a new roof, HVAC system, or electrical panel, proves the work was completed professionally.
- Existing Appraisal (If Available): If the seller had a recent appraisal for a refinance, it can provide valuable information, though the buyer's lender will still order a new one.
Marketing Your Certified Listing in Henderson
Once your listing is certified, it becomes a unique selling proposition that you must leverage in your marketing. This isn't just a background detail; it's a headline feature that differentiates your listing from the competition in a crowded Henderson market.
Highlight Certification in MLS Remarks
Your MLS description is the first thing other agents see. Use the agent-only remarks to state the property's status clearly. For example:
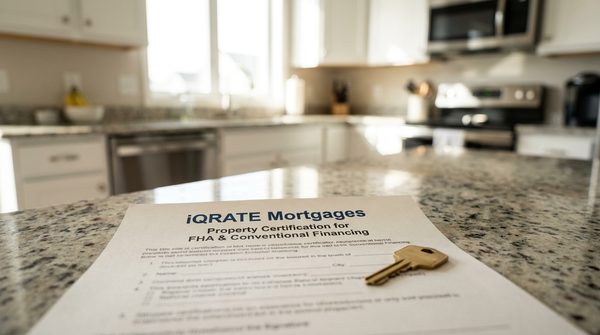
'Property is Pre-Certified for FHA & Conventional Financing! All property-related underwriting conditions have been reviewed. Bring your buyers with confidence. See attached certification documents.'
Create Custom Marketing Collateral
Design a small, professional flyer or a section on your property brochure that explains what 'Financing-Certified' means for a potential buyer. Use phrases like 'FHA Ready' and 'Move-In Ready for FHA Buyers'. On social media, create posts that highlight this benefit, targeting keywords that first-time homebuyers might use.
Leverage the Certification in Open Houses
During an open house, don't just wait for people to ask. Proactively explain the benefit. You can say, 'One of the things the seller did to make this an easy purchase is they had the property pre-certified for FHA financing. That means we've already cleared the major hurdles with the lender, so you can make an offer with a very high degree of confidence that the loan will be approved.'
Common Property Issues That Kill FHA and VA Loans
FHA and VA loans are backed by the government, which means the property used as collateral must meet certain safety, security, and soundness standards. Underwriters are trained to look for specific red flags that can halt a loan in its tracks. Certifying a property means checking for these issues ahead of time. (The data, information, or policy mentioned here may vary over time.)
Here are some of the most common property-related deal killers:
- Peeling or Chipping Paint: In homes built before 1978, this is a major red flag for potential lead-based paint hazards. It must be scraped and repainted before closing.
- Roofing Issues: An FHA appraiser must certify that the roof has at least two years of remaining economic life. Any active leaks or significant damage must be repaired.
- Inadequate Safety Features: This includes missing handrails on stairs (both interior and exterior), non-functional windows that are intended for egress, or lack of smoke detectors.
- Outdated Electrical and Plumbing: Exposed wiring, evidence of overloaded circuits, or major plumbing leaks will be flagged by an appraiser.
- Foundation or Structural Problems: Any signs of significant cracks in the foundation, water damage in the basement or crawlspace, or structural instability are immediate roadblocks.
- Ineligible Condo Projects: For a condominium, the entire project must be HUD-approved. If the HOA has too many investor-owned units, pending litigation, or insufficient reserve funds, the property will be ineligible for FHA financing.
De-Risking Contingent Offers for Your Seller
A common headache for sellers is an offer that is contingent on the buyer selling their own home. This adds a layer of uncertainty and a longer timeline. However, if your listing is financially certified, it significantly de-risks this scenario.
The certification removes one of the two major unknowns. You and your seller already know your property is financeable. The only remaining variable is whether the buyer's own home sells on time. This puts your seller in a much stronger position. They can evaluate the contingent offer based solely on the merits of the buyer's qualifications and the likelihood of their home selling, without worrying about a last-minute surprise from their own property's condition.
A Unique Value Proposition for Your Listing Presentation
In a competitive market, every agent promises to sell a home for top dollar. The 'Certified Property' program allows you to show how you will do it differently and with less risk.
Showcasing Your Proactive Strategy
Present this as part of your strategic marketing plan. Explain to the seller: 'My approach is to remove potential problems before they happen. We are going to get your property pre-approved for financing, which will attract more buyers, make our offers stronger, and protect you from the stress of a deal falling through.'
Quantifying the Value
Connect the certification to tangible results. You can explain that properties with this designation often have fewer days on market because they appeal to a wider audience. More importantly, they have a much lower chance of going 'Back on Market' after a contract fails, which almost always results in a lower final sale price.
Addressing Seller Fears Head-On
Look the seller in the eye and say, 'Your biggest concern is likely the uncertainty of the escrow process and the fear that a buyer's loan will be denied. This program is my direct answer to that fear. We take control of the process from day one, ensuring your home is presented as the most reliable and attractive option on the market.' This demonstrates that you understand their concerns and have a concrete, innovative solution to protect their interests. As a real estate agent, your value lies in your ability to provide certainty in an uncertain process. To learn more about how the Certified Property program can help you win more listings and protect your sellers, reach out to a mortgage strategist who can pre-underwrite your property's potential.
A certified property provides peace of mind for everyone involved. If you're ready to begin your homebuying journey with that same level of confidence, start by seeing what you qualify for. Apply now and take the first step toward a smoother transaction.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.