What happened on this Miami DSCR loan?
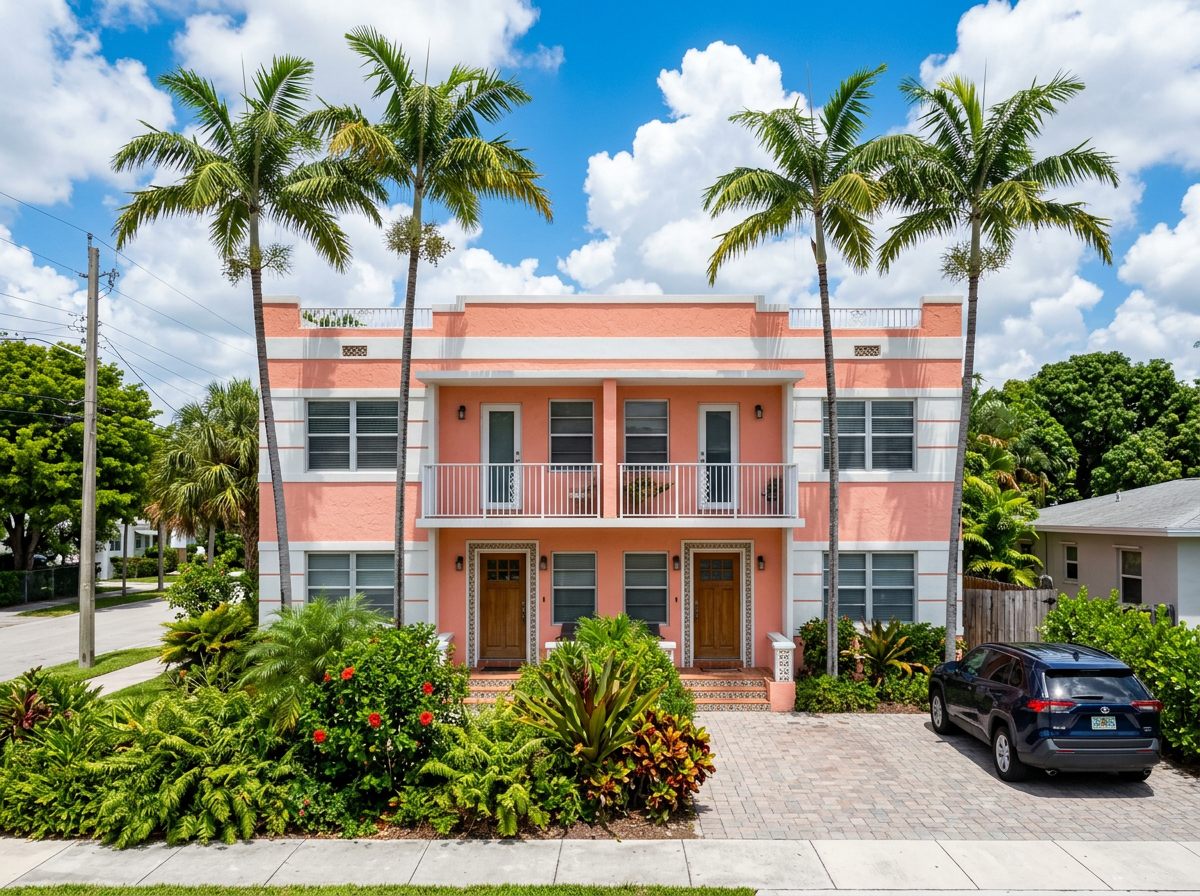
My client had bought fourplexes before. For her next one, an $800,000 fourplex in Miami, she planned to put 35% down using money from her beauty salon business. She financed the rest with a $520,000 Miami DSCR loan, which funded in summer 2024.
A DSCR loan qualifies the property, not your tax returns. The lender divides the monthly rent it counts by the full monthly property payment. On a fourplex, that rent is the total from all four units. For condo buyers, our Miami condo DSCR loan page covers the extra project rules.
- Purchase price: $800,000, a fourplex
- Down payment: $280,000 (35%), from business funds
- Loan: $520,000 DSCR loan (65%)
- Math: $800,000 x 35% = $280,000 down; $800,000 - $280,000 = $520,000 loan
- Funded: summer 2024
Why did the lender question the salon funds?
The lender could see the money on the business bank statements. The balance was never the problem. Its concern was what would happen to the salons after she took $280,000 out. If a business needs that cash to operate, pulling it out for a down payment can hurt the business, and lenders are careful about funds that may not really be free to use.
- What the lender could already see: the money sitting in the business account. Another statement would only show the balance again.
- What the lender needed to know: could the salons keep paying their expenses after the withdrawal?
This comes up often with self-employed buyers. We cover the general rules in our guide to using business funds for a Florida loan.

How did a CPA letter solve it?
What the underwriter needed to understand was how much cash the salons needed to keep operating. My client ran profitable salons, and their operating expenses ran well below revenue.
I worked with her CPA on a letter about the planned withdrawal. It did more than confirm she owned a profitable business. It explained why the salons could keep paying their expenses after she used business funds for the purchase. That gave the underwriter what was needed to accept the funds.
- Generic letter: confirms the business exists and is profitable. It does not answer the lender's real question.
- Useful letter: answers the exact question the underwriter asked, here whether the business could operate after the withdrawal.
Does a DSCR loan check your personal income?
Not to qualify. The lender qualified this loan on the property's rent, so her personal debt-to-income ratio did not decide whether she qualified. That is one reason investors with business income use DSCR loans instead of bank statement loans, which do look at your income.
The lender still checks where the down payment comes from, and your credit still sets the price. Both mattered on this file.
How did a car purchase affect the pricing?
My client had just financed a car. That added a monthly debt and lowered her credit score. Because rent qualified the loan, the car payment never entered a personal debt-to-income test. The lower score still affected what she would pay to borrow.
- New car loan: added a monthly debt.
- Score dropped: rent still qualified the loan, but pricing got worse.
- Cards paid down: she lowered her card balances.
- Rapid rescore: my team requested one so the new balances showed on her mortgage credit report.
- Lower rate: her score rose before pricing, and she qualified for a lower rate.
What is a rapid rescore?
A rapid rescore is a request, made through the lender's credit vendor, to update a mortgage credit report after you correct or pay down an account. It does not erase accurate history. It makes sure the report reflects balances you have already paid. The CFPB explains what a credit report contains, and you can check yours for free at AnnualCreditReport.com.
What would have stopped this loan?
If the CPA letter had only confirmed the business was profitable, the underwriter's question would still have been open, and the funds could have been rejected. If she had not paid down her cards before pricing, she would have closed at a higher rate. Neither problem was about the property. Both were about paperwork and timing, which is where most investor files slip. See how to stop last-minute mortgage fallout for more examples.
What I recommend before applying for a Miami DSCR loan
- Know which account the down payment comes from: if it sits in a business account, ask early what the lender needs to see about the withdrawal.
- Give your CPA the lender's actual question: here it was whether the salons could pay their expenses after the withdrawal. A specific question gets a letter the underwriter can use.
- Check your credit after any big purchase: a new car loan will not break a DSCR qualification, but it can raise your price.
- Keep the business entity clean: make sure your business records with the Florida Division of Corporations match the bank statements you provide.
Buying elsewhere in Florida? See our Tampa DSCR loans, Florida mortgage broker page or Miami jumbo loans. When you are ready, call (702) 766-3744 or apply now.
Figures come from the purchase contract and the closing file. This is one closed loan, not a promise of any outcome, rate or approval. Investor loans are for business-purpose use only. iQRATE Mortgages, NMLS 1862492. Equal Housing Opportunity.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
Consumer Financial Protection Bureau: What is a credit report?
AnnualCreditReport.com: Free credit reports
Florida Department of State: Division of Corporations (Sunbiz)