

How Much Equity Do I Need to Remove Mortgage Insurance in Dallas?
The most critical requirement for refinancing out of a Federal Housing Administration (FHA) loan is having sufficient home equity. Lenders require you to have a loan-to-value (LTV) ratio of 80% or less to qualify for a conventional loan without private mortgage insurance (PMI). This means your remaining mortgage balance can be no more than 80% of your home's current appraised value. In simpler terms, you need at least 20% equity in your home.
Equity is the portion of your home you truly own. You can calculate it with a simple formula:
Home's Current Market Value - Remaining Mortgage Balance = Your Equity
For homeowners in the competitive Dallas market, rapidly appreciating home values can help build this equity faster than just making monthly payments.
Equity Calculation Example
Let's say you bought a home in Dallas a few years ago and its value has since increased.
- Current Appraised Value: $450,000
- Remaining Mortgage Balance: $350,000
To determine your LTV, you would divide the loan balance by the home's value:
$350,000 / $450,000 = 0.777 or 77.7% LTV
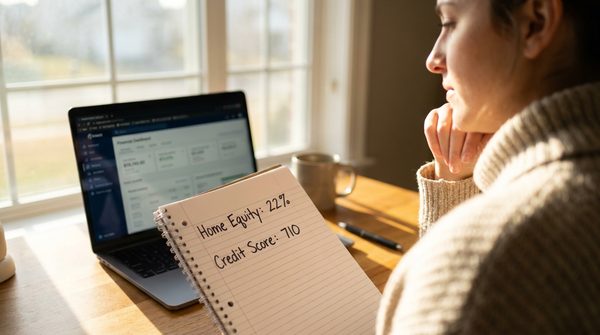
In this scenario, your LTV is below the 80% threshold, meaning you have over 22% equity. You would meet the equity requirement to refinance into a conventional loan and eliminate your FHA mortgage insurance premium (MIP).
What Credit Score Is Required to Refinance My FHA Loan?
While FHA loans are known for their flexible credit requirements, conventional loans have stricter standards. To refinance from an FHA loan to a conventional one, you will generally need a minimum credit score of 620. (The data, information, or policy mentioned here may vary over time.)
However, it's important to understand that 620 is just the baseline. Lenders reserve the best interest rates and terms for borrowers with higher credit scores.
- Good Credit (680-739): You will likely qualify for competitive interest rates.
- Excellent Credit (740+): You will be offered the most favorable interest rates available, potentially saving you tens of thousands of dollars over the life of the new loan.
If your score is below 620, you should focus on improving it by making on-time payments, reducing credit card balances, and checking your credit report for errors before applying for a refinance.
Will My Interest Rate Go Up When I Refinance to a Conventional Loan?
This is a common concern, and the answer depends entirely on the market. Your new interest rate will be based on the prevailing rates at the time you refinance, not the rate on your original FHA loan. It could be higher, lower, or about the same.
However, focusing solely on the interest rate can be misleading. The primary goal of this refinance is to eliminate the costly FHA MIP, which often saves you more money than a slightly higher interest rate would cost. You need to look at the total monthly payment.
Comparing Payments: Rate vs. MIP Savings
Consider this example for a homeowner in Dallas:
Current FHA Loan:
- Loan Balance: $400,000
- Interest Rate: 5.5%
- Monthly FHA MIP: $280
- Total Principal, Interest, and MIP Payment: ~$2,551
Proposed Conventional Refinance:
- New Loan Balance: $400,000
- New Interest Rate: 6.0%
- Monthly PMI: $0
- Total Principal and Interest Payment: ~$2,398
Even with a 0.5% higher interest rate, the monthly payment on the new conventional loan is $153 lower because you've eliminated the $280 monthly MIP payment. The annual savings would be over $1,800.
What Are the Closing Costs to Refinance Out of My FHA Loan in Dallas?
Refinancing is not free; it involves closing costs, just like your original home purchase. Typically, these costs range from 2% to 5% of the new loan amount. (The data, information, or policy mentioned here may vary over time.) For a homeowner in Dallas refinancing a $400,000 loan, this would mean closing costs between $8,000 and $20,000.
Common closing costs include:
- Appraisal Fee: To determine your home's current market value.
- Lender Origination Fee: A charge for processing and underwriting the new loan.
- Title Search and Insurance: To ensure there are no liens against your property.
- Credit Report Fee: The cost to pull your credit history.
- Recording Fees: Paid to your county to record the new mortgage lien.
- Prepaid Items: Such as property taxes and homeowners insurance for your new escrow account.
You have two primary ways to handle these costs: pay them out of pocket at closing or roll them into the new loan balance. Rolling them in increases your total loan amount and monthly payment slightly but avoids a large upfront expense.
How Long Must I Wait Before I Can Refinance My FHA Loan?
When refinancing from an FHA loan to a conventional loan, lenders have 'seasoning' requirements to see a history of consistent payments. Generally, you must have made at least six to twelve on-time monthly payments on your FHA loan. (The data, information, or policy mentioned here may vary over time.)
Some lenders might impose their own, stricter 'overlays', requiring a full year of payments. However, the most significant timing factor is not the number of payments but the time it takes to build the necessary 20% equity. For most homeowners, building that much equity through payments and market appreciation will take much longer than six months, making the seasoning requirement a minor consideration.
Is It Better to Wait for a Lower Interest Rate to Refinance?
Trying to 'time the market' for the perfect interest rate can be a costly mistake. While waiting, you continue to pay hundreds of dollars each month in FHA MIP that you will never get back. Instead of waiting for a hypothetical future rate, it's more practical to calculate your breakeven point today.
Your breakeven point is the time it takes for the monthly savings from your refinance to cover the closing costs. For instance, if your closing costs were $9,000 and you save $150 per month, your breakeven point is 60 months ($9,000 / $150). If you plan to stay in your home longer than five years, the refinance is financially beneficial.
The wisest strategy is often to refinance as soon as you are eligible and the numbers make sense. You can always refinance again in the future if rates drop significantly.
Can I Refinance if My Home Value in Dallas Has Decreased?
This is a challenging situation that directly impacts your LTV. If your home's value has fallen since you purchased it, refinancing might be difficult or impossible. The entire process hinges on having at least 20% equity, and a lower home value erodes your equity position.
For example, if you have a $380,000 loan balance and your home's appraised value drops from $420,000 to $395,000, your LTV would increase to over 96%. You would not be eligible to refinance into a conventional loan.
If you find yourself in this position, your options are:
- Wait for the Market: Continue making payments and hope the Dallas real estate market recovers, increasing your home's value.
- Pay Down the Principal: Make extra payments toward your principal balance to build equity faster.
What Is the First Step to Start the Refinance Process?
Starting the refinance process is straightforward and begins with assessing your current situation. Follow these clear steps to get started.
- Review Your Finances: The first step is to understand your numbers. Locate your most recent mortgage statement to confirm your exact loan balance. Check your credit score for free through your credit card provider or a credit monitoring service.
- Estimate Your Home's Value: Use online real estate tools to get a preliminary estimate of your home's current market value. This will give you a rough idea of your equity, but remember that the lender will require a formal appraisal for an official valuation.
- Consult a Mortgage Advisor: This is the most crucial step. A qualified mortgage professional can analyze your specific financial situation, confirm your eligibility, and provide a detailed Loan Estimate. This document outlines the interest rate, closing costs, and total monthly payment for the new loan, allowing you to see the precise savings.
- Gather Your Documents: Be prepared to provide standard financial documents to your lender. This typically includes your last two pay stubs, the last two years of W-2s or tax returns, and recent bank statements. Eliminating FHA mortgage insurance can save you hundreds each month. If you're ready to see if a conventional refinance makes sense for your financial goals, a qualified mortgage advisor can provide a personalized analysis with no obligation.
Ready to explore if you can eliminate mortgage insurance and lower your monthly payment? Apply now to receive a personalized analysis of your refinance options.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
What is a loan-to-value ratio and how does it relate to my mortgage costs?









