

Do Lenders Check My Credit Score for a Streamline Refinance in Miami?
The U.S. Department of Veterans Affairs does not mandate a minimum credit score or even require a new credit report for an Interest Rate Reduction Refinance Loan (IRRRL), commonly known as a streamline refinance. This is one of the most significant advantages of the program. The VA's logic is that you were already deemed a worthy borrower when you qualified for your original VA loan. The primary requirement from the VA's perspective is a history of on-time mortgage payments on that existing loan.
However, it's critical to understand the difference between VA guidelines and lender requirements. Most lenders impose their own internal rules, called 'lender overlays'. This means that while the VA doesn't ask for a credit check, nearly every lender will. Lenders in competitive markets like Miami often set a minimum credit score to manage their risk. Typically, you'll find lenders looking for a credit score of at least 620, though some may go lower or require a higher score. (The data, information, or policy mentioned here may vary over time.)
Your payment history is the most crucial factor. A perfect record of on-time payments for the last 12 months on your current VA mortgage will significantly strengthen your application. If you have one late payment (30 days past due) in the last year, you may still qualify with some lenders, but it becomes much more difficult. Two or more late payments will almost certainly result in a denial.
In summary:
- VA Requirement: No credit check is required.
- Lender Reality: Most lenders will pull your credit and have a minimum score requirement, often around 620.
- Most Important Factor: A clean 12-month mortgage payment history on your current VA loan.
Must I Prove My Income Again for This Type of Veteran Loan in Jacksonville?
Similar to the credit check, the VA does not require income verification for a standard IRRRL, provided the new monthly principal and interest payment does not increase by 20% or more. The program is designed to be 'streamlined', reducing the paperwork burden on the veteran. The focus is on lowering your rate or payment, not re-qualifying you from scratch.
This is especially beneficial for veterans in Jacksonville who may have changed jobs, become self-employed, or experienced an income reduction since their original loan. As long as you have a solid mortgage payment history, your current income status may not be a barrier.
There is a key exception to this rule. If your new mortgage payment will be 20% higher than your old one, the lender must fully underwrite the loan, which includes verifying your income and calculating your debt-to-income (DTI) ratio. This situation typically arises when a veteran refinances from an Adjustable-Rate Mortgage (ARM) to a Fixed-Rate Mortgage. While the new fixed rate might be higher than the current ARM rate, it provides long-term stability. In this scenario, the lender needs to ensure you can comfortably afford the new, higher payment.
Example: A Jacksonville veteran has an ARM with a current principal and interest payment of $1,500. They want to refinance into a fixed-rate loan with a new payment of $1,750. This is an increase of $250, or about 16.7%. Since this is less than a 20% increase, income verification would likely not be required by the VA's standards. If the new payment were $1,850 (a 23.3% increase), full income documentation would be mandatory.
Can I Get Cash Out With a Streamline Refinance Loan?
No, you cannot get cash out of your equity with a VA Streamline Refinance (IRRRL). The program's sole purpose is to help veterans improve the terms of their existing mortgage by lowering the interest rate or switching from an ARM to a fixed-rate loan. It is strictly a 'rate-and-term' refinance.
If you need to access your home's equity for things like debt consolidation, home improvements, or other major expenses, you would need to use a VA Cash-Out Refinance. This is a different loan product that involves a more detailed underwriting process, including a full credit check, income verification, and a new home appraisal.
There is one minor exception with the IRRRL. You can finance the costs of specific energy efficiency improvements into the loan, up to $6,000. These must be qualified Energy Efficiency Mortgages (EEMs) improvements, such as new insulation, solar panels, or storm windows. This amount is added to the loan balance but is not given to you as cash.
What Is the Net Tangible Benefit Rule for These Veteran Loans?
The Net Tangible Benefit (NTB) rule is a crucial consumer protection requirement for all VA refinances. It ensures that the refinance provides a genuine, measurable benefit to the veteran and isn't just generating fees for the lender. The lender must certify that the IRRRL meets at least one of the specific NTB requirements set by the VA.
Key acceptable benefits include:
- Lowering the Interest Rate: The new loan's interest rate must be lower than the old loan's rate. There are specific thresholds:
- Going from a fixed rate to another fixed rate requires at least a 0.5% reduction (e.g., from 6.0% to 5.5%).
- Going from an ARM to a fixed rate.
- Reducing the Loan Term: Shortening the mortgage term (e.g., from a 30-year to a 15-year) is a valid benefit, even if the payment increases.
- Moving from an ARM to a Fixed-Rate Loan: This is considered a significant benefit because it provides payment stability and eliminates the risk of future rate hikes.
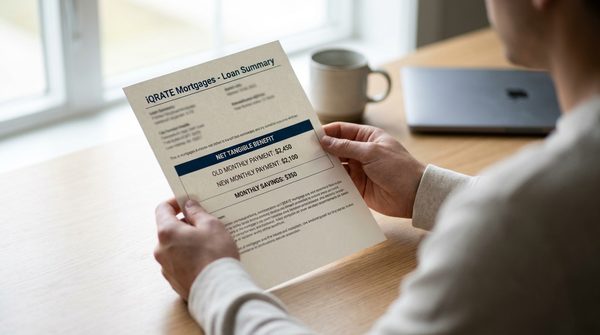
The lender must also demonstrate that you will recoup all closing costs and fees (a process known as 'recoupment') within 36 months. This is calculated by dividing the total closing costs by the amount you save each month with the new, lower payment. This prevents lenders from loading up a loan with high fees that negate the savings.
How Much Are Closing Costs for a Streamline Refinance Loan?
While an IRRRL is streamlined, it is not free. You will still have closing costs, but a major advantage is that all costs, including the VA Funding Fee, can be rolled into the new loan amount. This means you may not need to bring any cash to the closing table.
Typical closing costs can include:
- VA Funding Fee: This is a mandatory fee paid directly to the VA to help fund the loan program. For an IRRRL, it is 0.5% of the loan amount for all veterans, regardless of whether it's their first or subsequent use. Veterans receiving VA disability compensation are exempt from this fee.
- Lender's Origination Fee: Lenders can charge a flat fee of up to 1% of the loan amount to cover their processing and underwriting costs.
- Other Third-Party Fees: These may include title insurance, recording fees, and credit report fees (if the lender requires one).
Lenders are not permitted to charge for an appraisal since one is not typically required. In total, you can expect closing costs to be between 1% and 3% of your loan amount. For a $300,000 loan in Florida, this could range from $3,000 to $9,000, all of which can usually be financed. (The data, information, or policy mentioned here may vary over time.)
Does My Home in Miami Need a New Appraisal for This Process?
No, in nearly all cases, a new appraisal is not required for a VA Streamline Refinance. This is a massive benefit that saves veterans time and money. An appraisal can cost $500 to $800 or more in a market like Miami and add weeks to the closing timeline. (The data, information, or policy mentioned here may vary over time.) By skipping this step, the IRRRL process becomes much faster and less expensive.
The VA waives the appraisal requirement because it is already guaranteeing your original loan. The new loan is simply a modification of that existing obligation. The lender is not taking on significant new risk related to the property's value, especially since no cash is being taken out.
How Quickly Can a Streamline Refinance Loan Close in Jacksonville?
The absence of an appraisal and the reduced documentation requirements make the IRRRL process exceptionally fast compared to other types of mortgages. While a standard refinance or purchase loan can take 30 to 45 days or more to close, a VA Streamline Refinance can often be completed in as little as two to four weeks.
The timeline for a veteran in Jacksonville depends on a few factors:
- Lender's Efficiency: How quickly the lender's team can process your file.
- Your Responsiveness: How quickly you can provide the necessary documents, such as your existing mortgage statement, homeowners insurance, and signed disclosures.
- Title Company's Workload: The time it takes for the title company to prepare the final documents for closing.
Because the underwriting is so simplified, the bulk of the time is spent on initial processing and final document preparation. For veterans looking to quickly lock in a lower rate, the IRRRL's speed is a major advantage.
Can I Add My New Spouse to the Streamline Refinance Loan?
Yes, you can add a spouse to an IRRRL, but the rules depend on whether your spouse is also an eligible veteran.
- Veteran Spouse: If your spouse is also a veteran with their own VA loan eligibility, they can be easily added to the new loan. The process remains streamlined.
- Non-Veteran Spouse: You can add a non-veteran spouse, but it adds a layer of complexity. The VA requires that the original veteran who qualified for the loan remains on the new loan. You cannot remove the veteran and leave only the non-veteran spouse. The lender may also require additional underwriting, potentially including a credit check and income verification for the spouse, to ensure the loan meets their internal guidelines. This is a lender-specific requirement, not a VA rule, but it is common practice. (The data, information, or policy mentioned here may vary over time.)
The primary borrower must always be the veteran with the entitlement. Adding a spouse can be a good way to manage household finances, but it's important to discuss the implications with your mortgage advisor to ensure a smooth process. The VA Streamline Refinance program offers a powerful way for veterans to lower their monthly payments with minimal hassle. To see if you qualify and to understand the specific lender requirements, consult with a mortgage strategist who specializes in VA loans and can navigate the process for you.
The VA Streamline Refinance offers a powerful way for veterans to lower their monthly payments with minimal hassle. If you're ready to see how a lower interest rate could benefit your budget, you can Apply now to start the conversation with a VA loan specialist.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
U.S. Department of Veterans Affairs - Interest Rate Reduction Refinance Loan
Consumer Financial Protection Bureau - What is a VA streamline refinance loan?









