
The Move-Up Buyer's Dilemma: Why Florida Sellers Hesitate
In competitive Florida markets, many homeowners feel trapped. You want to sell your current home to buy a new one that better fits your lifestyle, but a paralyzing question stops you: 'Where will I go, and can I afford it?' This isn't just a minor worry; it's a major roadblock that shrinks housing inventory. Homeowners in bustling areas like Miami see properties selling quickly, but they hesitate to list their own because of the financial uncertainty that follows.
The fear is logical. You don't want to sell your home only to find yourself unable to secure a mortgage for the next one, or worse, discover the monthly payments are far higher than you anticipated. This hesitation creates a stalemate. You stay put, your dream home remains a dream, and a potential buyer misses out on your property. The solution isn't to hope for the best; it's to replace fear with a concrete, data-driven plan.
What is a Move-Up Certainty Certification?
A Move-Up Certainty Certification is a comprehensive pre-listing financial analysis that goes far beyond a typical mortgage pre-approval. It is a fully underwritten plan for your next home purchase, created before your current home is on the market. Think of it as a financial bridge connecting the sale of your old home to the purchase of your new one. It provides a clear, verified roadmap, transforming anxiety into actionable confidence.
This certification analyzes your complete financial picture in the context of your move-up goals. It includes:
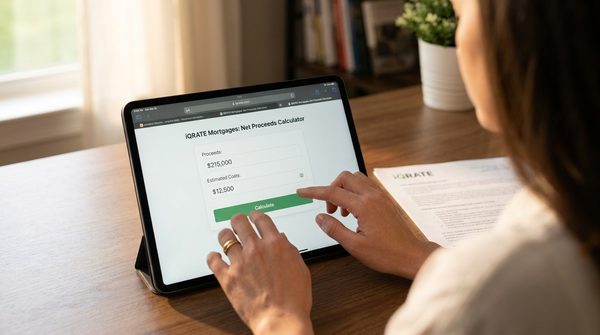
- Detailed Home Equity Analysis: An accurate calculation of the proceeds you can expect after your mortgage is paid off and all selling costs are covered.
- Verified Income and Asset Review: A full underwriting of your income, assets, and credit, just as would be done for a final mortgage application.
- New Mortgage Qualification: A confirmed loan amount, interest rate, and monthly payment for your next home, based on your projected down payment from the sale.
- Total Buying Power Calculation: A precise number that tells you exactly how much home you can confidently afford.
Beyond a Standard Pre-Approval
It's crucial to understand that a Move-Up Certainty Certification is not the same as a standard pre-approval letter. A pre-approval is a preliminary estimate of your borrowing power, often based on self-reported information. A certification is a commitment.
Standard Pre-Approval:
- Often based on a light review of credit and stated income.
- Provides a general idea of affordability.
- The loan is still subject to full underwriting and appraisal.
- Does not factor in the specific net proceeds from your home sale.
Move-Up Certainty Certification:
- Involves a full underwriting process with verified documents.
- Provides a concrete, reliable loan commitment.
- Calculates your exact buying power using projected net proceeds from your sale.
- Gives your future offer the strength of a cash buyer, as the financing is already secured.
How to Create Your Move-Up Plan in Naples and Miami
Building your certified move-up plan is a structured process designed to provide clarity and security. Whether you're navigating the fast-paced Miami market or the high-value real estate landscape of Naples, these steps ensure you're prepared to make a confident and competitive move.
- Initial Strategy Session: The first step is a detailed consultation to define your goals. What are you looking for in your next home? What is your ideal timeline and budget? This meeting establishes the foundation for your entire plan.
- Current Home Equity Analysis: We'll work with you to establish a realistic selling price for your current home. From there, we deduct your remaining mortgage balance, estimated agent commissions, closing costs, and taxes to arrive at a conservative 'net proceeds' figure. This number is the key to unlocking your down payment for the next home.
- Complete Financial Documentation Review: You will provide the same documents required for a final mortgage application: tax returns, pay stubs, bank statements, and other asset information. Our team performs a full underwriting review to verify every detail, leaving no room for last-minute surprises.
- Structuring Your New Mortgage: Using your calculated net proceeds as the down payment, we structure your next mortgage. We confirm your loan amount, program, interest rate, and projected monthly payment (including principal, interest, taxes, and insurance). You see the complete financial picture of your new home before you even start looking.
- Issuing Your 'Certainty' Commitment: Once the underwriting is complete, you receive a fully vetted loan commitment. This isn't a guess; it's a reliable financial instrument. You can now shop for your next home with the confidence of a cash buyer, knowing your financing is already in place and ready to go.
Example Scenario: A Naples Family's Move-Up Journey
Let's consider a family living in a townhome in Naples, which they believe is worth approximately $750,000. They have an outstanding mortgage balance of $300,000 and want to move up to a single-family home priced around $1,100,000.
- Estimated Sale Price: $750,000
- Remaining Mortgage: -$300,000
- Estimated Selling Costs (6% commission + 2% closing costs): -$60,000 (The data, information, or policy mentioned here may vary over time.)
- Projected Net Proceeds: $390,000
With a Move-Up Certainty Certification, this family goes through the underwriting process before listing their townhome. They are approved for a new mortgage based on using that $390,000 as a down payment on a $1,100,000 home. Their new loan amount would be $710,000. They receive a commitment letter confirming their rate and payment. Now, they can confidently list their townhome and make a non-contingent offer on their dream home, a powerful position in the competitive Naples market.
The Benefits of a Certified Move-Up Plan
Adopting this strategy provides tangible advantages that transform the entire experience of selling and buying a home.
- Removes Financial Uncertainty: The single biggest benefit is confidence. You know exactly how much you can afford, what your new payment will be, and that your financing is secure.
- Creates a Competitive Offer: In a multiple-offer situation, an offer backed by a fully underwritten loan commitment is significantly stronger than one with a standard pre-approval. Sellers see it as less risky and nearly as good as cash.
- Unlocks 'Hidden' Inventory: By giving hesitant sellers a clear path forward, this strategy encourages them to list their homes. It empowers homeowners who were previously on the fence to enter the market, increasing inventory for everyone.
- Reduces Stress and Timelines: The majority of the mortgage work is done upfront. This eliminates the frantic, stressful rush to secure financing after your offer is accepted, leading to a smoother and faster closing process.
Navigating Common Move-Up Challenges in Florida
Even with a solid plan, move-up buyers face unique challenges, especially in dynamic markets.
Timing the Sale and Purchase
The classic 'chicken-and-egg' problem. Do you sell first or buy first? A certified plan gives you options. You can confidently make offers with a flexible closing date or negotiate a 'rent-back' agreement, allowing you to stay in your current home for a short period after closing. This provides the time needed to close on your new home without being displaced.
Capital Gains Tax Considerations
When you sell your primary residence, you can exclude up to $250,000 of profit from capital gains tax ($500,000 for a married couple filing jointly), provided you've lived in the home for at least two of the last five years. Understanding your potential tax liability is a key part of the financial analysis, ensuring there are no surprises after the sale.
Handling Bridge Loans and Recasting
In some situations, you might find the perfect home before you've sold your current one. A bridge loan can provide short-term funds to 'bridge the gap'. Another powerful but lesser-known tool is 'mortgage recasting'. This allows you to make a large lump-sum payment on your new mortgage after your old home sells, and the lender will then re-amortize your loan, lowering your monthly payments without the cost of refinancing. This can be an excellent strategy if you want to act fast on a new home.
Don't let financial uncertainty keep you from your dream home. A Move-Up Certainty Certification provides the clear, data-driven plan you need to move forward with confidence. Take the first step and Apply now to discover your true buying power.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.