

How a Mortgage Partner Halves New Agent Onboarding Time
For most real estate team leaders, you are the business. You are the lead generator, the top producer, the recruiter, and unfortunately, the bottleneck. Every time a new agent joins, your time is immediately consumed by teaching them the basics of financing, how to read a loan estimate, and what makes a strong offer. This repetitive, low-leverage work prevents you from focusing on dollar-producing activities.
A strategic mortgage partner with a Lender Integration Blueprint removes you as the single point of failure. Instead of you personally training every new hire, the lending team takes over the entire financial onboarding process.
The Onboarding Shift
- Structured Training Modules: Your lender provides a pre-built curriculum covering loan products, the mortgage process from application to funding, and how to position financing to clients. This can be a mix of live Zoom sessions, a library of on-demand videos, and written guides.
- Dedicated Q&A Support: New agents get a direct line to a specific loan officer or processor who understands your team's workflow. They can ask fundamental questions without interrupting your day.
- System Integration: Training includes hands-on tutorials for the shared technology stack, such as the deal tracking portal and communication tools. This ensures they adopt the correct processes from day one.
Consider an agent joining your team in Irvine. A typical onboarding might require 30-40 hours of your direct supervision over their first three months just to get them comfortable with loan-related conversations. With an integrated lender, over half of that time is offloaded. The lender handles the mortgage systems and product training, freeing up 15-20 of your hours per new agent to recruit the next one.
Core Systems a Lender Should Provide for Team Growth
A true partnership goes beyond returning calls and closing on time. A lender positioned for team growth provides an operational infrastructure—a mortgage operating system—that you can plug your team into. This system must be built on a foundation of transparent, accessible technology.
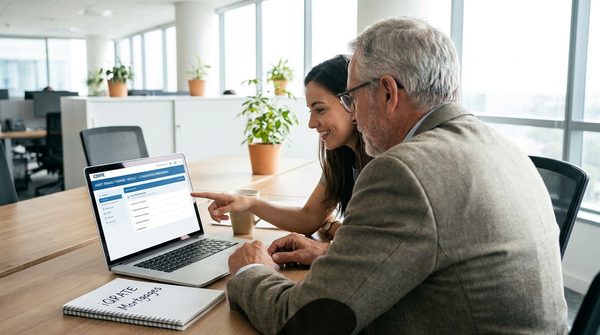
Key systems include:
- Centralized Deal Tracking Portal: This is non-negotiable. A single dashboard where you and every agent can see the real-time status of every single deal. It should track key milestones: application received, appraisal ordered, loan approved, docs out, funded. (The data, information, or policy mentioned here may vary over time.) This eliminates the need for constant 'what's the status?' calls and texts.
- On-Demand Training and Resource Library: A digital hub with training videos, underwriting guidelines for different loan types (FHA, VA, Conventional), marketing collateral, and calculators. When an agent in San Diego has a question about a self-employed borrower, they can find the answer here first.
- Integrated Communication Tools: Automated text and email updates for clients and agents at key milestones. This system should be co-brandable to maintain your team's identity while ensuring consistent, professional communication.
- CRM Integration Capability: The lender's technology should be able to 'talk' to your CRM. Whether through a direct API or a service like Zapier, this connection automates data entry and ensures client information is consistent across both platforms.
Why Standard Pre-Approvals Fail a Scaling Real Estate Team
As you scale, your team's reputation becomes your most valuable asset. A standard pre-approval from a random big-box lender is a direct threat to that reputation. These letters are often generated by automated systems after a superficial credit check and based on unverified information provided by the borrower. They are notoriously unreliable.
When a pre-approval falls apart, your junior agent loses confidence, your client is devastated, and your team's name is attached to a failed transaction. In competitive markets like San Diego, a weak pre-approval letter can get your client's offer rejected outright.
A Lender Integration Blueprint replaces this weak link with a Verified Approval. This is a fully underwritten approval where the lender's underwriting team has reviewed and verified the borrower's:
- Income: Pay stubs, W-2s, and tax returns are analyzed.
- Assets: Bank statements are sourced and reviewed for down payment and reserves.
- Credit: A full credit report is pulled and reviewed by a human, not just a computer.
A Verified Approval is as good as a cash offer because the only remaining conditions are typically the property appraisal and title report. (The data, information, or policy mentioned here may vary over time.) It gives your agents the confidence to write non-contingent offers and win more deals.
How a Lender's Centralized Deal Tracking Prevents Commission Loss
Chaos is the enemy of profit. Without a centralized system, information lives in individual email inboxes, text messages, and spreadsheets. An agent goes on vacation, and nobody knows the status of their closing. A processor asks for a document, but the email gets buried. These small gaps lead to delayed closings and, in the worst cases, lost commissions.
A centralized deal tracking portal, provided by your mortgage partner, is the single source of truth. Every stakeholder—the team lead, the agent, the transaction coordinator, the loan officer, and the processor—sees the exact same information.
Example: Your team in Irvine has 25 active escrows. From the portal's dashboard, you can see that three deals have an appraisal due back this week and one is waiting on the borrower to provide their final bank statement. The system automatically flags the file that is stalled, allowing the agent or you to follow up proactively. This prevents a last-minute fire drill and ensures the closing date is met, protecting the commission check tied to that deal.
The Role of a Dedicated Lending Team in Junior Agent Training
New agents don't just need information; they need mentorship. Sending them to a call center where they speak to a different person every time is a recipe for frustration and failure. An integrated lending partnership provides a dedicated lending team—often a lead loan officer, a loan partner, and a processor—who are assigned specifically to your real estate team.
This dedicated 'pod' becomes an extension of your own training program. They:
- Learn Your Culture: They understand your team's communication style, standards, and goals.
- Provide Real-World Scenarios: Instead of generic training, they can workshop actual deals with your junior agents. They can explain why a certain loan structure is better for a client or how to overcome a common underwriting objection.
- Build Confidence: Junior agents are often afraid to ask 'dumb questions'. Having a familiar, trusted lending partner creates a safe space for them to learn and grow without feeling like they are bothering their team leader.
How a Lender's Technology Stack Can Integrate With My Team's CRM
The goal of technology is to create efficiency, not more work. A key component of a Lender Integration Blueprint is ensuring the lender's systems can communicate with yours, primarily your Customer Relationship Management (CRM) software. This eliminates redundant data entry and minimizes human error.
There are a few levels of integration:
- Manual (But Structured): Using standardized file naming conventions and shared cloud folders (like Google Drive or Dropbox) for document exchange. This is the most basic level.
- Middleware Integration (e.g., Zapier): This is the sweet spot for most teams. Zapier acts as a bridge between your CRM (like Follow Up Boss or LionDesk) and the lender's Loan Origination System (LOS). You can create 'Zaps' to automate tasks like, 'When a lead's stage is changed to Active Buyer in the CRM, automatically create a new loan contact in the lender's system'.
- Direct API Integration: For larger, more technologically advanced teams, a direct Application Programming Interface (API) connection offers the most seamless flow of data. This allows for real-time, two-way synchronization of client information, loan status, and key dates.
Why a Standardized Communication Protocol Is Vital for Protecting Team Branding
Your brand is built on consistency. When a client in San Diego works with one agent, their experience should be nearly identical to a client working with another agent in Irvine. If every agent communicates differently and uses a different lender, your brand messaging becomes fractured and unprofessional.
An integrated lender implements a Standardized Communication Protocol that is executed on every single file. This includes:
- Co-Branded Updates: All milestone emails (e.g., 'Your Loan is Approved!') are sent from the lender's system but feature your team's logo and contact information.
- Scheduled Status Calls/Emails: A commitment to a weekly update call or email to the client and agent every Tuesday, for example. This sets clear expectations and prevents clients from feeling like they are in the dark.
- Unified Terminology: The lender trains your agents to use the same language when explaining complex mortgage concepts, ensuring clarity and consistency.
This protocol ensures that no matter which agent a client works with, they receive the same high level of professional, proactive communication that reflects positively on your team's brand.
How to Calculate the ROI of a Strategic Lending Partnership
Moving from a loose vendor relationship to a strategic partnership is a business decision that should be measured. The return on investment (ROI) is not just about getting a lower interest rate; it's about operational efficiency and scalable growth.
Step 1: Quantify Your Current 'Costs'
- Team Leader's Time: Calculate the hours you spend per month on loan-related training and problem-solving. Let's say it's 20 hours/month. If you value your time at $150/hour, that's a $3,000 monthly cost.
- Lost Opportunities: How many deals did your team lose last year due to financing falling through? If it was 3 deals with an average commission of $15,000, that's a $45,000 annual cost.
Step 2: Project the 'Gains' From Partnership
- Reclaimed Time: The 20 hours you get back are now spent on recruiting or landing a high-value listing. The $3,000 monthly cost becomes a gain.
- Increased Capacity: With streamlined systems and training, your team can handle more volume. If the partnership allows your team to close just 5 extra deals per year, that's an additional $75,000 in revenue.
The ROI Calculation
In this simplified example, the annual gain is $75,000 (new deals) + $36,000 (reclaimed time) = $111,000. The 'cost' of a true lending partnership is typically zero dollars; the lender is compensated by the increased loan volume. (The data, information, or policy mentioned here may vary over time.) You're not paying a subscription fee. You are simply committing to a more efficient process.
The ROI is immense because it allows you to transition from working in your business to working on your business. If you're a team leader feeling more like a loan officer than a CEO, it might be time to explore a true partnership. A Lender Integration Blueprint isn't just about getting loans closed—it's about getting your time back and building a scalable business.
Ready to stop being the bottleneck and start being the visionary for your team? A strategic lending partnership gives you the systems and support to scale efficiently. Explore a better process and apply now to see how we can help you reclaim your time.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.









