Written and reviewed by David Ghazaryan, Mortgage Broker, NMLS 1486726 · iQRATE Mortgages, NMLS 1862492 · 6360 S Rainbow Blvd, Las Vegas, NV · Last updated: October 24, 2026
Quick answer: Henderson is in Clark County, so for 2026 any loan above $832,750 on a one-unit home is a jumbo loan. In Henderson's luxury communities (MacDonald Highlands, Ascaya, Anthem Country Club and Lake Las Vegas) the loan itself works like any jumbo, but the property details drive the file: hillside custom homes are harder to appraise, vacant lots need a different kind of loan, and lake or resort-style condos need a project review. Know which of those applies to your home before you write the offer.
Henderson's high end isn't one market. A finished estate on a golf course in MacDonald Highlands, a raw homesite in Ascaya and a lakeside condo at Lake Las Vegas can all carry similar price tags, and each one gets financed differently. Here's how we think about each.
The 2026 jumbo line in Henderson
FHFA set the 2026 baseline conforming loan limit for a one-unit home at $832,750, and every county in Nevada, including Clark County, sits at that baseline. There's no high-balance tier in between. Your loan is either conforming (at or under the limit) or jumbo (over it). The limit applies to the loan amount, so the size of your down payment decides which side you land on.
For the basics of how jumbo programs work for Nevada buyers, see our jumbo loan page.
MacDonald Highlands
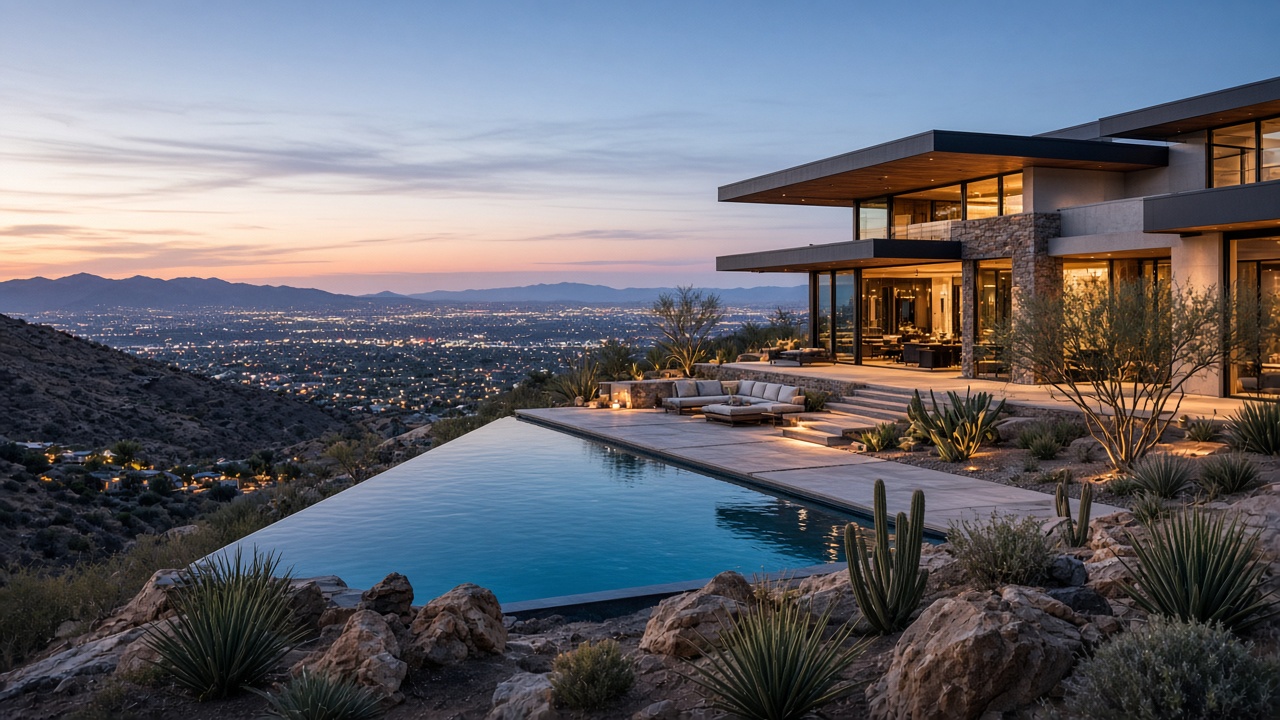
MacDonald Highlands is a guard-gated master plan of about 1,320 acres in the McCullough Range foothills, with two 24-hour guard-gated entries and the private DragonRidge Country Club and its 18-hole course inside the gates. Many homes are custom or semi-custom estates with valley and Strip views, and the community still has custom homesites for sale.
What matters for the loan:
- Appraisals on view homes. Strip-view hillside lots are scarce, and that scarcity is what the price reflects. An appraiser needs closed sales with similar views and lot positions to support the value. When there aren't many, the underwriter reads the adjustments closely. Some jumbo programs require a second appraisal above certain loan sizes.
- Club membership is separate. DragonRidge membership is by application and separate from owning a home there. If you choose to join, those dues generally aren't required housing costs. If a specific neighborhood's documents make any dues mandatory, we count them.
- Layered HOAs. Secondary gates inside MacDonald Highlands lead to sub-neighborhoods, and those often have their own association on top of the master. We pull every layer into your payment.
Ascaya
Ascaya is a separate guard-gated community next to MacDonald Highlands, set higher in the McCullough Range on about 664 acres. It's design-driven: every custom home goes through the community's Architectural Review Committee, and there's no golf course. A lot of Ascaya activity is buyers purchasing homesites to build on.
That changes the financing completely:
- A jumbo purchase loan is for a finished home. If you're buying a completed Ascaya home, it's a standard jumbo purchase, with the same custom-home appraisal homework as above.
- A lot is not a house. Buying a vacant homesite usually means paying cash, using a lot loan or rolling the lot into a construction loan. Lot loans typically need more down than a home loan and come from a smaller pool of lenders.
- Building means a construction loan. A custom build is usually financed with a construction-to-permanent loan or a construction loan followed by a jumbo "takeout" loan when the home is finished. We cover how those work in our guide to jumbo loans for new construction and custom homes in Las Vegas.
Anthem Country Club
Anthem Country Club is a guard-gated golf community inside the larger Anthem master plan in Henderson. Homes range from semi-custom to custom, and many sit on or near the course. From a lending standpoint it's similar to MacDonald Highlands: watch the combined HOA layers, check whether any club-related dues are mandatory and plan the appraisal on golf-frontage or view homes.
One more point for Anthem and similar established communities: older custom homes may have had additions, casitas or remodels over the years. Appraisers and underwriters may ask whether that work was permitted. If something wasn't, it's better to learn that during inspection than during underwriting.
Lake Las Vegas
Lake Las Vegas is a master-planned resort community of roughly 3,600 acres in Henderson built around a privately owned, man-made lake of about 320 acres. It includes the Reflection Bay Golf Club, a public Jack Nicklaus course, and SouthShore, a guard-gated country club enclave with its own private Nicklaus course. The community map also identifies The Island as guard-gated. Housing ranges from estates to townhomes and condos.
What matters for the loan:
- Second-home buyers are common here. If you'll use the home part of the year and not rent it out, a second-home jumbo may fit. If you plan to rent it, that's an investment property, which has different rules and pricing.
- Condos and townhomes need a project review. If the home is in a condominium project, the lender reviews the HOA's budget, reserves, insurance, delinquencies and any litigation. Resort-style projects get extra scrutiny for hotel-like features such as rental programs or front-desk services. Our guide to high-rise condo jumbo loans and warrantability explains those rules.
- Lakefront and hillside appraisals. Lake frontage and views drive value, and appraisers need similar sales to support them, the same issue as in the foothills.
Property taxes: primary home vs. second home in Henderson
Nevada limits how fast your property tax bill can grow through a partial abatement, often called the tax cap. Under Nevada law, an owner-occupied single-family home that you designate as your primary residence gets the lowest cap, 3 percent a year. Other property, including a second home or a rental, falls under a different cap that can run up to 8 percent a year depending on the county's calculation. Newly built homes generally don't get the abatement in their first year on the tax roll.
Why this matters for a jumbo: lenders qualify you on the property tax figure they estimate for your loan, and on a high-value Henderson home that number is a real part of the payment. If you're buying a second home at Lake Las Vegas or Anthem, don't assume the seller's tax bill is what you'll pay. We estimate it based on your occupancy so your debt-to-income math holds up.
Henderson jumbo approval: what lenders look at
Whichever community you're buying in, a Henderson jumbo approval comes down to the same core items:
- Credit. Jumbo programs set their own minimum scores, which are typically higher than conforming minimums and rise with loan size.
- Income. W-2, self-employed, bank statement and asset-based options all exist. Self-employed and business-owner files are common in this price range, and documentation choices matter.
- Debt-to-income. Every required housing cost counts: principal, interest, taxes, insurance, every HOA layer and any SID assessment.
- Down payment and reserves. Jumbo lenders usually want a meaningful cushion after closing, measured in months of your housing payment, and the requirement grows with loan size and with every other financed property you own.
If your down payment is close to the line, compare a single jumbo against a first-and-second-lien structure. We break that down in jumbo vs. piggyback loans in Las Vegas and Henderson.
What we'd do
- Pin down the property type first. Finished home, homesite, new build or condo? That single answer decides which lenders and programs we shop.
- Total the real monthly cost, with master and sub-HOA dues, guard-gate costs, any SID balance and any mandatory dues.
- Match income documentation to the program. We'd rather pick the right documentation path at the start than switch programs halfway through.
- Prepare for the appraisal on view, golf or lakefront homes, including whether a second appraisal applies.
- Shop the file across our lender network and show you the trade-offs side by side.
If you're looking in MacDonald Highlands, Ascaya, Anthem or Lake Las Vegas, call our Las Vegas office or visit our Henderson mortgage broker page.
FAQ
What is the 2026 jumbo loan limit in Henderson, Nevada?
Henderson is in Clark County, where the 2026 one-unit conforming loan limit is $832,750. Loans above that on a one-unit home are jumbo loans.
Can I use a jumbo mortgage to buy a lot in Ascaya or MacDonald Highlands?
Usually not. Jumbo purchase loans are for finished homes. A vacant homesite is typically bought with cash, a lot loan or a construction loan that includes the lot.
Do DragonRidge Country Club dues count in my debt-to-income ratio?
DragonRidge membership is separate from owning a home in MacDonald Highlands, so optional dues generally aren't counted. Any dues that a community's documents make mandatory would be counted like HOA dues.
Can I get a jumbo loan for a second home at Lake Las Vegas?
Many jumbo programs allow second homes, often with somewhat stricter down payment and reserve rules than a primary residence. You have to use it as a second home and not run it as a rental.
Are Lake Las Vegas condos harder to finance with a jumbo loan?
They can be. Condos need a project review, and resort-style projects are checked for hotel-like features, budget and reserve health, delinquencies and litigation. We review the project before you commit.
Investor loans are for business-purpose use only.
iQRATE Mortgages LLC, NMLS 1862492. Equal Housing Opportunity. Not a commitment to lend; terms subject to underwriting.