Who is the best mortgage broker in Henderson, NV?
A strong Henderson mortgage broker should be local to the Las Vegas valley, compare many lenders, and handle everything from first homes in Inspirada to jumbo loans in MacDonald Highlands and Lake Las Vegas. iQRATE Mortgages is a Las Vegas-area broker led by David Ghazaryan that serves Henderson buyers and homeowners for purchase, refinance, jumbo, bank-statement and DSCR loans.
Proof: we worked with a full-time online content creator buying a roughly $3M Henderson home, whose income did not fit a standard paycheck, and his team came back to us in January 2022 about refinancing it.
Our ratings: Google 5.0 from 77 reviews. Call or text (702) 766-3744. iQRATE Mortgages, NMLS #1862492.
Reviewed by David Ghazaryan, Mortgage Broker, NMLS 1486726 · iQRATE Mortgages, NMLS 1862492 · Updated October 31, 2026
Quick answer
A Henderson mortgage broker compares many lenders to price your loan instead of offering one bank's rates. iQRATE Mortgages is 15 minutes away at 6360 S Rainbow Blvd in Las Vegas and shops more than 100 lenders on complex files. Henderson's 2026 limits are Clark County's: $832,750 conforming and $541,287 FHA. Henderson's tax rate (about $2.9613 per $100 of assessed value) is lower than the City of Las Vegas's, but many newer master-planned homes carry SID or LID assessments. Full-doc loans close in about 17 days.
Get My Custom Rate Now · or call (702) 766-3744
5.0 stars from 87 reviews on Experience.com (October 2026) · Read David's reviews on Experience.com
Henderson buyers tend to be move-up families, retirees and relocating Californians, and the city's master-planned communities mean HOAs, special assessments and lots of new construction. That's where a broker helps: matching builder timelines, comparing a builder's preferred-lender incentive against an outside quote, and making sure assessments are in your numbers from day one.
Part of our Nevada mortgage broker coverage.
The Henderson housing market in 2026
- Prices: Henderson's median sold price was about $490,000 in mid-2026 (MLS-based city data from Nevada Real Estate Group), with a September median asking price near $535,000. That sits above the Southern Nevada median of $470,000 (Las Vegas Realtors, September 2026).
- New construction: Cadence, Inspirada and the West Henderson areas are still building, so builder incentives and rate buydowns are common. We compare them with an outside lender, because a builder credit isn't always the cheapest deal.
Neighborhoods and ZIPs we lend in: Green Valley and Green Valley Ranch (89014, 89052, 89074), Anthem and Sun City Anthem (89044, 89052), Seven Hills and MacDonald Highlands (89012, 89052), Inspirada (89044), Cadence (89011), Lake Las Vegas (89011), and older central Henderson near Water Street (89002, 89015).
Henderson at a glance
Henderson is Nevada’s second-largest city: the Census Bureau estimates 353,289 residents on July 1, 2025, up 11.5% from the April 2020 base. Compared with the rest of the valley it is older, higher-income and more owner-occupied, with 20.8% of residents aged 65 or over, a $90,138 median household income and a 66.1% owner-occupancy rate. Those numbers explain the loan mix we see in Henderson: move-up buyers, retirees and relocating households, a higher share of jumbo and high-balance loans, and buyers whose income comes from a business, a pension or investments rather than a single paycheck.
| Measure | Henderson | Why it matters for a mortgage |
|---|---|---|
| Population, July 1, 2025 estimate | 353,289 (up 11.5% from the April 2020 estimates base; 317,610 in the 2020 Census) | Steady in-migration keeps resale and new-construction demand moving |
| Households (2020-2024 ACS) | 132,573, with 2.49 persons per household | Smaller households than North Las Vegas; more single-story and 55+ demand |
| Owner-occupied housing rate | 66.1% | A deep base of comparable owner sales for appraisals |
| Median value of owner-occupied homes (2020-2024 ACS) | $484,900 | A survey figure that lags current sale prices |
| Median monthly owner costs with a mortgage | $2,079 | Survey average across older and newer loans, not a quote for a new loan |
| Median monthly owner costs without a mortgage | $617 | Many long-time owners and retirees own outright, which shapes cash-out and downsizing decisions |
| Median gross rent | $1,824 | The rent many buyers compare against ownership costs |
| Median household income (2024 dollars) | $90,138 | Relevant for assistance-program income limits |
| Persons 65 and over | 20.8% | A large retiree market, including Sun City Anthem |
| Veterans | 24,204 | VA loans remain an important part of the market |
| Mean travel time to work | 24.3 minutes | Short commutes to the Strip, the airport and the 215 corridor |
Sources: U.S. Census Bureau QuickFacts, Henderson city, Nevada (V2025 estimates and 2020-2024 ACS). Checked October 30, 2026.
Henderson home values by ZIP code (September 2026)
Henderson is several markets in one. Typical home values in the ZIP codes Zillow assigns to Henderson run from about $399,222 to about $594,397 in its September 2026 Home Value Index, and every one of them is a little below where it was a year earlier. The Zillow figure is a typical (middle-tier) value for all homes, single-family and condo together, so it reads lower than a single-family sale median and far lower than the guard-gated luxury enclaves. Use it to compare areas, and the price of the home you are buying to pick your loan.
| ZIP | Area (approximate) | Typical value, Sep 2026 | 1-year change | FHA fit at a typical value (1-unit limit $541,287) |
|---|---|---|---|---|
| 89002 | Black Mountain, Mission Hills and older central Henderson | $459,835 | -1.3% | Fits under the 1-unit FHA limit with 3.5% down |
| 89011 | Cadence and Lake Las Vegas | $468,182 | -2.3% | Fits under the 1-unit FHA limit with 3.5% down |
| 89012 | MacDonald Ranch, MacDonald Highlands and Green Valley | $521,350 | -1.6% | Fits under the 1-unit FHA limit with 3.5% down |
| 89014 | Green Valley North | $399,222 | -2.3% | Fits under the 1-unit FHA limit with 3.5% down |
| 89015 | East Henderson, Water Street area and Aries | $400,850 | -1.7% | Fits under the 1-unit FHA limit with 3.5% down |
| 89044 | Inspirada, Anthem’s south side and Sun City Anthem (part) | $525,513 | -3.3% | Fits under the 1-unit FHA limit with 3.5% down |
| 89052 | Green Valley South, Anthem, Seven Hills and Sun City Anthem (part) | $594,397 | -1.2% | Above the FHA limit at 3.5% down; conventional or a larger down payment |
| 89074 | Green Valley and Green Valley Ranch | $457,217 | -2.9% | Fits under the 1-unit FHA limit with 3.5% down |
Sources: Zillow Research, ZHVI by ZIP code, all homes, smoothed and seasonally adjusted (September 2026); HUD Mortgagee Letter 2025-23 (2026 FHA limits). Checked October 30, 2026.

Chart: every Henderson ZIP dipped in the past year. Inspirada and the south side fell most.
How to read this: in most Henderson ZIPs, a typical home fits under the 2026 FHA limit with 3.5% down. In 89052 it does not. The upper tier of 89012 and 89052 runs far past the conforming limit. Area names are approximate. ZIP codes do not follow neighborhood or city lines. Some homes with a Henderson mailing address sit in unincorporated Clark County.
What actually sold: July 2026 closings and September listings
Zillow’s index smooths the market; sale data shows how it feels to a buyer. Nevada Real Estate Group’s September 2026 Henderson report, built from the Las Vegas REALTORS MLS, counted every one of 2,367 active Henderson listings on September 15 and every July closing once the month had fully posted. The headline: Henderson still carries a price premium over the valley, but it is a negotiating market, with 44.0% of listings cut and 60.5% of July sales closing below their final list price.
| Measure | Figure | What it means for a buyer |
|---|---|---|
| Active listings | 2,367 | Real choice at most price points |
| Listings with at least one price cut | 1,041 (44.0%), median cut $20,000 (3.7%) | Room to ask for a price reduction or a seller credit |
| Median asking price | $535,000 ($599,990 single-family; $364,900 condo and townhome) | Many single-family listings sit above the FHA limit |
| Median asking price per square foot | $276 | Compare with the $256 sold figure when you judge a list price |
| July closings | 476 | Roughly 475 homes a month change hands inside city limits |
| July median sold price | $490,000 ($525,000 single-family; $330,000 condo and townhome) | Price your pre-approval to the settled median for your ZIP and type |
| July sale-to-list ratio | 98.8% (60.5% sold below list, 12.8% above) | Most buyers negotiated; a minority competed |
| July median days on market | 38 (52.3% of sold homes had cut price first) | You usually have time for inspections and a clean appraisal |
| August closings posted by September 15 | 211 at a $505,400 provisional median | Direction, not a final result |
Sources: Nevada Real Estate Group, Henderson market report September 2026 (GLVAR MLS data; actives counted September 15, July 2026 closings settled). Checked October 30, 2026.
Single-family vs condo and townhome: July 2026 closings
| Type | Closings | Median sold | Sale-to-list | Below list | Above list | Price per sq ft | Median days on market |
|---|---|---|---|---|---|---|---|
| Single-family | 371 | $525,000 | 98.9% | 61.5% | 12.4% | $267 | 37 |
| Condo and townhome | 93 | $330,000 | 98.6% | 58.1% | 16.1% | $237 | 38 |
Sources: Nevada Real Estate Group, Henderson market report September 2026 (GLVAR MLS data; actives counted September 15, July 2026 closings settled). Checked October 30, 2026.
The financing difference between those two rows is bigger than the price. A $330,000 condo or townhome can be a low-cash FHA, VA or conventional purchase, but only if the project qualifies: lenders review the HOA budget, reserves, owner-occupancy mix, litigation and insurance. A single-family home fits under the FHA limit with 3.5% down only at a price of about $560,900 or less, so many single-family buyers here use conventional financing instead.
Henderson by ZIP: listings and July sales
| ZIP | Active listings | Median ask | Share with a price cut | July closings | July median sold | Sale-to-list |
|---|---|---|---|---|---|---|
| 89011 (Cadence and Lake Las Vegas) | 658 | $534,999 | 46.0% | 94 | $459,535 | 100.0% |
| 89052 (Green Valley South and Anthem) | 332 | $682,400 | 42.5% | 69 | $640,000 | 98.2% |
| 89012 (MacDonald Ranch and Green Valley) | 313 | $799,000 | 34.5% | 49 | $610,000 | 98.4% |
| 89015 (East Henderson and Aries) | 270 | $430,950 | 42.6% | 62 | $391,688 | 100.0% |
| 89044 (Inspirada) | 244 | $543,415 | 46.7% | 81 | $520,000 | 98.8% |
| 89074 (Green Valley) | 229 | $499,900 | 42.8% | 51 | $430,000 | 98.6% |
| 89014 (Green Valley North) | 161 | $439,750 | 50.9% | 31 | $442,000 | 98.7% |
| 89002 (Black Mountain and Mission Hills) | 159 | $510,000 | 50.3% | 38 | $442,500 | 100.0% |
Sources: Nevada Real Estate Group, Henderson market report September 2026 (GLVAR MLS data; actives counted September 15, July 2026 closings settled). Checked October 30, 2026.

Chart: Cadence and Lake Las Vegas (89011) hold more listings than any other ZIP.

Chart: about half of the listings in Green Valley North and Black Mountain had cut their price. That gives buyers room to ask for seller credits.
Want to know what a seller credit could cover on your Henderson offer? Call or text (702) 766-3744 or apply now.
Three details matter for financing. First, 89011 has the most listings of any Henderson ZIP because Cadence is still building; that is where builder incentives and outside-loan comparisons matter most. Second, 89012’s $799,000 median ask is close enough to the conforming limit that many buyers there are choosing between a conforming loan with a larger down payment and a jumbo. Third, 89015 and 89002 closed July at 100% of list, so well-priced entry-level homes there still draw competition.
Henderson listings by price band, and the loan that usually fits
| Price band | Active listings | Share of board | Share with a price cut | Financing most often used |
|---|---|---|---|---|
| Under $400,000 | 526 | 22.2% | 48.5% | FHA, VA, conventional with 3% to 5% down, Home Is Possible assistance |
| $400,000 to $500,000 | 522 | 22.1% | 47.1% | FHA up to the limit, VA, conventional |
| $500,000 to $650,000 | 472 | 19.9% | 47.9% | Conventional; FHA only at the low end; VA |
| $650,000 to $850,000 | 339 | 14.3% | 44.0% | Conventional, high-balance planning near the $832,750 line, VA |
| $850,000 to $1.5 million | 205 | 8.7% | 42.4% | Jumbo, or conventional with a large down payment; VA for eligible veterans |
| $1.5 million and up | 303 | 12.8% | 25.7% | Jumbo (full-doc, bank statement or asset-based); cash and bridge strategies |
Sources: Nevada Real Estate Group, Henderson market report September 2026 (GLVAR MLS data; actives counted September 15, July 2026 closings settled); FHFA, conforming loan limit values for 2026. Checked October 30, 2026.

Chart: 44% of the board asks under $500,000, where FHA, VA and low-down conventional loans fit.
How Henderson compares with its neighbors
| Market | Active listings | Share cut | Median ask | July closings | July median sold | Sale-to-list | July median days |
|---|---|---|---|---|---|---|---|
| Henderson | 2,367 | 44.0% | $535,000 | 476 | $490,000 | 98.8% | 38 |
| Las Vegas | 8,330 | 43.3% | $469,000 | 1,400 | $430,000 | 98.9% | 28 |
| North Las Vegas | 1,037 | 42.9% | $425,000 | 249 | $415,000 | 100.0% | 19 |
| Summerlin corridor | 1,699 | 46.7% | $630,000 | 322 | $527,500 | 98.2% | 27 |
| Boulder City | 142 | 33.1% | $442,500 | 16 | $442,500 | 98.2% | 25 |
Sources: Nevada Real Estate Group, Henderson market report September 2026 (GLVAR MLS data; actives counted September 15, July 2026 closings settled). Checked October 30, 2026.

Chart: Henderson sold for about $60,000 more than Las Vegas in July, and asks run above recent sales.
The takeaway: Henderson’s settled median is $60,000 above Las Vegas and $75,000 above North Las Vegas, and homes take longer to sell. For buyers, that means more room to negotiate and more reason to plan the loan around the jumbo line and HOA costs. If you are comparing cities, see our Las Vegas, North Las Vegas and Summerlin pages.
Henderson master-planned communities: prices, pace and what they mean for your loan
Most Henderson purchases happen inside a master plan, and each one has its own price level, building stage and HOA structure. The table uses 12 months of MLS closings counted by Nevada Real Estate Group through September 18, 2026.
| Community | Closings | Median sold | Price per sq ft | Median days to contract | Months of supply | Built 2025 or later |
|---|---|---|---|---|---|---|
| Cadence | 648 | $485,000 | $248 | 40 | 4.6 | 64% |
| Anthem (all villages) | 555 | $650,000 | $307 | 34 | 4.7 | 0% |
| Sun City Anthem (55+) | 348 | $588,500 | $300 | 36 | 4.3 | 0% |
| Inspirada | 334 | $559,200 | $256 | 34 | 5.1 | 15% |
| Green Valley | 268 | $485,000 | $269 | 22 | 5.0 | 0% |
| Lake Las Vegas | 264 | $659,900 | $329 | 59 | 11.8 | 34% |
| MacDonald Ranch / Highlands | 160 | $1,978,250 | $502 | 37 | 7.4 | 12% |
| Seven Hills | 119 | $655,000 | $298 | 30 | 6.7 | 0% |
Sources: Nevada Real Estate Group, top-selling communities in Las Vegas and Henderson (MLS closings, 12 months ending September 18, 2026). Checked October 30, 2026.

Chart: only MacDonald Ranch and the Highlands has a median above the conforming limit, so most of its buyers need a jumbo loan.

Chart: Lake Las Vegas has close to a year of supply, the most room to negotiate on this list.
Lake Las Vegas stands out: 11.8 months of supply and a 59-day median to contract, well above most Henderson communities, which gives buyers leverage on price and credits but also means appraisers have fewer recent sales to work with. Green Valley is the opposite, with a 22-day median. Anthem, Seven Hills and Sun City Anthem are resale markets with no 2025-or-later construction in the count; Cadence is mostly new construction.
Henderson neighborhoods and the loan questions that come up most
| Area | Typical housing | Loan questions to settle early |
|---|---|---|
| Green Valley and Green Valley Ranch (89014, 89052, 89074) | Established neighborhoods, golf and park communities | Older roofs, HVAC and water heaters for FHA and VA minimum property standards; count master and sub-association dues |
| Anthem and Sun City Anthem (89044, 89052) | Hillside resale homes; Sun City Anthem is age-restricted (55+) | Age-restricted HOAs are normal for lenders; ask about the HOA budget and any special assessments |
| Seven Hills and MacDonald Ranch / Highlands (89012, 89052) | Guard-gated and custom homes, many above the conforming limit | Jumbo documentation and reserves; appraisals for unique custom homes can take longer |
| Inspirada (89044) | Master plan begun in the 2000s (district billing began June 1, 2008); mostly resale plus some new homes | City of Henderson LID T-18 assessment through June 1, 2035, plus quarterly master dues |
| Cadence (89011) | Large new-construction master plan with many builders | Builder incentives versus an outside loan; master and some sub-association dues; no SID or LID per the developer |
| Lake Las Vegas (89011) | Resort-style community, condos, custom and semi-custom homes | Condo project reviews, higher HOA costs, slower sales; second-home and investor occupancy rules |
| Central and East Henderson, Water Street area (89002, 89015) | Older homes, infill and some new townhomes | Good FHA and first-time buyer territory; check property condition and any manufactured-home rules |
Neighborhood descriptions are general and for orientation only. We do not steer buyers to or away from any area; where you buy is your choice, and every loan is underwritten on the same rules wherever the home is.
Henderson closing-cost and property-tax notes
- Transfer tax: Clark County's $2.55 per $500 (0.51%); on a $490,000 home that's about $2,499, customarily paid by the seller.
- Property tax: Henderson's FY 2026–27 district rate is about $2.9613 per $100 of assessed value (assessed value is 35% of taxable value). File the primary-residence claim after closing to keep the 3% cap.
- SIDs and LIDs: Inspirada and some other Henderson neighborhoods carry special or local improvement district assessments (Cadence has none, per its developer), billed with or alongside property taxes. They raise your monthly payment and some can be paid off; we show them in your Loan Estimate's escrow math.
- 55+ communities: Sun City Anthem and similar age-restricted HOAs are normal for lenders, but condo and PUD project reviews still apply.
Closing costs are not your cash to close
Closing costs are what it costs you to get the loan: origination, discount points, appraisal, and escrow and title. Cash to close also includes your prepaids (first-year homeowners insurance, daily interest to month-end, and an escrow deposit for your own future property taxes and insurance) plus your down payment. Prepaids aren't a cost of the loan; they're your own bills paid ahead. For iQRATE clients, Nevada closing costs typically run about $6,000–$8,000 on full-documentation loans and about $15,000 on some non-QM loans, itemized on your Loan Estimate. See how Nevada compares with California, Texas and Florida on our closing costs by state page.
Clark County transfer tax at Henderson prices
Clark County’s real property transfer tax (RPTT) is $2.55 per $500 of value, rounded up to the next $500. By local custom the seller pays it in Southern Nevada, but the purchase contract controls, and buyer and seller are both liable under state law if it goes unpaid. At Henderson price points the tax is large enough to be worth reading in your contract.
| Price | Transfer tax | Customarily paid by |
|---|---|---|
| $350,000 | $1,785.00 | Seller (negotiable) |
| $490,000 | $2,499.00 | Seller (negotiable) |
| $525,000 | $2,677.50 | Seller (negotiable) |
| $650,000 | $3,315.00 | Seller (negotiable) |
| $832,750 | $4,248.30 | Seller (negotiable) |
| $1,000,000 | $5,100.00 | Seller (negotiable) |
| $1,500,000 | $7,650.00 | Seller (negotiable) |
| $2,000,000 | $10,200.00 | Seller (negotiable) |
Sources: Nevada Department of Taxation, real property transfer tax. Checked October 30, 2026.

Chart: the tax is about 0.51% of the price. By local custom the seller pays, but the contract decides.
Henderson property tax: the rate, the math and the cap
Henderson has one of the lower city property-tax rates in Clark County: $2.9613 per $100 of assessed value for fiscal year 2026-2027 in the main city district (500). Nevada taxes 35% of a home’s taxable value, and the Assessor’s taxable value is often well below the price you pay, because land is valued separately and improvements are valued at replacement cost less depreciation. Nevada’s cap then limits how fast your bill can rise.
| District | Rate per $100 of assessed value | Tax per $100,000 of taxable value, before the cap |
|---|---|---|
| Henderson city (district 500) | $2.9613 | $1,036.45 |
| City of Las Vegas (district 200) | $3.2782 | $1,147.37 |
| North Las Vegas city (district 250) | $3.3544 | $1,174.04 |
| Paradise town, unincorporated (district 470) | $2.9328 | $1,026.48 |
| Fiscal year | Rate per $100 of assessed value | Change |
|---|---|---|
| 2024-2025 | $2.9604 | — |
| 2025-2026 | $2.9611 | +$0.0007 |
| 2026-2027 | $2.9613 | +$0.0002 |
Sources: Clark County Treasurer, tax rates by district, FY 2024-2025 to FY 2026-2027; NRS 361.4723 (property-tax cap). Checked October 30, 2026.

Chart: Henderson’s city rate runs about $111 per $100,000 below the City of Las Vegas.
Your actual bill is usually lower than rate times price, for two reasons. First, the Assessor’s taxable value is not the sale price. Second, the cap: under NRS 361.4723 the bill on your primary residence can rise no more than 3% a year, while rentals and other property get a cap of up to 8%. New construction gets no cap in its first year, so Cadence and other new-home buyers should expect a bigger change after the first full assessment. If you buy a resale home, the seller’s capped bill may not be what you pay as an investor; ask us to estimate both. Some Henderson parcels sit in redevelopment or other overlapping districts, so we confirm the exact district on the Assessor’s parcel record.
Henderson LIDs and SIDs: the assessment many buyers miss
Some Henderson neighborhoods were built with roads, sewers, drainage or parks financed through a Local Improvement District (LID) or Special Improvement District (SID). Each owner repays a share of the bonds through an annual assessment on the parcel, on top of property tax and HOA dues. For a mortgage, the assessment works like part of your housing payment: the lender adds it to your monthly obligations, so it reduces how much home you qualify for. In Henderson, LID bills are issued by Assessment Management Group, which can give the current status and a payoff figure for a parcel; most assessments can be paid off early.
| Item | Inspirada (89044) | Cadence (89011) |
|---|---|---|
| Master association dues, 2026 | $255 per quarter | $225 per quarter |
| Improvement district | City of Henderson LID T-18; final installment June 1, 2035 | None, per the developer’s FAQ |
| Assessed parcels in the district | 6,086 on December 31, 2025 | Not applicable |
| District billing began | June 1, 2008 | Not applicable |
| Sub-associations | Some neighborhoods | Some neighborhoods; some condo and townhome areas have non-HOA assessment fees |
| 12-month closings / median sold | 375 / $543,750 (12 months ending August 31, 2026) | 690 / $479,400 (same period) |
Sources: Nevada Real Estate Group, Inspirada vs Cadence (October 15, 2026); Cadence community FAQs; City of Henderson Finance, LID / Special Assessments page (LID bills are issued by Assessment Management Group). Checked October 30, 2026.

Chart: the master dues differ by $120 a year. The LID and any sub-association dues matter more, so check the title report.
Comparing Inspirada and Cadence? We can show how the dues and LID affect your approval. Call or text (702) 766-3744 or apply now.
How we handle it: we order the title report as soon as you are under contract (earlier when you are deciding between neighborhoods), read the LID or SID line, and ask the HOA for the resale package figures for every association on the property. Those numbers go into your debt-to-income ratio from day one. A buyer who finds a $1,000-plus annual assessment in underwriting may no longer qualify at the same price; a buyer who knows on day one can adjust the offer or the program.
Henderson closing costs, line by line
For iQRATE clients, closing costs on full-documentation loans typically run about $6,000 to $8,000, and about $15,000 on some non-QM loans, before prepaids and your down payment. Jumbo loans can run higher because of second appraisals and larger title premiums. The table lists each common line item, where it appears on the Loan Estimate, and who typically pays in Southern Nevada. Every item is negotiable in the purchase contract, and your Loan Estimate is the document that controls the numbers.
| Item | Loan Estimate section | Typically paid by | Henderson notes |
|---|---|---|---|
| Origination or broker fee | A. Origination charges | Buyer | Compare this line across offers |
| Discount points (optional) | A. Origination charges | Buyer | Points buy a lower rate; ask for the break-even month |
| Appraisal | B. Services you cannot shop for | Buyer | Some jumbo loans need two appraisals |
| VA funding fee or FHA upfront premium | B. Services you cannot shop for (usually financed) | Buyer, unless exempt | See the VA and FHA tables below |
| Lender’s title policy | C. Services you can shop for | Buyer | Premium rises with the loan amount |
| Escrow or settlement fee | C. Services you can shop for | Often split buyer and seller | VA limits some fees the veteran can pay |
| Owner’s title policy | H. Other | Often the seller in Southern Nevada (negotiable) | Protects you; confirm in the contract |
| Recording fees | E. Taxes and other government fees | Buyer for the deed of trust | Clark County Recorder |
| Transfer tax (RPTT) | E. Taxes and other government fees | Seller by custom (negotiable) | $2.55 per $500 of value |
| Prepaid interest, insurance and tax escrow | F. Prepaids and G. Initial escrow | Buyer | Your own future bills paid ahead, not a cost of the loan |
| HOA transfer, resale package and capital contribution | H. Other | Varies by contract and HOA | Two associations can mean two sets of fees |
| LID or SID payoff (optional) | Payoffs and payments, or H. Other | Negotiable | Ask for the AMG payoff figure; many buyers simply assume the assessment |
| Home inspection | H. Other (or paid outside closing) | Buyer | Strongly recommended, especially on older Green Valley homes |
Sources: CFPB, Loan Estimate explainer; Nevada Department of Taxation, real property transfer tax. Checked October 30, 2026.
Want to lower your cash to close? The usual levers are a seller credit, a lender credit in exchange for a higher rate, down payment assistance, a builder incentive on new construction, or a documented gift from a family member. With 44% of Henderson listings carrying a price cut in September 2026, a seller credit is often a realistic request. Each option comes with program rules and limits; we put them side by side on Loan Estimates so you can pick the trade-off you prefer.
2026 loan limits in Henderson
Conforming $832,750 and FHA $541,287 for a one-unit home in 2026 (Clark County). Duplexes go to $1,066,250 conforming. MacDonald Highlands, Ascaya and Lake Las Vegas purchases usually need jumbo financing.
Jumbo loans in Henderson, NV
Short answer: Henderson is in Clark County, so for 2026 any loan above $832,750 on a one-unit home is a jumbo loan (FHFA). Henderson communities where prices often exceed that include MacDonald Highlands, Ascaya, Anthem Country Club and Lake Las Vegas.
For loans above $832,750, read our Henderson jumbo loans guide: 2024-2025 City of Henderson loan data by ZIP, jumbo denial reasons, local costs and requirements.
| Henderson jumbo fact (updated Oct 28, 2026) | Detail |
|---|---|
| 2026 conforming limit, 1 unit | $832,750 (FHFA, Clark County) |
| Typical down payment | 10-20% (varies by lender) |
| Typical reserves | About 6-12 months of payments (varies by lender) |
| Options | Full-doc, bank-statement, asset-depletion and interest-only jumbo |
Guard-gated and golf communities can add HOA document reviews, and larger loans may require a second appraisal (varies by lender). See our full Las Vegas jumbo loan guide or call (702) 766-3744. David Ghazaryan, NMLS 1486726; iQRATE Mortgages, NMLS 1862492. Equal Housing Opportunity.
More Henderson and Las Vegas jumbo guides
- Henderson jumbo loans: MacDonald Highlands, Ascaya, Anthem and Lake Las Vegas
- Summerlin jumbo loans for guard-gated and golf course homes
- Moving from California? Buy in Las Vegas with a jumbo before you sell
- Jumbo loans for new construction and custom homes in Las Vegas
- Las Vegas jumbo down payment and reserve requirements in 2026
- Las Vegas high-rise condo jumbo loans and warrantability
Sources: FHFA 2026 county loan limit list (Clark County, NV); FHFA 2026 conforming loan limit announcement; FFIEC HMDA Data Browser (2025 first-lien home purchase loans, Las Vegas-Henderson-North Las Vegas metro).
2026 loan limits in Clark County by number of units
| Property | Conforming limit | FHA limit |
|---|---|---|
| 1 unit | $832,750 | $541,287 |
| 2 units | $1,066,250 | $693,050 |
| 3 units | $1,288,800 | $837,700 |
| 4 units | $1,601,750 | $1,041,125 |
Sources: FHFA, conforming loan limit values for 2026; HUD Mortgagee Letter 2025-23 (2026 FHA limits). Checked October 30, 2026.
Clark County is a low-cost area for FHA, so its limits are the national floor set at 65% of the conforming limit. VA has no loan limit for borrowers with full entitlement; veterans with a VA loan already outstanding may have a limit tied to the conforming figure. In Henderson the limits matter more than anywhere else in the valley: the July 2026 single-family median of $525,000 sits just under the price at which a 3.5%-down FHA loan reaches its limit, and a large share of Anthem, Seven Hills, MacDonald Ranch and Lake Las Vegas homes are above the conforming line.
Where the jumbo line falls at Henderson prices
A loan above $832,750 on a one-unit home is a jumbo loan in Clark County in 2026. Whether your loan crosses the line depends on both the price and your down payment. The table shows the highest price you can pay and still stay conforming at each down payment.
| Down payment | Highest conforming price | Loan amount at that price | Cash down at that price |
|---|---|---|---|
| 3% | $858,505 | $832,750 | $25,755 |
| 5% | $876,579 | $832,750 | $43,829 |
| 10% | $925,278 | $832,750 | $92,528 |
| 15% | $979,706 | $832,750 | $146,956 |
| 20% | $1,040,938 | $832,750 | $208,188 |
| 25% | $1,110,333 | $832,750 | $277,583 |
Sources: FHFA, conforming loan limit values for 2026. Checked October 30, 2026.
Why it matters: jumbo loans usually need more reserves (often several months of payments in the bank after closing), sometimes a second appraisal, and full documentation unless you use a non-QM jumbo. Pricing can be better or worse than conforming depending on the day and the lender. Some Henderson buyers bring a slightly larger down payment to stay conforming; others prefer to keep cash and take the jumbo. A conforming first mortgage plus a second lien is another structure some lenders offer. We price the options side by side. See our jumbo loan page for documentation and reserve details.
FHA mortgage insurance in Henderson
FHA loans carry two premiums: an upfront premium of 1.75% of the base loan, which is usually added to the loan, and an annual premium paid monthly. For a 30-year FHA loan with a base loan at or under $726,200, which covers every Clark County FHA purchase at the 2026 one-unit limit, the annual premium depends on how much you put down.
| Down payment (loan-to-value) | Upfront premium | Annual premium | How long the annual premium lasts |
|---|---|---|---|
| Under 5% down (LTV above 95%) | 1.75% of the base loan | 0.55% | Life of the loan |
| 5% to under 10% down (LTV above 90% to 95%) | 1.75% of the base loan | 0.50% | Life of the loan |
| 10% or more down (LTV 90% or less) | 1.75% of the base loan | 0.50% | 11 years |
Sources: HUD Mortgagee Letter 2023-05 (FHA mortgage insurance premiums). Checked October 30, 2026.
Video: Stop Paying FHA Mortgage Insurance For 30 Years
David compares FHA and conventional loans for a first home. He covers removing mortgage insurance, assumability when you sell, renting the home later and refinance options. Read the notes on the video page. Questions about your own Henderson file? Call (702) 766-3744.
Because FHA premiums last for the life of the loan when you put less than 10% down, many buyers start with FHA and later refinance into a conventional loan once they have enough equity. Conventional private mortgage insurance, by contrast, can be removed under federal rules as you pay down the loan or the home gains value. At Henderson prices, a buyer with good credit often finds conventional with 5% to 10% down costs less than FHA; we compare both on your Loan Estimates.
VA funding fee for Henderson veterans
Henderson is home to 24,204 veterans, according to the Census Bureau. The VA funding fee is a one-time charge that replaces monthly mortgage insurance on VA loans. It is a percentage of the loan amount and can be financed. Veterans who receive VA compensation for a service-connected disability, and some others, are exempt.
| Down payment | First use | After first use |
|---|---|---|
| Less than 5% | 2.15% | 3.3% |
| 5% or more | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
| Loan type | Funding fee |
|---|---|
| Cash-out refinance, first use | 2.15% |
| Cash-out refinance, after first use | 3.3% |
| Interest rate reduction refinance (IRRRL) | 0.5% |
| Loan assumption | 0.5% |
Sources: VA, funding fee and closing costs; U.S. Census Bureau QuickFacts, Henderson city, Nevada (V2025 estimates and 2020-2024 ACS). Checked October 30, 2026.

Chart: 5% down cuts the fee on a later VA loan from 3.3% to 1.5%. Veterans with a disability rating are generally exempt.
Video: Don't Make This $9,000 VA Funding Fee Mistake
David shows how the VA funding fee works, who is exempt and how a small down payment can lower the fee on a later VA loan. Read the notes on the video page. Questions about your own Henderson file? Call (702) 766-3744.
VA also limits seller concessions to 4% of the home’s reasonable value, but normal closing costs paid by the seller do not count toward that 4%. With full entitlement there is no VA loan limit, so an eligible veteran can buy above $832,750 with no down payment if the lender approves the loan; lenders set their own rules for larger VA loans.
Upfront cash at Henderson prices: FHA, VA and conventional
| Price | FHA 3.5% down | FHA upfront premium (1.75% of base loan, usually financed) | Conventional 5% down | Conventional 10% down | VA, first use, 0% down: funding fee (2.15%, usually financed) |
|---|---|---|---|---|---|
| $400,000 | $14,000 | $6,755 | $20,000 | $40,000 | $8,600 |
| $490,000 | $17,150 | $8,275 | $24,500 | $49,000 | $10,535 |
| $525,000 | $18,375 | $8,866 | $26,250 | $52,500 | $11,288 |
| $650,000 | Over FHA limit | — | $32,500 | $65,000 | $13,975 |
| $800,000 | Over FHA limit | — | $40,000 | $80,000 | $17,200 |
Sources: HUD Mortgagee Letter 2023-05 (FHA mortgage insurance premiums); VA, funding fee and closing costs; HUD Mortgagee Letter 2025-23 (2026 FHA limits). Checked October 30, 2026.

Chart: at the $490,000 July median, FHA needs about $7,350 less down than 5% conventional, before mortgage insurance and closing costs.
About this chart: it redraws numbers already shown in the table above it. Dollar examples are sample math, not an offer of credit, a rate quote or a commitment to lend. Your terms depend on your credit, income, property and program, and are confirmed in writing before you commit.
Sample math only. Dollar examples on this page are arithmetic based on published program rules and public data. They are not an offer of credit or a quote of rates or terms. Your actual down payment, APR, monthly payment and costs depend on your credit, income, property, program and the lender, and appear on your Loan Estimate. All loans are subject to credit, property and underwriting approval.
Down payment help in Henderson
- Home Is Possible: up to 4% for first-time buyers or 5% for repeat buyers, a 0% second mortgage with income and price limits.
- Clark County HOME/AAHTF funds: periodic rounds for income-qualified buyers countywide.
- Not eligible: Nevada Rural Housing's Launchpad excludes Henderson city limits.
Home Is Possible options in detail
The Nevada Housing Division’s Home Is Possible (HIP) programs pair a 30-year fixed first mortgage with down payment assistance delivered as a second mortgage at 0% interest with no monthly payment. The assistance is not forgiven; it is repaid when you sell, refinance or pay off the first mortgage. The right version depends on whether you are a first-time buyer, your income, your credit, the loan type and the price.
| Option | Loan types | Assistance | Who qualifies | Key limits |
|---|---|---|---|---|
| HIP for First-Time Homebuyers (government) | FHA, VA, USDA | 2% or 4% of the loan | First-time buyers (no primary home owned in the last 3 years) | Minimum score 640; program income and price limits apply; maximum debt ratio 50% with a 680+ score, 45% below 680 |
| HIP for First-Time Homebuyers (conventional) | Conventional | 2% or 4% | First-time buyers at or below 80% of area median income | Minimum score 640; maximum purchase price $570,000; maximum debt ratio 50% |
| HIP-DPA (government) | FHA, VA, USDA | 3% or 5% | Repeat or first-time buyers | Minimum score 640; income limit $165,000; price up to $832,750 within agency limits; 1 to 4 units |
| HIP-DPA (conventional, 80% AMI) | Conventional | 3% or 5% | Repeat or first-time buyers at or below 80% of area median income | Minimum score 640; maximum debt ratio 50%; 1 to 4 units |
Sources: Nevada Housing Division, Home Is Possible program highlights (as of October 29, 2026). Checked October 30, 2026.
Video: Nevada Down Payment Help: Grant or Forgivable Loan?
David explains the two kinds of Nevada down payment help: a grant you do not repay and a forgivable second loan. He also covers the income, credit and homebuyer-class rules that usually apply. Read the notes on the video page. Questions about your own Henderson file? Call (702) 766-3744.
In Henderson, the price caps matter. The conventional first-time option tops out at $570,000, which covers the July 2026 single-family median of $525,000 but not the typical 89052 home. FHA-based assistance is limited by the $541,287 FHA loan limit. The trade-off to understand: in the Housing Division’s own published rate sheet, the options with larger assistance carry a higher first-mortgage rate. Assistance lowers the cash you bring to closing, but it can raise your monthly payment and it adds a second lien you repay later. A seller credit plus a standard FHA or conventional loan sometimes costs less over time. We show both on Loan Estimates so you can choose with real numbers.
Henderson first-time buyer playbook
- Get your numbers first. Pull your credit through us, list your monthly debts and gather 30 days of pay stubs, two years of W-2s and two months of bank statements.
- Pick a payment, not a price. Decide the monthly housing payment you are comfortable with, including taxes, insurance, every HOA layer and any LID, then work back to a price.
- Compare three paths. FHA with 3.5% down, conventional with 3% to 5% down, and an assistance program. Veterans add VA with no down payment.
- Know where the inventory is. On September 15, 2026 there were 1,048 Henderson listings under $500,000, about 44% of the board, and roughly 48% of them had already cut price. Condos and townhomes, older Green Valley homes and East Henderson are where most entry-level choice sits.
- Get a fully reviewed pre-approval. A reviewed file lets you negotiate on price and credits from strength, especially in 89015 and 89002, which closed July at 100% of list.
- Check the HOA and condo project early. FHA and VA condo purchases need an approved or eligible project; conventional lenders review the HOA too.
- Write the offer with financing in mind. Ask for a seller credit within your program’s limits, and leave time for the appraisal and HOA documents.
- Close and file your primary-residence claim. Make sure the Assessor has you as owner-occupied so the 3% tax cap applies.
Take a homebuyer education course early. Many assistance programs require one, and it is a useful refresher on budgeting, maintenance and avoiding foreclosure. See our first-time home buyer guide and FHA loan page for more detail.
Sources: Nevada Real Estate Group, Henderson market report September 2026 (GLVAR MLS data; actives counted September 15, July 2026 closings settled). Checked October 30, 2026.
Investing in Henderson: DSCR loans and STR registration
- Henderson's short-term vacation rental rules: owners must register with the city every year, keep at least 1,000 feet from another registered rental and 2,500 feet from a resort hotel, and remit Henderson's 13% transient lodging tax monthly. Homes in an HOA qualify only if the governing documents expressly allow transient lodging, which rules out most master-planned homes.
- Long-term rentals: Henderson's school demand and newer housing stock make it a common choice for long-term rentals. A DSCR loan qualifies on market rent from the appraisal, can close in an LLC, and needs no tax returns.
- Self-employed owners: a bank statement loan uses 12 or 24 months of deposits when write-offs shrink your taxable income.
Henderson rents and DSCR math
A DSCR loan compares the rent a property earns with its full monthly payment: principal, interest, taxes, insurance, HOA dues and any LID or SID assessment. A ratio of 1.0 means rent covers the payment exactly; many lenders want 1.0 to 1.25, and some allow lower with a larger down payment. HUD’s Fair Market Rents for the Las Vegas-Henderson-North Las Vegas metro area give a public benchmark for long-term rents; your appraiser’s rent schedule for the specific home is what the lender actually uses.
| Unit size | FY 2026 FMR | FY 2025 FMR | Change |
|---|---|---|---|
| Efficiency | $1,333 | $1,316 | +$17 |
| 1 bedroom | $1,478 | $1,476 | +$2 |
| 2 bedrooms | $1,735 | $1,750 | -$15 |
| 3 bedrooms | $2,413 | $2,452 | -$39 |
| 4 bedrooms | $2,764 | $2,841 | -$77 |
Sources: HUD FY 2026 Fair Market Rents, Las Vegas-Henderson-North Las Vegas MSA; U.S. Census Bureau QuickFacts, Henderson city, Nevada (V2025 estimates and 2020-2024 ACS). Checked October 30, 2026.

Chart: larger-unit rents slipped for FY 2026, so run DSCR numbers on current rents, not last year’s.
Fair Market Rents are a 40th-percentile gross rent for the whole metro area, so a newer 3- or 4-bedroom home in Inspirada, Cadence or Anthem may rent above the FMR, and an older East Henderson home below it. The Census Bureau’s 2020-2024 median gross rent for Henderson was $1,824. Henderson’s higher prices mean DSCR ratios are tighter here than in North Las Vegas, so investors often bring a larger down payment or pick lower-HOA properties. Two Henderson-specific items change the math: the up-to-8% tax cap on non-owner-occupied homes, and an LID assessment on parcels in districts such as Inspirada’s LID T-18, both of which count in the ratio.
Short-term rentals in Henderson: registration rules that affect your loan
Henderson allows short-term vacation rentals only with a city registration under Henderson Development Code Section 19.9.4.F, and the requirements carry real costs. If short-term income is part of your plan, read the rules before you choose a property, because some of them can make a specific home ineligible.
| Requirement | What it means for a buyer |
|---|---|
| $848 registration fee per property, paid annually, non-refundable | A fixed yearly cost in your budget |
| HOA governing documents must expressly authorize short-term rentals | Many Henderson HOAs do not, which rules those homes out |
| Current Nevada business license in the owner’s name | Plan the ownership entity before you close |
| General liability insurance of at least $1,000,000 | A cost beyond your homeowner’s policy |
| Certification class for the owner and the local contact; the local contact must live in Clark County (NRS 645 licensed managers are exempt from the class) | Out-of-state owners need a local contact or a licensed manager |
| Trust or LLC documents if the owner of record is an entity | Lenders and the city both review the entity |
| 13% combined transient lodging tax, reported monthly by the 15th, even in months with no rentals | Owner is liable whether or not the tax was collected from guests |
| Street-facing camera, noise management plan, smoke and CO alarms, fire extinguishers and an evacuation map | Set-up costs before the first rental |
| A change in record ownership, including a transfer of interests in an owning entity, ends the registration | You cannot buy a seller’s registration; you must register again |
Sources: City of Henderson, Short-Term Vacation Rentals page and STVR registrant acknowledgement form (Henderson Development Code Section 19.9.4.F). Checked October 30, 2026.
Because of these rules, we usually underwrite Henderson homes as long-term rentals and treat short-term income as upside, unless you already hold the approvals and the lender accepts short-term rental income. Homes with a Henderson mailing address that sit in unincorporated Clark County fall under county rules instead, so confirm the jurisdiction on the Assessor’s parcel record.
House hacking a Henderson duplex to fourplex
If you live in one unit, FHA lets you buy a two- to four-unit property with 3.5% down, up to $693,050 for two units, $837,700 for three and $1,041,125 for four in Clark County in 2026, and lenders can count projected rent from the other units to help you qualify. Three- and four-unit FHA purchases must also pass a self-sufficiency test, in which net rent must cover the full payment. VA allows up to four units for eligible veterans who live in one. Small multifamily is limited in Henderson and concentrated in older central and East Henderson, so many house hackers here use a single-family home with a casita or rent rooms instead; ask how a lender treats that income before you count on it.
Which investor loan fits?
| Loan | Qualifies on | Best for | Watch for |
|---|---|---|---|
| Conventional investment loan | Your income, credit and reserves | Your first few rentals with strong tax-return income | Limits on the number of financed properties |
| DSCR loan (business purpose) | The property’s rent compared with its full payment | Self-employed investors, LLC buyers, serial investors growing a portfolio | HOA dues, any LID and the up-to-8% tax cap all count in the ratio |
| Hard money or fix-and-flip (business purpose) | Price, rehab budget, after-repair value and exit plan | Dated Green Valley and East Henderson homes that need work | Short terms; plan the refinance or sale before you close |
| Portfolio or blanket loan (business purpose) | The portfolio’s rents and your experience | Investors with several Henderson and Las Vegas rentals | Cross-collateral and release terms |
| FHA or VA multi-unit (owner-occupied) | Your income plus rent from other units | House hackers who will live in one unit | Owner-occupancy is required; three- and four-unit FHA needs self-sufficiency |
Business-purpose loans only: DSCR, hard money, bridge and other investor programs on this page are for non-owner-occupied investment properties, not for a home you or your family will live in.
See our DSCR loan, Nevada hard money, serial investor and real estate investor pages for program details.
Loans we place in Henderson
Conventional (as little as 3% down for eligible first-time buyers), FHA (3.5% down, 580+ score), VA (no down payment for eligible veterans with full entitlement), jumbo above the conforming limit, DSCR loans that qualify on rent, bank statement loans for self-employed borrowers, asset-based and 1099 loans, and rate-and-term or cash-out refinances. As a broker we compare wholesale lenders, more than 100 on complex files, instead of one bank's menu.
Buying in Henderson on savings, brokerage or retirement balances? See asset depletion loans in Nevada.
Henderson loan program menu
| Program | Qualifies on | Who it fits in Henderson | Learn more |
|---|---|---|---|
| Conventional | Credit, income, assets; 3% down for eligible first-time buyers | W-2 earners, move-up buyers, refinances up to $832,750 | Call (702) 766-3744 |
| FHA | Credit (580+ for 3.5% down), income, assets | First-time buyers, condo buyers and buyers rebuilding credit; base loan up to $541,287 | FHA loans |
| VA | Eligibility, income and residual income | Veterans, active duty and eligible surviving spouses; no loan limit with full entitlement | VA loans |
| Jumbo | Credit, income, larger reserves | Anthem, Seven Hills, MacDonald Ranch, Lake Las Vegas and other homes above the conforming line | Jumbo loans |
| First-time buyer and assistance | Program rules plus down payment help | Buyers who need help with down payment and closing costs | First-time home buyers |
| Bank statement | 12 or 24 months of deposits (varies by lender) | Self-employed owners, consultants and contractors | Bank statement loans |
| P&L | A profit-and-loss statement (varies by lender) | Business owners with a CPA-prepared or signed P&L | P&L loans |
| Asset depletion | Eligible liquid assets turned into monthly income | Retirees, Sun City Anthem buyers and asset-rich households with little documented income | Asset depletion loans |
| DSCR (business purpose) | The rental’s rent compared with its full payment | Investors, LLC buyers, long-term rentals | DSCR loans |
| Non-QM overview | Alternative documentation | Anyone whose tax returns understate income | Non-QM loans |
How a Henderson home loan works with iQRATE, step by step
| Step | What happens | Who does the work | Timing |
|---|---|---|---|
| 1. Strategy call | We learn your goal, income type, credit, the price range and the neighborhoods you are shopping | You and your broker | One conversation |
| 2. Full application and documents | You apply and upload the full document package up front | You, with our checklist | As soon as you are ready |
| 3. Loan Estimates | We price your file across lenders and send Loan Estimates, including a builder comparison if you are buying new | iQRATE | Within 3 business days of a full application (Regulation Z) |
| 4. Pre-approval | Your file is reviewed so your offer has a real approval behind it | iQRATE and the lender | Before you write offers |
| 5. Offer and contract | Your agent writes the offer; we confirm the terms work with your loan, including any seller credit | You, your agent and iQRATE | Your search timeline |
| 6. Appraisal, title and HOA | Appraisal ordered; title report checked for LIDs, SIDs and liens; HOA resale packages for every association | Lender, escrow and iQRATE | Right after the contract |
| 7. Underwriting and approval | The lender clears conditions from the package you already sent | Lender and iQRATE | Varies by file and program |
| 8. Closing Disclosure | You receive your final costs and terms | Lender | At least 3 business days before closing (Regulation Z) |
| 9. Signing, funding and recording | You sign with escrow; the loan funds and the deed records with the Clark County Recorder | Escrow, lender and Recorder | Closing day |
Sources: CFPB, 12 CFR 1026.19 (Loan Estimate and Closing Disclosure timing). Checked October 30, 2026.
Our goal for eligible full-documentation conventional, FHA and VA purchases is 17 calendar days from initial disclosures, under the terms of our 17-Day Closing Commitment; most of our loans close in under 30 days. Jumbo, non-QM and investor loans vary more with the program and the appraisal, so we give you a realistic date for your file.
Henderson mortgage document checklist
| Borrower type | Income documents | Assets and other |
|---|---|---|
| W-2 employee | Last 30 days of pay stubs; 2 years of W-2s | 2 months of bank statements; photo ID |
| Healthcare, hospitality and casino workers with shift pay or tips | Pay stubs and W-2s showing overtime, differentials or reported tips; usually a 2-year history | 2 months of bank statements |
| Retirees | Social Security and pension award letters; 1099-R forms; proof of continuance for retirement-account distributions | Recent statements for retirement and brokerage accounts (also used for asset depletion) |
| Relocating from California or another state | Pay stubs and W-2s, or an offer letter for a new Nevada job | Statements for sale proceeds or the listing agreement on the home you are selling |
| Jumbo borrowers | Full income documents, often with 2 years of tax returns | Statements showing reserves after closing; explanation of large deposits |
| Veterans and active duty | Leave and Earnings Statement or income documents; VA award letter if applicable | Certificate of Eligibility (we can request it); DD-214 for veterans |
| Self-employed (tax-return loan) | 2 years of personal and business tax returns | Business license or CPA letter; 2 months of statements |
| Self-employed (bank statement loan) | 12 or 24 months of business or personal bank statements | Business license or CPA letter |
| Investor (business purpose) | For DSCR: lease or rent schedule | Entity documents if buying in an LLC; statements on other properties |
Common Henderson loan problems and how we solve them
| Issue | Why it comes up in Henderson | What we do |
|---|---|---|
| Price lands just over the conforming line | 12.8% of listings ask $1.5 million or more, and many Anthem and Seven Hills homes sit near $832,750 | Show the down payment that keeps you conforming next to a jumbo quote |
| LID assessment pushes ratios over | Inspirada and some other neighborhoods carry improvement-district assessments | Pull the title report early and include the assessment in your payment from day one |
| Two layers of HOA dues | Master plans often have a master and a sub-association | Count every association; compare programs with higher ratio limits if needed |
| Builder incentive tied to the builder’s lender | Common in Cadence and other new-home areas | Price an outside loan the same day and compare the net cost, incentive included |
| Appraisal on a unique custom home | Guard-gated and hillside custom homes have fewer close comparables | Order early, give the appraiser upgrade lists, and plan a reconsideration if needed |
| Retirement income looks low on paper | Retirees often draw less than they could | Use asset depletion or documented distributions to show qualifying income |
| Buying before your California home sells | Many Henderson buyers relocate from California | Qualify with both payments, use a bridge structure, or plan a sale-and-rent-back |
| Condo project not approved | Some Lake Las Vegas and older condo projects do not meet FHA or VA rules | Check the project before you offer; use conventional or portfolio financing if needed |
| Address not in the city | Some Henderson mailing addresses are unincorporated Clark County | Confirm the jurisdiction for the tax rate and any rental plans |
Henderson borrower situations we see most
California relocators. Buyers moving from California often have significant equity in a home they have not sold yet. You can buy before you sell if you qualify with both payments, use a bridge loan secured by the California home, or sell first and arrange a rent-back. Nevada has no state income tax on wages, but your loan is still underwritten on your gross income, not your take-home pay. If you are changing jobs with the move, an offer letter for a Nevada position can sometimes be used before your first paycheck.
Retirees and Sun City Anthem buyers. Retirees often have large balances in retirement and brokerage accounts but modest monthly income on paper. Lenders can count Social Security, pensions and documented distributions, and an asset depletion program can turn eligible assets into qualifying income. Paying cash and taking a loan later is another approach some buyers use. Age is never a factor in approval.
Move-up and luxury buyers. Buyers moving from Green Valley to Anthem, Seven Hills or MacDonald Highlands usually need a jumbo or a large down payment. Jumbo lenders look closely at reserves after closing and at large recent deposits, so we review your statements before you apply.
Self-employed professionals. Business owners, physicians in private practice, contractors and consultants often show less income on their returns because of write-offs. David has prepared more than 6,000 tax returns, so we start by reading your return to see whether a standard loan still works before we move you to a bank statement or P&L loan.
New-construction buyers. In Cadence, Inspirada and Lake Las Vegas, builders often offer credits for using their lender. We compare the full cost of the builder’s offer with outside Loan Estimates and plan the rate lock around the build schedule.
Investors. Henderson’s HOA rules and the city’s short-term rental registration make long-term rentals the usual plan. DSCR and portfolio loans let investors buy in an LLC and grow without adding personal income documents for every property.
Written guarantees that apply in Henderson
Terms for each are on its own page; see all iQRATE guarantees.
- Rate Match: lock with us, and within 3 calendar days show a competitor's locked Loan Estimate for identical terms. We match it or pay you $1,000 after you close with them.
- Bare Bones Closing Costs: no processing, admin, doc-prep, lock or broker fees of our own; third-party fees at cost.
- 17-Day Closing Commitment: our goal for eligible conventional, FHA and VA purchases is 17 calendar days from initial disclosures. Most of our loans close in under 30 days.
- $5,000 Seller Guarantee and All Costs Covered: if a purchase backed by our verified approval fails solely because of our error, we pay the seller $5,000, and we reimburse you up to $1,000 of costs plus forfeited earnest money up to $5,000.
- 12-Month Rate Drop and Lifetime Rate Monitoring: if rates fall at least 0.50% within a year, typical lender fees on the refinance are covered through premium pricing (subject to lender availability), and we watch rates for you for life.
Best mortgage broker in Henderson NV with good reviews
iQRATE Mortgages (NMLS 1862492), led by broker David Ghazaryan (NMLS 1486726), holds 5.0 stars from 87 reviews on Experience.com and 5.0 stars from 77 Google reviews (October 2026), and shops Henderson purchase, jumbo and investor loans across 100+ wholesale lenders. Our office at 6360 S Rainbow Blvd in Las Vegas is about 15 minutes from Green Valley, and we close Henderson loans through local escrow companies.
"Best" depends on your loan, so here's how to check any Henderson broker, us included, before you apply:
- Look up the license. Search the company and the loan officer on NMLS Consumer Access and confirm a Nevada license with the Nevada Division of Mortgage Lending.
- Read reviews on more than one site. Look for reviews that mention your loan type (jumbo, VA, DSCR, self-employed) and how the lender handled problems, not just the star average.
- Ask how many lenders they can quote. A broker compares wholesale lenders on one application; a retail bank or builder's lender quotes only its own programs.
- Compare Loan Estimates, not quotes. Get official Loan Estimates the same day and compare the APR, lender fees and points line by line.
- Ask about Henderson specifics. A local broker should know how SID and LID assessments, HOA and condo project reviews, and Clark County transfer tax affect your cash to close.
See every review on our reviews page or David's Experience.com profile. Buying above the conforming limit? Start with Las Vegas jumbo loans. Buying a rental? See DSCR loans.
Get My Custom Rate Now · or call (702) 766-3744
Reviewed by David Ghazaryan, Mortgage Broker, NMLS 1486726 · iQRATE Mortgages, NMLS 1862492 · Updated October 31, 2026. Review counts are as of October 2026 and change over time. Not a commitment to lend; all loans subject to credit, income, property and lender approval. Equal Housing Opportunity.
How to choose a Henderson mortgage broker (2026 checklist)
Short answer: the right Henderson mortgage broker is licensed in Nevada and easy to verify, compares many lenders instead of one menu, puts your costs in writing on a Loan Estimate, and knows the things that are specific to Henderson: master-association and sub-association dues, the Local Improvement District assessments carried by some neighborhoods, builder incentives in Cadence and Inspirada, the jumbo line that a large share of Anthem, MacDonald Ranch and Lake Las Vegas homes cross, and the city’s short-term rental registration. Henderson is a higher-priced market than the rest of the valley, so the difference between a well-structured loan and a generic one is bigger here. Use this checklist on every broker you interview, including us.
| What to look for | Why it matters in Henderson | How to check it | iQRATE Mortgages |
|---|---|---|---|
| A Nevada license for the company and the loan officer | Only licensed brokers and loan originators may arrange Nevada home loans | Search both names on NMLS Consumer Access; Nevada brokers are supervised by the Division of Mortgage Lending | Company NMLS 1862492; David Ghazaryan NMLS 1486726 |
| Jumbo and high-balance experience | 12.8% of Henderson listings on September 15, 2026 asked $1.5 million or more, and MacDonald Ranch / Highlands closed at a $1,978,250 median | Ask how they document assets and reserves for loans above $832,750 and how many jumbo options they can quote | Full-doc, bank statement, asset-based and interest-only jumbo options across our lender network |
| New-construction know-how | 64% of Cadence’s closings in the last 12 months were homes built in 2025 or later | Ask how they compare a builder incentive with an outside loan, and how they handle a long build and rate-lock timeline | We price the builder’s offer against outside Loan Estimates so you can see the real trade-off |
| HOA and LID awareness | Inspirada carries a City of Henderson LID; most master plans have a master association and many have sub-associations | Ask when they pull the title report and HOA resale package | We pull title and HOA figures early so dues and assessments are in your ratios before you offer |
| Number of lenders compared | One lender has one set of rules; a broker can move a file when a lender says no | Ask how many lenders they actively send loans to, by program | More than 100 banks and private lenders, including non-QM and investor lenders |
| Written costs early | Loan Estimates are the only apples-to-apples way to compare | You should get a Loan Estimate within 3 business days of a full application (Regulation Z) | Loan Estimates on every application; costs itemized before you commit |
| Public, recent reviews | Reviews show how a broker handles problems, not just easy files | Read a third-party review site, not only quotes on the broker’s website | 5.0 stars from 87 reviews on Experience.com (October 2026) |
| A broker who will say no | Sometimes waiting, paying down a card or taking a builder’s offer is the better move | Ask them to compare their best quote with the builder’s or your bank’s | We show you the comparison, even when the answer is “take the other offer” |
Sources: NMLS Consumer Access (iQRATE Mortgages, 1862492); NMLS Consumer Access (David Ghazaryan, NMLS 1486726); Nevada Division of Mortgage Lending; CFPB, 12 CFR 1026.19 (Loan Estimate and Closing Disclosure timing); Nevada Real Estate Group, Henderson market report September 2026 (GLVAR MLS data; actives counted September 15, July 2026 closings settled); Nevada Real Estate Group, top-selling communities in Las Vegas and Henderson (MLS closings, 12 months ending September 18, 2026); Experience.com. Checked October 30, 2026.
A practical way to use the table: shortlist two or three brokers or lenders, give each the same information on the same day, and compare the Loan Estimates line by line. Look at section A (origination charges, including any points), section B (services you cannot shop for) and the total in section J. Prices move daily, so quotes collected on different days are not comparable. The CFPB’s CFPB, Loan Estimate explainer walks through each section in plain language.
Mortgage broker vs bank vs builder’s lender in Henderson
Henderson buyers usually choose among three kinds of loan sources. A mortgage broker such as iQRATE Mortgages does not lend its own money; we arrange your loan with a wholesale lender that funds it, and we can choose among many lenders for each file. A bank or credit union lends on its own guidelines and may offer relationship pricing to depositors. A builder’s affiliated lender is common in Cadence, Inspirada and other new-home neighborhoods, and builders often tie closing-cost credits or rate buydowns to using it. Any of the three can be the right answer; the point is to compare them on the same day with the same information.
| Question | Mortgage broker | Bank or credit union | Builder’s affiliated lender |
|---|---|---|---|
| Whose loan programs? | Many wholesale lenders | Its own | Its own, often with builder-funded incentives |
| If one lender declines | The broker can move your file to another lender | You usually start over elsewhere | You usually lose the incentive if you leave late |
| Jumbo above $832,750 | Several jumbo menus, including non-QM jumbo | Often available; relationship pricing for large depositors | Varies by builder and price point |
| Self-employed and 1099 income | Bank statement, P&L and 1099 programs available | Usually tax-return income only | Usually tax-return income only |
| Retirees with assets, not paychecks | Asset depletion and asset-based programs | Some offer asset-based programs | Varies |
| DSCR and investor loans | Broad access across lenders | Often limited | Rarely; most builder programs are for owner-occupants |
| Long new-construction timelines | Extended locks available from some lenders (cost varies) | Varies | Builder may cover extended locks as part of an incentive |
| How the loan officer is paid | By the lender or by you, never both on one loan (Regulation Z) | Salary and/or commission | Salary and/or commission |
Sources: CFPB, 12 CFR 1026.36 (loan originator compensation); Nevada Division of Mortgage Lending. Checked October 30, 2026.
Federal rules limit how loan originators are paid. Under Regulation Z, a broker’s compensation cannot be based on your interest rate or other loan terms, and a broker cannot be paid by both you and the lender on the same loan. That keeps the comparison simple: look at your total cost on each Loan Estimate, then subtract any incentive you would actually lose by going elsewhere.
When is a bank or builder’s lender the better choice in Henderson? When a builder’s incentive is larger than any price difference you can find outside, when your bank offers a relationship discount on a large jumbo, or when a portfolio lender will keep an unusual property on its books. When is a broker the better choice? When your income comes from your own business, investments or retirement accounts, when you are buying a rental or buying in an LLC, when you need a jumbo with less than 20% down, when you are relocating from California and need to buy before you sell, or when one lender has already said no.
Questions to ask any Henderson mortgage broker before you apply
- What is your NMLS number, and the company’s? Look both up on NMLS Consumer Access before you send documents.
- Is my pre-approval underwritten, or just a pre-qualification? Henderson homes that closed in July 2026 sat a median 38 days, so you have more time than in North Las Vegas, but sellers still compare the strength of each buyer’s file.
- Where is the jumbo line for my down payment? With 10% down, any price above about $925,000 makes the loan jumbo; with 20% down the line is about $1,040,000. The answer changes reserves, documentation and pricing.
- Does this parcel carry an LID or SID? Inspirada is in the City of Henderson’s LID T-18; other neighborhoods have their own districts or none. Assessments count in your monthly payment.
- What are the master and sub-association dues? Anthem, Seven Hills, Green Valley Ranch and the new master plans often have two layers of dues. Ask for the resale package numbers, not the listing field.
- How do you compare a builder incentive? Ask for the builder’s Loan Estimate and an outside one on the same day.
- What happens if the appraisal comes in low? Ask how they handle a reconsideration of value and whether another program or a larger down payment fits.
- Which commitments do you put in writing? Get the terms of any guarantee before you sign anything.
Who you work with: David Ghazaryan, NMLS 1486726
David Ghazaryan is the owner and broker of iQRATE Mortgages (NMLS 1862492), based at 6360 S Rainbow Blvd, Suite 101, in Las Vegas, about 15 minutes from Green Valley. He entered the mortgage industry in 2005 and founded a tax practice in 2008, where he has prepared more than 6,000 tax returns. That background matters on Henderson files: business owners and professionals with complex returns, retirees living on distributions and investment income, California transplants with a home still to sell, and real estate investors with several properties often have income that a quick automated review misreads. Reading a return the way a tax preparer does is how we find the program that fits. David is also a real estate investor, so rental files get looked at the way an owner looks at them: rent, taxes, insurance, HOA dues and any LID first, then the loan.
Our network includes more than 100 banks and private lenders, which lets us place conventional, FHA, VA, jumbo, DSCR, bank statement, asset depletion, hard money and portfolio loans from one office. Clients rate David 5.0 stars from 87 reviews on Experience.com (October 2026). See David’s profile, read client reviews, verify his license on NMLS Consumer Access (David Ghazaryan, NMLS 1486726), or start an application. Call (702) 766-3744.
Real Henderson loan stories from my desk
No names, no addresses. Just what happened, and how the loan got done.
Real client scenario: a 91% refinance in seven days
One week. Start to finish.
The stakes: In winter 2024 a Henderson homeowner wanted a rate-and-term refinance with very little equity, about 93% loan-to-value.
Where it almost fell apart: At that loan-to-value there is almost no room for a surprise. A low appraisal could have stopped it.
The turn: The appraisal came in about $20,000 above the estimate. That pulled the loan-to-value down to about 91%.
The payoff: The loan went from submission to closing in one week.
Real client scenario: selling, buying and keeping the payment comfortable
They had a number. They would not go over it.
The stakes: A couple was listing their home and capped their next purchase at about $400,000 so the payment stayed comfortable.
Where it almost fell apart: Two moves at once means two sets of deadlines, and both jobs had to be verified in writing.
The turn: We set up a temporary 2-1 buydown and gathered full written job verifications for both of them.
The payoff: A purchase of about $320,000 in Henderson closed in winter 2022, under their cap.
Real client scenario: a condo with 30% down
A big down payment. A small loan.
The stakes: In 2018 a buyer wanted a Henderson condo priced around $165,000.
Where it almost fell apart: The seller was a company, not a person, which adds paperwork.
The turn: The buyer put 30% down, for a loan of about $115,000.
The payoff: The purchase closed, and the same client came back the next year for another loan. This loan closed while I was a loan officer at a prior company, before iQRATE.
Real client scenario: jumbo-size loans across Southern Nevada
Big loans. Same care.
The stakes: From 2020 through 2023 we closed 15 loans at or above about $725,000, above the conforming limit in each of those years.
Where it almost fell apart: Loans this size get extra review, and every number has to hold up.
The turn: 13 of the 15 were in Southern Nevada, including a refinance of about $1.5 million in Henderson.
The payoff: Every one of the 15 closed. See our jumbo loan page for how it works.
Want to see how your file would play out? Call (702) 766-3744 or contact us to get a quote.
Equal Housing Opportunity. iQRATE Mortgages LLC NMLS 1862492; David Ghazaryan NMLS 1486726. All loans subject to credit approval. Past results do not guarantee future outcomes.
Henderson in plain numbers
Here is the Henderson market in six charts. Each one answers a buying question. The sources are under each chart.
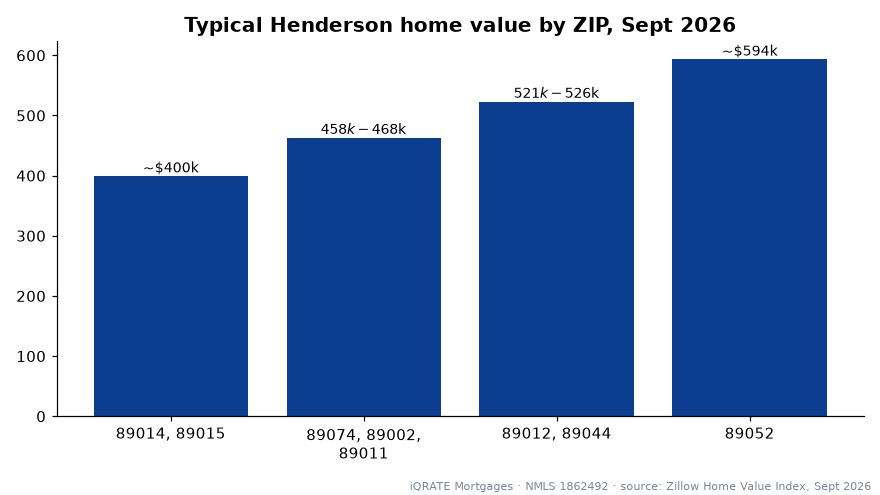
Start with the ZIP, not the city. 89014 and 89015 sit near $400,000. 89052 sits near $594,000. Values in every ZIP were 1.2% to 3.3% lower than a year earlier.


Homes take longer to sell here than in North Las Vegas. In July 2026, 60.5% of Henderson sales closed below list. That gives you room to ask for seller credits.
Want to know what to offer on a Henderson home?
Call or text (702) 766-3744, send us a question, or start an application. No cost to ask.

Shopping in Anthem, MacDonald Highlands or Lake Las Vegas? Check this line first. Read our jumbo loan guide if your price sits above it.
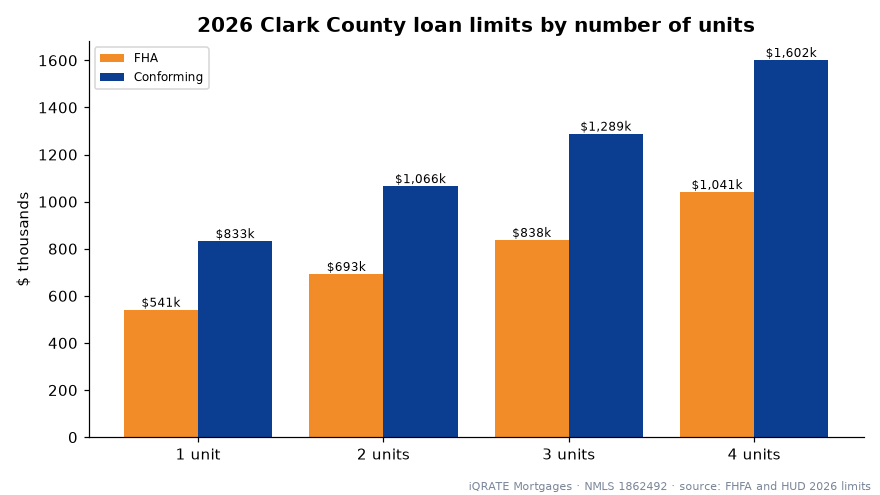
Buying a duplex or fourplex to live in? You can use an FHA loan with a much higher limit.

Quick answers for Henderson buyers
Is Henderson cheaper than it looks?
Sometimes. The tax rate is lower than North Las Vegas. But SID, LID and HOA fees can add to your payment. Lenders count all of them.
Should I buy a condo or a house?
A condo costs about $195,000 less at the median. But the lender must review the condo project. Ask us early so the review does not slow your closing.
I am a veteran. What should I use?
Look at a VA loan. It can mean no down payment. Veterans with VA disability pay generally skip the funding fee.
I own a business. Can I still qualify?
Yes. See our self-employed mortgage guide or the bank statement loan if your tax returns show low income.
I want a rental in Henderson. Where do I start?
Start with the rent. Our DSCR loan page explains how rent qualifies the loan. Short-term rentals need a city registration first.
Is this my first home?
Read the first-time buyer guide. It covers Home Is Possible help and FHA. Then compare with North Las Vegas prices.
Ready to see your Henderson numbers?
Call or text (702) 766-3744, send us a question, or start an application. No cost to ask.
What clients say about iQRATE Mortgages
Real reviews from our Google profile, quoted word for word. They describe our company overall, not this specific loan or city.
★★★★★ 5 out of 5
“I am so thankful to David and his staff for helping us through our home buying process. His team was so knowledgeable and incredibly friendly. This was our first time purchasing a home and we felt extremely comfortable that we were getting the best loan at the best rate. If you are looking to buy I home I highly recommend you get your loan from David and his team. They are there with any questions or concerns you may have and they treated us so well. I cannot express my gratitude for everyone on his team helping us buy our first home!!”
— Elizabeth H., review on Google
Read all of our reviews on Google · Call or text (702) 766-3744
More client reviews from Google, Yelp and Zillow
Real 5-star reviews, quoted word for word, with the reviewer’s first name and last initial. A screenshot of each review sits above its quote. They describe working with David Ghazaryan and the iQRATE team overall, not a promise about your loan.

“I highly reccomend David. He treated my loan process in the same manner as he would of had if it's his own. David walked me through the process from the beginning to the end. He was always available when i called, even on weekends and holidays, especially when he had a family tragedy he still made my loan a priority and finished it on time as promised.”
— Yelena M. (Henderson, NV), 5-star review on Zillow

“We are very thankful for the excellent and extremely fast help from David Ghazaryan! As first-time home buyers we couldn't imagine a better experience. We love our new Green Valley home and recommend David Ghazaryan and his team to everyone who is looking to buy a house.”
— Olena P., 5-star review on Google
Our ratings: Google 5.0 from 77 reviews. Yelp 5.0 from 51 reviews. Zillow 5.00 from 9 reviews. Questions? Call or text (702) 766-3744.
Read our Google reviews. Read our Yelp reviews. Read our Zillow reviews.Real Henderson files from David's desk
These are real loans David Ghazaryan and the iQRATE team worked, told in David's words. Client names, addresses and other identifying details are left out, and some prices are rounded to protect client privacy.
The Anthem Highlands Buyer Who Had Two W-2s but Only One Job
Anthem Highlands · about $725K purchase · Conventional loan · 21-day closing
I had a buyer who had worked for the same healthcare organization for eleven years. Excellent credit, strong income, 20% down. Nothing about the file suggested a difficult loan. Then underwriting questioned his employment history. He had received two W-2s in the same year, each from a different company. His latest pay stub showed only seven months of year-to-date earnings. The lender thought he had changed jobs and that we couldn't establish enough history for his overtime income. But he hadn't changed jobs at all.
His employer had reorganized its payroll under a different legal entity. Same building, same supervisor, same position. Even his employee identification number was unchanged. The unusual part was that his final paycheck under the old entity and first paycheck under the new entity fell within the same pay period. I reconstructed his earnings using both W-2s, the payroll transition records, and confirmation from the employer. We demonstrated continuous employment and separated the earnings periods so nothing was counted twice. The lender accepted the corrected documentation, and we closed in 21 days. Sometimes the hardest part of a mortgage is proving something that never actually changed.
The Inspirada Buyer Who Thought Her Tax Bill Was a Scam
Inspirada · about $650K purchase · Conventional financing
I had a buyer in Inspirada who nearly refused to approve her closing paperwork over a bill mailed to Los Angeles. She saw a Local Improvement District assessment with a California payment address and thought somebody was trying to defraud her. I understood why she questioned it. She was a former banking fraud investigator, and she couldn't believe a Henderson property assessment would have a Los Angeles payment address. But Henderson's assessment billing arrangement can legitimately use a Los Angeles mailing address. The larger problem emerged when we reviewed the numbers.
The property had a separate semiannual improvement-district assessment of approximately $1,080. That was another $180 per month in housing expense that hadn't been included in the original qualification. We were already close to the lender's debt-to-income limit. We documented the assessment, obtained confirmation directly through the authorized servicing channel, and revised the financial analysis. The buyer also had a small vehicle loan she had planned to pay off after closing. By completing that payoff earlier and documenting it properly, we reduced her monthly liabilities enough to preserve approval. She kept the house she wanted. What almost killed the loan wasn't the purchase price. It was a government assessment that arrived in a suspicious-looking envelope.
The MacDonald Highlands Jumbo Funded by Four Vintage Guitars
MacDonald Highlands · about $2.9 million purchase · Jumbo loan · 28-day closing
One of my more unusual jumbo files involved a buyer whose down payment included proceeds from selling four vintage electric guitars. Not ordinary guitars. Rare instruments he had collected for decades, including a left-handed model that attracted serious collectors. He sold them through a specialty auction house and received approximately $318,000. The problem was the deposit. The bank statement showed one large incoming wire from an auction company, with a reference number that didn't identify what he had sold. The lender couldn't establish the source of the funds.
The client was frustrated. In his mind, he had sold property he owned, paid the auction commission, and put his money in the bank. But the lender needed a documented chain. We assembled the consignment agreement, individual auction-lot settlement statements, proof of ownership, commission breakdown, and wire confirmation. Then we traced the funds directly into the account used for closing. The documentation established the source of funds, and the loan closed in 28 days. A nearly $3 million purchase almost came down to proving ownership of four guitars.
A Henderson Condo Bought With 30% Down, and a Client Who Came Back
Henderson · about $165K purchase · Conventional, 30% down
A real closed file, de-identified. In 2018 a buyer purchased a Henderson condo for roughly $165,000 from a seller that was an LLC, with a loan of roughly $115,000, putting about 30% down.
The same client came back in 2019 for another loan. This file closed while David was the loan officer at a prior company, before iQRATE.
A larger down payment on a condo can widen your lender choices; we check the condo project before you write an offer.
The Henderson Rental That Included a Jukebox Workshop
Near Water Street District · about $475K purchase · DSCR financing
An investor brought me a property that looked attractive on paper. It was a single-family home with a detached workshop. The house could rent for approximately $2,850 monthly. The workshop had a separate arrangement with a man who restored antique jukeboxes. He paid another $550 a month to use the space. The investor calculated total rental revenue of $3,400. But the proposed DSCR lender wouldn't count the workshop's separate rental income as qualifying residential rent.
The difference was substantial.
Rent and payment, before and after: the investor counted $3,400 a month in rent against a $3,050 payment, which he read as a 1.11 DSCR. The lender counted only the house's verified $2,850. After we reduced leverage and revised pricing, the payment came down to $2,540, for a DSCR of 1.12.
Using only the house's $2,850 rent against the original $3,050 payment would have produced a DSCR of approximately 0.93. Instead of trying to persuade the lender that jukebox restoration was residential rental income, we changed the financing structure. We reduced leverage, revised pricing, and made the loan work using the home's supportable residential rent alone. The workshop could still produce additional revenue, but the financing didn't depend on that revenue being accepted. The unusual thing about that deal was that the investor wasn't wrong about the cash flow. He was wrong about which cash flow the lender would recognize.
What I Tell Henderson Buyers That Other Lenders May Overlook
I tell buyers not to assume everything attached to the property appears in the mortgage payment. One Henderson home had an electricity bill that was practically zero because the seller had prepaid a long-term solar arrangement. The buyer thought that meant the solar equipment was owned outright. It wasn't. The panels belonged to a third party, and a precautionary UCC financing statement appeared in the property's records.
We had to establish the actual solar agreement, transfer requirements, and the lender's title and underwriting treatment. It was a small detail with the potential to complicate an otherwise ordinary closing. I also make buyers review improvement-district assessments, the actual HOA structure, and Nevada's property-tax abatement classification. A monthly payment estimate is only useful if it includes the obligations the buyer will actually inherit.
Every loan is subject to credit approval, underwriting and property eligibility; this is not a commitment to lend. Call (702) 766-3744 to talk through your file. iQRATE Mortgages LLC, NMLS 1862492. David Ghazaryan, NMLS 1486726. Equal Housing Opportunity.
Henderson mortgage FAQs
What is the 2026 FHA loan limit in Henderson NV?
$541,287 for a one-unit home, the Clark County limit. The 2026 conforming limit is $832,750.
What is the property tax rate in Henderson NV?
About $2.9613 per $100 of assessed value for FY 2026–27, and assessed value is 35% of taxable value. Newer areas can add SID or LID assessments on top.
What is a SID or LID in Henderson?
A special or local improvement district assessment that pays for infrastructure in some neighborhoods, such as Inspirada's LID T-18 (Cadence has none, per its developer). It's billed separately, adds to your monthly payment, and lenders count it in your debt-to-income ratio.
Can I run a short-term rental in Henderson?
Only with an annual city registration, at least 1,000 feet from another registered rental and 2,500 feet from a resort hotel, plus 13% transient lodging tax. Homes in an HOA qualify only if the documents expressly allow it.
Should I use the builder's lender in Henderson?
Compare first. Builder incentives often require their lender, but an outside quote backed by our Rate Match Guarantee may beat it. We line up both offers so you see the total cost.
How much are closing costs in Henderson?
For iQRATE clients, about $6,000 to $8,000 on full-documentation loans and about $15,000 on some non-QM loans. Prepaids, such as insurance and the tax escrow deposit, are added to cash to close but aren't closing costs.
Who pays the transfer tax in Henderson?
By local custom the seller pays Clark County's $2.55 per $500 transfer tax, but the purchase contract decides.
How fast can iQRATE close a Henderson purchase?
Most of our loans close in under 30 days. Eligible full-doc conventional, FHA and VA purchases target 17 calendar days from initial disclosures.
Is iQRATE a local Henderson lender?
We're a Southern Nevada brokerage based at 6360 S Rainbow Blvd in Las Vegas, about 15 minutes from Green Valley. We close Henderson loans through local escrow companies.
Is my Henderson loan conforming or jumbo? Tables and calculators
Short answer: a Henderson loan is a jumbo when it is bigger than the Clark County limit. For 2026 that limit is $832,750 for a one-unit home. The tables and tools below show where that line falls for your price and down payment.
At what home price does a one-unit Henderson loan become a jumbo?
This is simple math. The loan is the price minus the down payment. Prices are rounded to the nearest dollar.
| Down payment | Highest price for a conforming loan | Cash for the down payment at that price |
|---|---|---|
| 5% | $876,579 | $43,829 |
| 10% | $925,278 | $92,528 |
| 20% | $1,040,938 | $208,188 |
| 25% | $1,110,333 | $277,583 |
Which loan fits which Henderson borrower?
| Loan type | Usually fits | Learn more |
|---|---|---|
| Conforming | Loans at or below $832,750 with W-2 or tax-return income | Nevada mortgage broker |
| FHA | Buyers with a smaller down payment or a lower credit score | FHA loans |
| VA | Eligible service members and veterans, including Nellis families | VA loans |
| Jumbo | Loans above the Clark County limit, common in MacDonald Highlands, Ascaya and Lake Las Vegas | Jumbo loans |
| Bank statement or P&L | Self-employed borrowers whose tax returns show low income | Bank statement loans |
| Asset depletion | Retirees and others who qualify on savings, not paychecks | Asset depletion loans |
| DSCR | Investors who qualify on a rental's income (business purpose only) | DSCR loans |
| Portfolio and blanket | Investors who finance several rentals at once | Blanket loans |
Is my Henderson loan above the conforming limit?
Result: enter both numbers
What is the rental's DSCR with a special assessment?
DSCR is the monthly rent divided by the full monthly payment. Many newer Henderson areas, like Inspirada and Cadence, carry a special or local improvement district bill. Add it here. Lenders set their own minimums.
Result: enter rent and payment
What is the debt-to-income ratio?
Result: enter both numbers
These tools do simple math only. They do not use interest rates, quote a payment or approve a loan. Each lender sets its own rules. DSCR loans are for business-purpose investment property only.
Sources: FHFA, conforming loan limits; CFPB, debt-to-income ratio; City of Henderson.
Nearby cities and programs we also serve
- Las Vegas mortgage broker
- Summerlin mortgage broker
- North Las Vegas mortgage broker
- Boulder City mortgage broker
- Mesquite mortgage broker
- Pahrump mortgage broker
- Reno mortgage broker
- BRRRR loans in Las Vegas
- Portfolio loans
- No-ratio DSCR loans
- Foreign national DSCR loans
- Refinance
- Closing costs by state
- P&L loans
How do I start a Henderson loan with iQRATE?
Call or text David Ghazaryan (NMLS 1486726) at (702) 766-3744. Tell him the price range, the neighborhood and how you earn your income. When you are ready, apply now or contact us to set a time to talk.
iQRATE Mortgages, NMLS 1862492. Equal Housing Opportunity.
Which other iQRATE guides help Henderson buyers and owners?
These Nevada guides go deeper on topics this page touches. Pick the question closest to your situation.
Which guides help you buy a Henderson home with FHA, conventional or down payment help?
- Are Mortgage Points a Waste of Money in Nevada?
- Nevada Closing Costs 2026: How Much & How to Cut Them.
- Bypass Mortgage Seasoning Rules in Las Vegas & Reno.
- Can a Non-Relative Gift My Down Payment in Nevada?
- Cover FHA Closing Costs With Seller Credits in Nevada.
- Covering an FHA Appraisal Gap in Nevada Without Cash.
- Deed-in-Lieu and Your Next Mortgage in Nevada.
- DPA vs Seller Credits for a Las Vegas, Nevada Home Loan.
- FHA 203k Renovation Loans in Reno and Sparks, Nevada.
- FHA Credits vs. Conventional Gifts for Nevada Homebuyers.
- FHA or Conventional Loan in Las Vegas for Future Buying?
- FHA or Conventional with DPA in Las Vegas & Henderson?
- FHA Repair Checklist for Reno & Carson City, Nevada Homes.
- FHA vs 5% Conventional Loan in Nevada: Which Builds Equity Faster?
- FHA vs Conventional Appraisal for Older Nevada Homes.
- FHA vs Conventional for Wealth Building in Nevada.
- FHA vs Conventional in Las Vegas: Which Insurance Is Cheaper?
- FHA vs Conventional in Las Vegas: Which Needs Less Cash?
- FHA vs Conventional in Nevada: A 10-Year Wealth Plan.
- FHA vs. Conventional in Nevada: A Long-Term Wealth Guide.
- FHA vs Conventional Loan for a Henderson, Nevada Home?
- FHA vs Conventional Loan in Nevada: A Total Cost Guide.
- FHA vs Conventional Loan Las Vegas: 10-Year Cost Comparison.
- FHA vs Conventional Loans in Nevada: A 5-Year Cost Guide.
- FHA vs Conventional Loans in Nevada: Which Has Hidden Traps?
- FHA vs Conventional PMI in Nevada: Avoiding the Cost Trap.
- First Time Homebuyer in Las Vegas.
- How Much Cash Do You Need to Close on a Nevada Home?
- How to Get a Seller to Pay FHA Costs in Nevada.
- How to Prove Your Henderson Financed Offer is a Sure Thing.
- How to Rescue a Failing Escrow in Las Vegas, Nevada.
- How to Use a Gift of Equity in Nevada for a Mortgage.
- How Your Mortgage Escrow Account Works in Nevada.
- Las Vegas DPA: A Good Deal or a Costly Trap for Buyers?
- Las Vegas Lender Credits vs Seller Credits: Which is Better?
- Making Your Financed Offer Win in Las Vegas, Nevada.
- Mortgage Points vs Rate Buydown in Las Vegas, Nevada.
- Nevada DPA: Grant vs Forgivable Loan for Homebuyers.
- Nevada Non-Recurring Closing Costs Explained for Homebuyers.
- Nevada SID & LID Fees: What Las Vegas Buyers Must Know.
- Passing an FHA Appraisal on a Nevada Fixer-Upper.
- Rate Buydown or More Down in Nevada: Which Saves More?
- Real Risks of a Co-Signed Mortgage in Nevada.
- SAVE Plan & Your Nevada FHA Loan: Will You Get Approved?
- Unmarried Homebuyers Guide for Nevada.
- Using a 401k Loan for a Down Payment in Nevada.
- Using a Power of Attorney for a Nevada Mortgage Closing.
- Using an Energy Efficient Mortgage in Nevada Explained.
- Using Lender Credits on a Nevada Mortgage.
- Using Seller Credits in Las Vegas to Win Your Offer.
- Waive a Loan Contingency in Nevada: A Cash Offer Guide.
- What Is the Buyer Power Index in Las Vegas, Nevada?
- When to Lock a Mortgage Rate in Las Vegas, Nevada.
- Why Did My Nevada Mortgage Payment Go Up? Escrow Explained.
- Why Las Vegas, Nevada Homeowners Insurance Is So High.
- Why Your Las Vegas Mortgage Payment Increased.
- Your CPA Mortgage Guide for Las Vegas & Henderson Homebuyers.
- Nevada Down Payment Help: Grant or Forgivable Loan?
How do you fix credit or debt issues before you apply?
- 720 Credit Score But Low Cash in Nevada: FHA vs Conventional.
- A Letter of Explanation Can Save Your Las Vegas Mortgage.
- Authorized User Accounts & Your Nevada Mortgage Approval.
- Can a Lender Revoke a Mortgage Commitment in Nevada?
- Can Manual Underwriting Save Your Las Vegas FHA Loan App?
- Credit Dispute Halting Your Las Vegas, Nevada Mortgage?
- Credit Mistakes That Kill a Mortgage in Las Vegas, Nevada.
- FHA Loan Denied in Las Vegas? A Manual Underwrite Can Help.
- FHA vs Conventional Loan in Nevada with a 620 Credit Score.
- FHA vs Conventional Loan with a 600 Score in Nevada.
- FHA vs Conventional Loan with Good Credit in Nevada.
- Fix a Credit Error During Your Las Vegas Mortgage Escrow.
- Fix Credit Report Errors During a Las Vegas Escrow.
- Get a Las Vegas Mortgage With No Credit Score in Nevada.
- Get a Mortgage in Henderson & Reno with a Thin Credit File.
- Good Credit But Denied a Las Vegas, Nevada Mortgage? Why.
- How Co-Borrower Debt Can Block Your Henderson Home Loan.
- How Payment Shock Can Derail Your Nevada Mortgage Loan.
- How to Buy a Nevada Home With Limited Credit History.
- Las Vegas FHA Loan Denied With a 600 Score? Here's Why.
- Loan Denied After Clear to Close in Nevada? Here's Why.
- Low Credit Score? How to Buy a Home in Reno & Las Vegas.
- Medical Debt and Your 2026 Nevada Mortgage Approval.
- Mortgage Shopping in Las Vegas: Will It Hurt Your Credit?
- Nevada: FHA or Conventional With 5% Down & a 640 Score?
- Nevada Mortgage Guide for Thin Credit Files.
- New Collection in Escrow in Nevada? How to Save Your Loan.
- Old vs. New Debt: What Hurts a Las Vegas Mortgage Most?
- Parent's Credit Wrecked My Las Vegas Mortgage? Here's a Fix.
- Protect Your Credit Score During Escrow in Las Vegas, Nevada.
- Rapid Rescore Guide for Mortgages in Nevada.
- VA Loan With Low Credit in Las Vegas? It's Possible.
- Why Credit Disputes Halt FHA Loans in Las Vegas, Nevada.
- Why FHA Condo Loans Are Denied in Las Vegas, Nevada.
- Why Your FHA Loan Was Denied in Nevada With a 620 Score.
- Why Your Mortgage Score in Nevada Is Lower Than You Think.
- Why Your Nevada FHA Condo Loan Request Was Denied.
- Will Paying Collections Hurt My Las Vegas Mortgage Score?
- Why Banks Reject Your Las Vegas Condo Hotel Loan.
How do self-employed, commission and other non-salary buyers prove income?
- A Nevada S-Corp Guide to Mortgage Qualification.
- Bank Statements vs. Tax Returns for a Las Vegas Mortgage.
- Get a Las Vegas Mortgage After a Bad Business Year.
- Get a Nevada Mortgage with a Business Loss.
- Getting a Mortgage in Nevada with Cannabis Income.
- How Lenders Average 1099 Income in Las Vegas & Reno.
- How Lenders Calculate Gig Worker Income in Nevada.
- How Lenders Combine 1099 Incomes in Las Vegas & Reno.
- How Lenders Verify Tip Income for a Mortgage in Nevada.
- How Nevada Lenders Calculate Overtime & Bonus Income.
- How to Get a Las Vegas Mortgage After Quitting Your W-2 Job.
- How to Get a Mortgage on a Tax Extension in Nevada.
- How to Get a Mortgage with Commission Income in Las Vegas.
- Las Vegas Mortgage for New Businesses: How Soon Can You Buy?
- Nevada 1099 Mortgage Guide for Gig Worker Income.
- Nevada Business Taxes and Your Home Mortgage Qualification.
- Nevada Mortgage After Business Change: A Self-Employed Guide.
- Prep S-Corp Taxes for Las Vegas Jumbo Loan Approval.
- Prep Your Las Vegas & Reno Business for a Mortgage.
- Qualify for a Las Vegas Mortgage as an S-Corp Owner.
- Qualify for a Mortgage in Nevada on Commission Pay.
- Qualifying for a Nevada Mortgage With a Spousal Salary.
- S-Corp Mortgage Guide for Business Owners in Nevada.
- S-Corp Mortgage in Nevada: Get Approved After a Business Change.
- S-Corp Switch & Your Nevada Mortgage: How to Get Approved.
- Using S-Corp Income for a Mortgage in Nevada.
- VA Loan for Nevada Veterans with a New Business.
- When to Apply for a Self-Employed Mortgage in Nevada.
What about jumbo, new construction, condos, trusts, VA and other special cases?
- A Guide to Buying a Las Vegas Home Anonymously.
- A Guide to De-Risking New Construction Loans in Nevada.
- Best Loan for a Multi-Gen Home in Las Vegas, Nevada.
- Buy a Las Vegas Home Before You Sell Your Current One.
- Buying a Home from a Trust in Las Vegas: A Guide.
- FHA vs. Conventional Loan for a Las Vegas Condo.
- Foreign National Jumbo Loans in Nevada: A Guide.
- Get a Mortgage on a Home in a Trust in Nevada.
- How to Read Nevada HOA Docs for a Condo Loan.
- Jumbo Loans for a Home in a Trust in Las Vegas, Nevada.
- Jumbo vs. High-Balance Loans in Nevada: Which Is Best?
- Jumbo vs Piggyback Loan in Las Vegas & Henderson Nevada.
- Nevada Foreign National Loan: Documents You Need.
- Nevada ITIN vs. Foreign National Loan: A Direct Comparison.
- One-Time Close Construction Loans in Nevada Explained.
- Qualify for a Las Vegas Jumbo Loan With No W-2s.
- Restore VA Loan Entitlement After Divorce in Las Vegas.
- Using a Construction Loan to Build a Home in Nevada.
- Using a VA Loan to Buy a Las Vegas Condo in Nevada.
- Using Foreign Funds for a Nevada Mortgage: A Guide.
- VA Condo Approval in Las Vegas and Henderson Nevada.
- What Is a Seller Bridge Solution in Las Vegas, Nevada?
- What to Do After a Failed VA Appraisal in Nevada.
Which guides cover DSCR, rental and other investor loans in Nevada?
- Your 2025 Guide to Nevada DSCR Investor Loans.
- A DSCR Loan for a Las Vegas Non-Warrantable Condo Guide.
- A Foreign Buyer's Guide to Nevada Rental Property Loans.
- A Guide to Las Vegas & Reno Rental Portfolio Blanket Loans.
- Best Loan to Buy a Reno BRRRR Property in Nevada.
- Best Property Type for a DSCR Loan in Nevada.
- Beyond 10 Mortgages in Nevada: A Guide for Investors.
- Buy a Las Vegas Rental After Foreclosure Sooner Than You Think.
- Buying a Las Vegas Rental with an ITIN Investor Loan.
- California Investors Buying Las Vegas Rentals With a DSCR Loan.
- Can DSCR Loans Use Casita Rent in Las Vegas, Nevada?
- Clark County Property Tax and Transfer Tax on a Las Vegas DSCR Rental.
- DSCR Loan Calculation for Las Vegas & Reno Investors.
- DSCR Loan for a Las Vegas House-Hack: A Smart Guide.
- DSCR Loan Guide for Fixer-Upper Rentals in Nevada.
- DSCR Loan Guide for Mid-Term Rentals in Nevada.
- DSCR Loan in Las Vegas & Henderson with No Lease.
- DSCR Loan Reserve Rules in Las Vegas, Nevada Explained.
- DSCR Loan Reserves in Las Vegas, Nevada: A Guide for Investors.
- DSCR Loans and High HOAs in Las Vegas and Henderson.
- DSCR Loans and HOA Rules in Nevada: A Lender's Guide.
- DSCR Loans: Finance a Las Vegas Condo-Hotel Unit.
- DSCR Loans for Las Vegas Condo-Hotels: Your Guide.
- DSCR Loans for Las Vegas Short-Term Rentals Explained.
- DSCR Loans for New Construction Rentals in Las Vegas.
- DSCR Loans for Vacant Rentals in Reno & Las Vegas.
- DSCR vs. Blanket Loans: A Guide for Nevada Investors.
- FHA 90-Day Flip Rule Blocking Your Nevada Home Loan?
- Nevada FHA Multi-Family Loan: Use Future Rent to Qualify.
- Finance 5+ Nevada Rentals with One Blanket Mortgage Loan.
- Financing 5+ Unit Rentals in Las Vegas, Nevada: A Guide.
- Financing a Las Vegas Condo-Hotel with a DSCR Loan.
- Financing a Nevada Fix-and-Flip: A Complete Guide.
- Financing Past 10 Mortgages in Las Vegas, Nevada.
- Financing Your 11th Rental in Reno and Sparks, Nevada.
- Get a DSCR Loan in Nevada With No Rent Roll.
- Guide to DSCR Renovation Loans in Las Vegas Nevada.
- Henderson and North Las Vegas DSCR Loans for Single-Family Rentals.
- How Appraisers Calculate Rent for a Las Vegas DSCR Loan.
- How Lenders Project Rent for Las Vegas DSCR Loans.
- How to Buy More Rentals in Nevada With a Portfolio Loan.
- How to Stress-Test a DSCR Loan in Nevada.
- How to Use AirDNA for a DSCR Loan in Nevada in 2025.
- Investor Loan in Las Vegas Nevada After Bankruptcy: A Guide.
- Las Vegas Duplex, Triplex and Fourplex DSCR Loans: How 2-4 Unit Deals Qualify.
- Las Vegas Short-Term Rental DSCR Loans: Check the City Rules Before You Buy (2026).
- Loan Options After 10 Properties in Las Vegas & Reno Nevada.
- Nevada BRRRR: Bypass Seasoning with a DSCR Loan.
- Nevada DSCR Loan Guide for LLCs with Partners.
- Nevada DSCR Loans for Reno & Las Vegas Gig Workers.
- Nevada DSCR vs. Conventional Loan: Which Is Better?
- Nevada FHA Self-Sufficiency Test for Multi-Family Homes.
- Nevada Foreign Investor Portfolio Loan: Reno & Las Vegas.
- Nevada Portfolio Loans for Foreign Investors Guide.
- Nevada Portfolio Loans for Your Rental Properties.
- Nevada Rentals: Blanket Loan vs. Multiple Investor Loans.
- Portfolio Loan Risks in Reno and Carson City, Nevada.
- Portfolio Loans for Las Vegas BRRRR Real Estate Investing.
- Portfolio Loans for Nevada Rentals: A Las Vegas Guide.
- Portfolio vs DSCR Loans in Nevada for Rental Growth.
- Qualify for a DSCR Loan with Casita Rent in Las Vegas.
- Simplify Reno & Las Vegas Rentals with One Portfolio Loan.
- Use Rental History for a Las Vegas Mortgage in Nevada.
- Use Your Portfolio for a Nevada Jumbo Loan in 2026.
- Using a DSCR Loan for a Seasonal Las Vegas Rental.
- Using Casita Income for a Nevada DSCR Loan Approval.
- What Is a Cross-Collateral Loan in Nevada for Rentals?
- Why a DSCR Loan Protects Your Next Loan in Las Vegas.
- Will My Unique Las Vegas Property Get a DSCR Loan in Nevada?
- Your First DSCR Loan Guide for Las Vegas, Nevada.
- Zoning Risk: The Hidden DSCR Loan Killer in Las Vegas Nevada.
How do you refinance or tap equity on a Henderson home?
- Cash from a Nevada Rental with a DSCR Refinance.
- Using a DSCR Cash-Out Refinance to Scale a Las Vegas Rental Portfolio.
- How to Refinance in Nevada to Buy Out Your Spouse.
- How to Speed Up Your Las Vegas DSCR Loan Refinance.
- Mortgage Recast vs. Refinance in Nevada: Which Saves More?
- Nevada HELOC vs Cash-Out Refinance: Fund Your Next Home.
- Refinance FHA to Conventional Loan in Nevada.
- Should You Recast Your Mortgage in Nevada? A Guide.
- Tap Nevada Rental Equity Without a Cash-Out Refinance.
- Use Home Equity to Buy a Rental Property in Nevada?
- VA Cash-Out Refinance vs HELOC in Nevada: A 2024 Guide.
- What Is a Rate and Term Refinance in Las Vegas, Nevada?
Buying, building or refinancing in Henderson? Call or text (702) 766-3744, apply now or contact us. We compare FHA, VA, conventional, jumbo, bank-statement and DSCR options for you.
By David Ghazaryan, NMLS 1486726, iQRATE Mortgages (NMLS 1862492). Updated October 31, 2026. General information, not a loan offer or commitment. All loans are subject to credit approval. Equal Housing Opportunity.
Is a mortgage broker better than a bank or builder’s lender in Henderson?
It depends on your file. A broker can compare many wholesale lenders and move your loan if one lender declines, which helps with jumbo, self-employed, retiree and investor loans. A bank may offer relationship pricing, and a builder may offer incentives for using its lender. Compare total costs on Loan Estimates from each on the same day.
How do mortgage brokers get paid?
Either the lender pays the broker or you do, but not both on the same loan. Under Regulation Z, a loan originator’s pay cannot be based on your interest rate or other loan terms. The broker’s compensation appears on your Loan Estimate and Closing Disclosure.
What is the median home price in Henderson?
Nevada Real Estate Group’s analysis of MLS data found Henderson’s July 2026 median sold price was $490,000 across all residential types: $525,000 for single-family homes and $330,000 for condos and townhomes. The median asking price on September 15, 2026 was $535,000.
How fast are homes selling in Henderson?
The median Henderson home that closed in July 2026 sold after 38 days at 98.8% of its final list price, and 60.5% of sales closed below list. That is slower than Las Vegas and North Las Vegas, which gives buyers more room to negotiate.
What are home values by ZIP code in Henderson?
Zillow’s Home Value Index for September 2026 shows typical values of about $400,000 in 89014 and 89015, $458,000 to $468,000 in 89074, 89002 and 89011, $521,000 to $526,000 in 89012 and 89044, and $594,000 in 89052. Each is 1.2% to 3.3% below a year earlier.
At what price does a Henderson loan become a jumbo loan?
A one-unit loan above $832,750 is jumbo in Clark County in 2026. With 10% down you stay conforming up to a price of about $925,000; with 20% down, up to about $1,040,000; with 25% down, up to about $1,110,000.
What are the 2026 loan limits for duplexes and fourplexes in Henderson?
In Clark County for 2026 the FHA limits are $541,287 for one unit, $693,050 for two, $837,700 for three and $1,041,125 for four. Conforming limits are $832,750, $1,066,250, $1,288,800 and $1,601,750.
What is the Inspirada LID?
Inspirada parcels are in the City of Henderson’s Local Improvement District T-18, which repays bonds for community infrastructure through an annual assessment. The final installment is due June 1, 2035. Lenders count the assessment in your monthly payment, and Assessment Management Group can provide a payoff figure.
Does Cadence have an LID or SID?
According to the developer’s FAQ, Cadence has no SID or LID. Owners pay a master association fee, reported at $225 a quarter in 2026, and some neighborhoods have sub-association dues or non-HOA assessment fees.
How do HOA dues affect my Henderson mortgage?
Lenders add every HOA layer, master and sub-association, to your monthly housing payment when they calculate your debt-to-income ratio. Higher dues reduce the price you qualify for, so we get the resale package figures early instead of relying on the listing.
What does it cost to register a short-term rental in Henderson?
The City of Henderson charges an $848 non-refundable registration fee per property each year. Owners also need a Nevada business license, at least $1,000,000 of general liability insurance, a certification class, a Clark County local contact and HOA documents that expressly allow short-term rentals.
Can I take over a seller’s Henderson short-term rental registration?
No. Under the city’s registrant acknowledgement, any change in record ownership, including a transfer of interests in an owning entity, ends the registration. A buyer must register again and pay a new fee.
What lodging tax applies to Henderson short-term rentals?
The combined transient lodging tax for registered short-term rentals in Henderson is 13% of rental revenue. Reports and payments are due monthly by the 15th, even in months with no rentals, and the owner is liable whether or not the tax was collected.
Can I get a mortgage in Sun City Anthem?
Yes. Age-restricted 55+ communities like Sun City Anthem are financed with the same conventional, FHA, VA and jumbo programs as other homes, subject to the HOA review. Retirees can qualify with Social Security, pensions, documented distributions or an asset depletion program. Sun City Anthem’s 12-month median sale price through September 18, 2026 was $588,500.
What should I know about financing in Lake Las Vegas?
Lake Las Vegas had 11.8 months of supply and a 59-day median to contract in the 12 months ending September 18, 2026, so buyers often have negotiating room. Condo projects need a lender review, HOA costs can be higher, and second-home or investor occupancy changes the loan terms.
What is the FHA mortgage insurance premium in Henderson?
FHA charges an upfront premium of 1.75% of the base loan, usually financed, plus an annual premium. For a 30-year loan of $726,200 or less, the annual premium is 0.55% with under 5% down and 0.50% with 5% or more down. It lasts for the life of the loan unless you put at least 10% down, in which case it lasts 11 years.
How much is the VA funding fee?
For a first-time VA purchase with less than 5% down, the funding fee is 2.15% of the loan; after first use it is 3.3%. With 5% down it is 1.5%, and with 10% down 1.25%. Veterans receiving VA disability compensation are generally exempt, and the fee can be financed.
Can I use Home Is Possible down payment assistance in Henderson?
Yes, if you meet the program rules. The first-time buyer options require that you have not owned a primary residence in the last three years and a 640 or higher score; the conventional version caps the price at $570,000. The HIP-DPA options are open to repeat buyers, with a $165,000 income limit on the government-loan version. Assistance is a 0% second mortgage repaid when you sell, refinance or pay off the loan.
How much is property tax on a Henderson home?
The Henderson city district rate is $2.9613 per $100 of assessed value for fiscal year 2026-2027, and assessed value is 35% of the Assessor’s taxable value. That works out to about $1,036 per $100,000 of taxable value before Nevada’s cap, which limits increases on a primary residence to 3% a year.
What rents do lenders use for a Henderson DSCR loan?
Lenders rely on the appraiser’s rent schedule for the specific home. As a public benchmark, HUD’s FY 2026 Fair Market Rents for the Las Vegas-Henderson-North Las Vegas metro are $1,735 for two bedrooms, $2,413 for three and $2,764 for four, including utilities, and Henderson’s 2020-2024 median gross rent was $1,824.
Can I buy in Henderson before I sell my California home?
Often, yes. You can qualify with both payments, use a bridge loan secured by the California home, or sell first and arrange a rent-back. The right choice depends on your income, your equity and how quickly you need to move.
Sources
- FHFA, Conforming Loan Limit Values for 2026
- HUD Mortgagee Letter 2025-23, 2026 FHA loan limits
- Nevada Department of Taxation, Real Property Transfer Tax
- NRS 361.4723, 3% primary-residence tax cap
- Nevada Housing Division, Home Is Possible
- Clark County Treasurer, tax rate by district
- Las Vegas Realtors September 2026 report (via News 3 Las Vegas, Oct 6, 2026)
- Clark County, short-term rental units (unincorporated areas)
- City of Henderson, short-term vacation rentals
- Nevada Real Estate Group, Henderson market report September 2026
- Nevada Rural Housing, down payment assistance (Home At Last, Launchpad, Rural Rocks $20K)
Talk to a broker about Henderson
Get My Custom Rate Now · or call (702) 766-3744
iQRATE Mortgages · NMLS 1862492 · 6360 S Rainbow Blvd Ste 101, Las Vegas, NV 89118. David Ghazaryan, Mortgage Broker, NMLS 1486726. Verify us on NMLS Consumer Access. Equal Housing Opportunity. Programs, rates and terms change and are subject to credit, property and underwriting approval; local facts on this page are from the public sources below and are not legal or tax advice.
More: Nevada mortgage broker · DSCR loans · Bank statement loans · Our guarantees · Closing costs by state