
Why does my high business revenue not qualify me for a jumbo loan in Beverly Hills?
It's a common and frustrating scenario for successful entrepreneurs in California. Your business is generating millions in revenue, yet when you apply for a jumbo loan to buy a home in Beverly Hills, the lender rejects your application. The problem isn't your revenue; it's the income figure lenders are required to use.
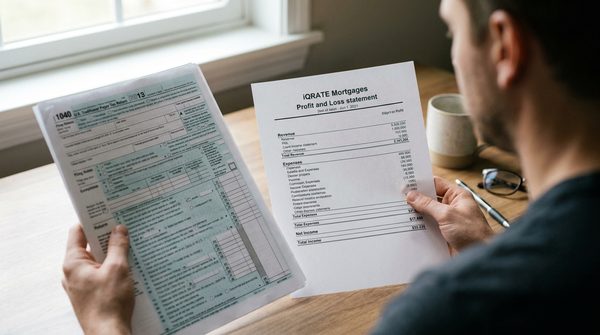
Traditional mortgage underwriting strictly follows the numbers on your federal tax returns. Lenders calculate your qualifying income based on your Adjusted Gross Income (AGI) or net income after all business expenses and deductions have been claimed. While minimizing your tax liability is a smart business strategy, it creates a significant obstacle for mortgage qualification.
Lenders use this net income figure to calculate your debt-to-income (DTI) ratio. If your tax returns show a low net profit, your DTI will appear too high for the loan amount you need.
Example:
- Your consulting firm in Beverly Hills grosses $1.5 million annually.
- Your accountant strategically writes off $1.3 million in expenses, including salaries, marketing, and equipment depreciation.
- Your net income on your tax return is $200,000.
- The lender only sees the $200,000. For a multi-million dollar jumbo loan, that income is insufficient, leading to a denial despite your business's strong cash flow.
What is a bank statement mortgage and how does it work in California?
A bank statement mortgage is a powerful tool for self-employed borrowers. It's a type of Non-Qualified Mortgage (Non-QM), meaning it doesn't have to adhere to the strict income verification rules of conventional loans. Instead of tax returns, lenders use your business bank statements to prove your income.
Here’s the process:
- Documentation: You provide 12 or 24 months of business bank statements to the lender.
- Income Calculation: The lender analyzes the monthly deposits to determine a consistent cash flow. They do not look at withdrawals or individual expenses.
- Expense Factor: To account for business operating costs, the lender applies an 'expense factor'. They will typically consider a percentage of the total deposits, often 50%, as your qualifying income. (The data, information, or policy mentioned here may vary over time.) This factor can sometimes be adjusted with documentation proving lower overhead.
Example: Let's say you own a thriving e-commerce business in San Diego. Your business bank account shows an average of $120,000 in deposits each month for the last 24 months.
- Total Annual Deposits: $120,000 x 12 = $1,440,000
- Lender's Expense Factor: 50%
- Qualifying Annual Income: $1,440,000 x 0.50 = $720,000
This $720,000 figure is what the lender uses for your DTI calculation, providing a much more accurate reflection of your financial capacity than your tax returns would.
How can a profit and loss statement get my jumbo loan approved in San Diego?
A Profit and Loss (P&L) statement loan is another excellent Non-QM option for business owners, particularly those with well-organized financials and a Certified Public Accountant (CPA).
This loan program allows the lender to use a P&L statement, prepared and signed by your CPA, to determine your qualifying income. This is often paired with a few recent business bank statements to verify the information presented on the P&L.
This approach is beneficial when your actual business expenses are significantly lower than the standard 50% expense factor used in many bank statement loans. The P&L provides a detailed breakdown of your revenue and itemized expenses, which can result in a higher net profit figure for qualification purposes. For a high-value home in San Diego, this can make a substantial difference.
Lenders typically require:
- A year-to-date P&L statement.
- A P&L from the previous full year.
- A letter from your CPA attesting to the accuracy of the documents.
- Two to three months of business bank statements to show cash flow consistency.
What do lenders look for in my business bank statements?
When underwriters review your bank statements for a jumbo loan, they are looking for stability and consistency. They are building a case that your business provides a reliable income stream capable of supporting the mortgage payment. Key items they scrutinize include:
- Consistent Deposits: They want to see a predictable pattern of deposits month over month. Wild fluctuations can be a red flag unless they are normal for your industry (e.g., seasonal businesses).
- Number of Deposits: Many small deposits are often viewed more favorably than one or two large, irregular deposits, as this indicates a healthy base of customers.
- No Non-Sufficient Funds (NSF) or Overdrafts: Frequent overdrafts suggest poor cash flow management and are a major concern for lenders.
- Sufficient Ending Balances: Ending daily balances should be consistently positive and show a healthy cash cushion.
- Clear Separation of Funds: Commingling personal and business funds is highly discouraged. Lenders need to clearly identify business-related revenue.
Which is better for me: a bank statement loan or a profit and loss loan?
Choosing between these two loan types depends entirely on your business structure and bookkeeping practices. Neither is inherently better; the right choice is the one that produces the highest qualifying income for your specific situation.
A bank statement loan may be better if:
- Your business has very high and consistent cash flow, but your expense tracking isn't meticulous.
- You prefer a simpler documentation process that doesn't require deep involvement from your CPA.
- Your actual business expenses are at or above the lender's standard expense factor (e.g., 50%).
A P&L loan may be better if:
- You run a low-overhead business, such as a professional consultancy or digital services firm in Beverly Hills. Your actual expenses might only be 20-30% of revenue.
- You maintain immaculate financial records and have a strong relationship with a CPA who can produce detailed, signed statements.
- You want to maximize your qualifying income by showing your true, higher profit margins.
How do lenders add back business write-offs to calculate my income?
'Adding back' deductions is a technique used in more traditional underwriting, often referred to as an 'Alt-Doc' loan, which still starts with your tax returns but allows for certain adjustments. This is different from a pure bank statement or P&L loan that bypasses tax returns altogether.
In this process, an underwriter analyzes your business tax returns (like a Schedule C or 1120-S) and adds certain non-cash expenses back to your net income. These are legitimate deductions for tax purposes, but since they don't represent an actual cash outlay, they can be included in your qualifying income.
Common add-backs include:
- Depreciation: A paper expense used to account for the decreasing value of an asset.
- Depletion: Similar to depreciation, but used for natural resources.
- Amortization: The write-down of intangible assets over time.
- One-Time Major Purchases: A significant, non-recurring equipment purchase may be added back.
- Business Use of Home: The portion of your home expenses written off for business use.
While this can boost your qualifying income, the process is complex and subject to underwriter discretion. For many high-revenue business owners, the straightforward calculations of bank statement or P&L loans are often more predictable and effective for securing a jumbo loan.
What kind of interest rates can I expect on these types of jumbo loans?
It is important to set realistic expectations regarding interest rates for Non-QM loans. Because these loans do not meet the standardized guidelines set by Fannie Mae and Freddie Mac, they represent a higher perceived risk to the lender. Consequently, the interest rates are typically higher than those for a conventional jumbo loan.
You can generally expect interest rates to be 0.5% to 2% higher than a traditional loan. (The data, information, or policy mentioned here may vary over time.) The exact rate you receive will depend on several factors:
- Credit Score: A higher credit score (ideally 720+) will secure a more favorable rate.
- Down Payment / Loan-to-Value (LTV): A larger down payment (e.g., 25% or more) reduces the lender's risk and can lower your rate.
- Cash Reserves: Lenders want to see that you have significant liquid assets remaining after closing, often 6 to 12 months of mortgage payments.
- Documentation Type: A 24-month bank statement loan is often seen as lower risk than a 12-month program and may come with a slightly better rate.
While the rate may be higher, these loans provide a vital pathway to homeownership that would otherwise be closed off to successful, self-employed individuals. If your business's high revenue isn't reflected on your tax returns, don't assume a jumbo loan is out of reach. Exploring alternative documentation options with a mortgage strategist can reveal your true borrowing power and open the door to your next home.
Don't let tax returns limit your homeownership goals. Discover how your true business revenue can qualify you for the home you deserve. Apply for a mortgage today to unlock your real borrowing potential.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
CFPB: What is a debt-to-income ratio?
Fannie Mae: Underwriting Factors for a Self-Employed Borrower