

Can You Really Get a Mortgage While in Chapter 13?
One of the most persistent myths in real estate is that filing for Chapter 13 bankruptcy automatically disqualifies you from buying a home for the entire three-to-five-year repayment period. For many aspiring homeowners, this misconception can unnecessarily delay their dreams. The truth is, you can secure a mortgage while in an active Chapter 13 plan, but the path is specific and requires navigating a clear set of rules.
Unlike a Chapter 7 liquidation bankruptcy, a Chapter 13 is a reorganization of debt. You are actively repaying your creditors through a court-approved plan. Lenders, particularly those backing government-insured loans, recognize this commitment. They have established specific guidelines that allow borrowers to take on new mortgage debt, provided they can demonstrate a solid track record of financial responsibility since the bankruptcy filing.
The key is to work with government-backed programs like the Federal Housing Administration (FHA) or the Department of Veterans Affairs (VA) loans). These programs are designed to provide more flexible lending standards and have explicit rules for handling applications from borrowers in Chapter 13.
Navigating FHA Guidelines for a Mortgage in Chapter 13
The FHA loan program is the most common route for homebuyers seeking a mortgage during Chapter 13. The FHA provides clear, standardized guidelines for lenders to follow, making the process predictable if you meet the criteria. These rules are designed to ensure that taking on a mortgage will not jeopardize your bankruptcy repayment plan or place you in a position of financial hardship.
To qualify, you must meet all standard FHA requirements for credit, income, and assets, in addition to the specific bankruptcy-related rules. The lender will evaluate your entire financial profile to confirm you are a reliable borrower who has learned from past financial challenges.
The 12-Month On-Time Payment Requirement
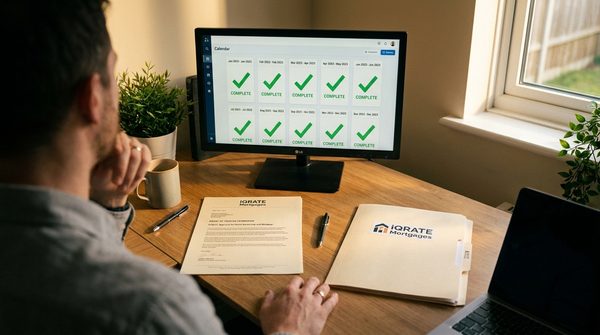
The most important threshold you must meet is the payment history within your bankruptcy plan. To be considered for an FHA loan, you must have made at least 12 consecutive, on-time payments to the Chapter 13 trustee. There is no flexibility on this point.
- What constitutes 'on-time'? This means the trustee received each payment in the correct amount and by the due date specified in your plan. A single late payment can reset the 12-month clock, forcing you to wait longer to apply.
- Why 12 months? This period serves as a crucial test of your financial discipline. It demonstrates to the lender and the FHA that you are capable of consistently managing your obligations under the court's supervision. It proves that your financial situation has stabilized since the initial filing.
Lenders will require a complete payment history ledger from your trustee as verification. This document, often called a 'transaction history', shows every payment you've made, the date it was received, and the date it was disbursed. Any inconsistencies will be flagged immediately.
Securing Approval from the Court and Trustee
Beyond meeting the FHA's 12-month payment rule, you cannot proceed without legal approval. You must obtain explicit, written permission from both the bankruptcy court and your appointed trustee. This is a non-negotiable step that protects all parties involved.
This process typically involves your attorney filing a 'Motion to Incur Debt' with the U.S. Bankruptcy Court. Here’s what that entails:
- The Role of the Trustee: The Chapter 13 trustee's primary job is to administer your plan and ensure creditors are paid. Before granting permission, they will review the proposed mortgage terms, including the principal amount, interest rate, and estimated monthly payment (PITI: principal, interest, taxes, and insurance). They need to be convinced that you can afford the new house payment in addition to your ongoing Chapter 13 plan payment without defaulting.
- The Role of the Court: The bankruptcy judge gives the final approval. The court's main concern is the feasibility of your budget. Your attorney will present a revised budget showing your current income, your Chapter 13 payment, and the proposed new mortgage payment. If the court agrees that the new debt is reasonable and won't undermine your repayment plan, it will issue a court order granting you permission to obtain the mortgage.
Lenders will not move forward without a copy of this signed court order. It's a critical piece of documentation for the loan file.
How Your Chapter 13 Plan Impacts Your DTI
Your Debt-to-Income (DTI) ratio is a cornerstone of mortgage qualification. It measures how much of your gross monthly income goes toward paying your debts. When you are in Chapter 13, your monthly plan payment is treated as a regular debt obligation, just like a car loan or credit card payment.
This is a critical calculation. The lender will add your proposed monthly housing payment to your existing debts and your Chapter 13 trustee payment. The total is then divided by your gross monthly income.
Let’s look at a practical example:
- Gross Monthly Income: $7,000
- Car Payment: $450
- Student Loan Payment: $200
- Chapter 13 Plan Payment: $600
- Proposed Monthly Mortgage Payment (PITI): $1,800
Calculation:
- Total Monthly Debts: $450 (car) + $200 (student loan) + $600 (Chapter 13) + $1,800 (mortgage) = $3,050
- DTI Ratio: $3,050 / $7,000 = 0.4357, or 43.6%
While a common benchmark for DTI is 43%, FHA guidelines can allow for a total DTI ratio of up to 56.9% or higher with strong compensating factors like a high credit score or significant cash reserves. (The data, information, or policy mentioned here may vary over time.) Including the Chapter 13 payment makes meeting DTI requirements more challenging, so it’s essential to manage other debts carefully and have a clear understanding of your budget.
Required Documents from the Bankruptcy Trustee
When you apply for a mortgage during Chapter 13, your loan file will contain several documents that are not part of a standard application. Your lender will require you to provide the following items obtained directly from your trustee or attorney:
- Letter of Permission from the Trustee: A signed letter from your Chapter 13 trustee explicitly stating they have reviewed your request and approve of you incurring new mortgage debt.
- Copy of the Filed Bankruptcy Plan: This document details all the debts included in the bankruptcy, the repayment terms, and the monthly payment amount.
- 12-Month Payment History: The official ledger from the trustee's office showing a perfect record of at least 12 consecutive on-time payments.
- Signed Court Order: The official order from the bankruptcy judge authorizing you to secure a mortgage for a specific amount or property.
Gathering this documentation can take time, so it's wise to start the conversation with your bankruptcy attorney early in the homebuying process.
Are Conventional Loans an Option During Chapter 13?
For borrowers in an active Chapter 13 plan, conventional loans are generally not an option. Conventional loans are those that conform to the guidelines set by Fannie Mae and Freddie Mac. Their rules regarding bankruptcy are much stricter.
Typically, Fannie Mae and Freddie Mac require a waiting period after a bankruptcy has been discharged or dismissed. The waiting period is usually:
- Two years from the discharge of a Chapter 13 bankruptcy.
- Four years from the dismissal of a Chapter 13 bankruptcy.
Because you are still in the plan, you do not meet these post-bankruptcy waiting period requirements. This is why FHA and VA loans are the primary financial instruments available to those looking to buy a home mid-bankruptcy.
Chapter 13 Mortgage vs. Post-Discharge Home Purchase
Understanding the difference between buying during Chapter 13 versus after it's discharged is crucial for planning your financial future.
Buying a Home During Active Chapter 13:
- Pros: Allows you to become a homeowner sooner and start building equity without waiting years for the plan to end.
- Cons: Requires court and trustee approval, which adds complexity and time. Your Chapter 13 payment is included in your DTI, potentially limiting your purchasing power. Loan options are primarily limited to FHA and VA.
Buying a Home After Chapter 13 Discharge:
- Pros: No need for court permission. The Chapter 13 payment is gone, which significantly lowers your DTI ratio and increases your purchasing power. You may be eligible for a conventional loan after a waiting period, potentially offering better terms or avoiding mortgage insurance.
- Cons: You must wait until the entire 3-5 year repayment plan is complete, plus any additional seasoning period required by the lender. This can mean delaying homeownership for a significant amount of time. Navigating a mortgage application during an active Chapter 13 bankruptcy requires precision and expertise. The rules are strict, and the documentation is extensive. To ensure a smooth process, partner with a mortgage professional who has direct experience with FHA and VA guidelines for bankruptcy financing. They can help you prepare your documentation, coordinate with your attorney, and present your file for a successful approval.
Feeling more confident about your path to homeownership during Chapter 13? The process is detailed, but you don't have to navigate it alone. If you're ready to explore your options with an experienced team, take the first step and Apply now to see where you stand.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
HUD Handbook 4000.1 (FHA Single Family Housing Policy Handbook)
Consumer Financial Protection Bureau - How can I rebuild my credit after bankruptcy?









