

What Does a 'No-Cost' VA IRRRL Loan Really Mean?
Veterans across Florida, from Jacksonville to Pensacola, often receive compelling mailers advertising a 'no-cost' VA Interest Rate Reduction Refinance Loan (IRRRL). The promise is tempting: lower your monthly mortgage payment without paying a dime out of pocket. However, the term 'no-cost' is a marketing phrase, not a financial reality. It rarely means the refinance is free.
A 'no-cost' IRRRL typically means you have no out-of-pocket expenses at closing. The costs associated with the loan, which can be thousands of dollars, are handled in one of two ways:
- Rolling Costs into the Loan Balance: This is the most common method. The lender takes all the closing costs, including their origination fee, title fees, and the VA funding fee, and adds them to your existing loan principal. For example, if your current VA loan balance is $300,000 and the closing costs are $5,000, your new loan will be for $305,000. You didn't write a check at closing, but you now owe more money.
- Accepting a Higher Interest Rate (Lender Credits): A lender might offer you a slightly higher interest rate than the absolute best rate available. In exchange, they provide a 'lender credit' that covers some or all of the closing costs. You might get a 3.75% rate that covers all costs, while a 3.5% rate would require you to pay costs yourself. You avoid increasing your loan balance, but you pay more in interest over the life of the loan.
Neither option is inherently bad, but transparency is crucial. The danger lies in aggressive marketing that obscures how these costs are being paid, leading veterans to believe the service is free when it is not.
Where Are Closing Costs Typically Hidden in These Refinance Offers?
The key to uncovering the true cost of an IRRRL is learning to read the Loan Estimate (LE). This standardized three-page document is your best tool for seeing past the marketing flyers. When a lender in Tampa sends you an offer, insist on seeing the LE. This is where you'll find the fees, no matter how they are paid.
Lender Credits vs. Rolling Costs into the Loan
On your Loan Estimate, the story of your 'no-cost' loan unfolds. If costs are rolled in, you will see the 'Loan Amount' on Page 1 is higher than your current mortgage payoff amount. If the lender is giving you a credit, you will see a negative number in Section J on Page 2, labeled 'Lender Credits'.
Example: A veteran in Jacksonville has a current loan balance of $250,000.
- Offer A (Costs Rolled In): The Loan Estimate shows a new Loan Amount of $254,500. The $4,500 in closing costs have been added to the principal.
- Offer B (Lender Credit): The Loan Estimate shows a new Loan Amount of $250,000. In Section J, it shows a Lender Credit of -$4,500 to offset the costs. However, the interest rate on this offer is likely higher than Offer A's.
Scrutinizing Section A: Origination Charges
This is the lender's direct profit center. It includes fees for processing, underwriting, and originating the loan. The VA allows lenders to charge a flat fee of up to 1% of the loan amount. (The data, information, or policy mentioned here may vary over time.) This '1% origination fee' is meant to cover all of the lender's administrative costs. Some lenders, however, may try to break this out into multiple line items like 'processing fee', 'underwriting fee', and 'application fee'. Always question these fees. A transparent lender should be able to justify every dollar in this section.
Understanding Section B: Third-Party Services
These are fees for services provided by other companies that are necessary to close your loan. They are pass-through costs, but that doesn't mean they can't be inflated.
- Title Fees: Costs for the title search, title insurance, and settlement agent. (The data, information, or policy mentioned here may vary over time.)
- Recording Fees: The cost charged by your county to record the new mortgage. (The data, information, or policy mentioned here may vary over time.)
- VA Funding Fee: This is a mandatory fee paid directly to the Department of Veterans Affairs that helps fund the VA loan program. For most IRRRLs, it is 0.5% of the loan amount. Veterans receiving VA disability compensation are exempt from this fee. An unscrupulous lender might 'forget' to waive this fee for an exempt veteran, adding a significant and unnecessary cost.
How Do I Compare Two Different IRRRL Loan Estimates Side-by-Side?
Comparing offers from different lenders is the single best way to ensure you're getting a fair deal. When you have two Loan Estimates, one from a lender in Pensacola and another from a different company, don't just look at the interest rate or monthly payment. You need to perform a methodical comparison.
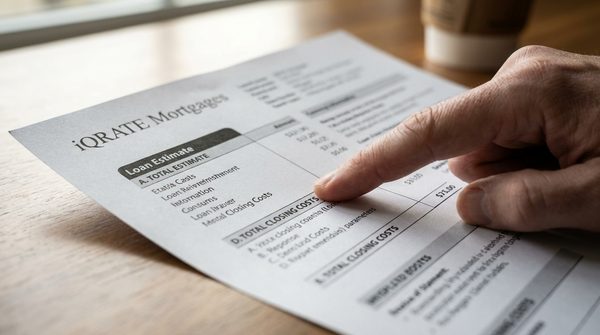
- Start on Page 3: The 'Comparisons' Section. This section shows you how much you will have paid in principal, interest, mortgage insurance, and loan costs in the first five years. It's a powerful at-a-glance tool for understanding the long-term cost.
- Check the 'Total Loan Costs' (Section D on Page 2). This is the sum of the lender's origination charges and the third-party service fees. How much does one lender charge versus the other?
- Confirm the New 'Loan Amount' on Page 1. Is one offer adding significantly more to your principal balance than the other? A lower payment isn't a good deal if it comes from a much larger loan.
- Analyze the New 'Principal & Interest' (P&I) Payment. This is the number most advertisements focus on. Make sure the reduction in your payment is substantial enough to justify the refinance.
- Verify the 'Estimated Cash to Close' on Page 1. For a true 'no-cost' refinance, this number should be zero or a negative number (meaning you get money back). If it shows you need to bring money to closing, it's not a no-cost loan.
What Specific Questions Should I Ask a Lender in Tampa About Their Fees?
When you're on the phone with a loan officer, being prepared with specific, direct questions can cut through the sales pitch and get you the facts. Arm yourself with this list:
- 'Is this interest rate based on paying discount points, or is it the par rate?'
- 'Can you confirm the total amount of closing costs and explain how they are being paid? Are they rolled into the loan, covered by a lender credit, or a combination?'
- 'Please provide an itemized breakdown of every fee listed in Section A of the Loan Estimate.'
- 'What is the total new loan amount after all costs and the VA Funding Fee are included?'
- 'Does this refinance meet all the requirements of the VA's tangible net benefit rule?'
- 'I am exempt from the VA Funding Fee due to my disability rating. Can you confirm it has been waived on my Loan Estimate?'
Is Skipping Payments a Real Benefit or a Marketing Gimmick?
Many IRRRL offers are framed around the 'benefit' of skipping one or two mortgage payments. This is one of the most misunderstood and misleading aspects of refinancing. You are not getting free months of housing. You are deferring the payments.
Here's how it works: Your new loan closes, and your first payment isn't due for 30-60 days. During this period, interest on your new, larger loan balance continues to accrue daily. This accrued interest is then added to your principal balance. So, while you get temporary cash-flow relief by not writing a check, you end up paying interest on that deferred interest for the entire life of the new loan. It is a marketing gimmick, not a true financial benefit.
What Is the Tangible Net Benefit Rule and How Does It Protect Me?
The Department of Veterans Affairs implemented the Net Tangible Benefit (NTB) test to protect veterans from 'loan churning'—a predatory practice where lenders repeatedly refinance a loan to generate fees, with little to no benefit to the borrower.
For an IRRRL to be approved, the lender must certify that it provides a clear, tangible benefit to you. This usually means the loan must meet one of these conditions:
- The new loan's principal and interest (P&I) payment is lower than the old loan's P&I payment.
- The new loan has a shorter term than the old loan.
- The borrower is moving from an adjustable-rate mortgage (ARM) to a fixed-rate mortgage.
- The new loan's interest rate is lower than the previous loan's rate.
- The loan's term is not more than 10 years longer than the remaining term of the loan being refinanced.
Additionally, all costs and fees associated with the IRRRL must be recouped through the savings from the lower monthly payment within 36 months. This recoupment rule is a critical safeguard. If it takes longer than three years to break even, the VA will not insure the loan.
When Does Refinancing My Veteran Affairs Loan Not Make Financial Sense?
An IRRRL is a powerful tool, but it's not always the right move. Rushing into a refinance without considering the long-term implications can be a costly mistake.
Consider a veteran in Tampa with 18 years left on a 30-year mortgage. A lender offers to refinance them into a new 30-year loan. While the monthly payment might drop by $150, they have just reset their mortgage clock, adding 12 years of payments. The total interest paid over the life of the new loan could be tens of thousands of dollars more than if they had simply stayed with their current mortgage.
Refinancing may not be wise if:
- The interest rate reduction is minimal. A drop of 0.25% might not generate enough savings to overcome the closing costs in a reasonable time.
- You plan to sell the home soon. If you sell before you hit the 'break-even point' where your monthly savings have paid back the closing costs, you will have lost money on the transaction.
- It significantly extends your loan term. Always calculate the total interest paid. Lowering your payment by stretching out your debt is often a poor financial trade-off. Understanding your VA IRRRL options is the first step toward a smart financial decision. If you're ready to compare offers with confidence, connect with a mortgage strategist who can provide a transparent breakdown of your true costs and benefits.
Ready to explore your options with clarity and confidence? Apply now for a transparent mortgage analysis and see what you truly qualify for.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.
References
VA Interest Rate Reduction Refinance Loan (IRRRL)
The loan estimate and closing disclosure: Tools for homebuyers









