
Understanding Jumbo Loans for Florida Second Homes
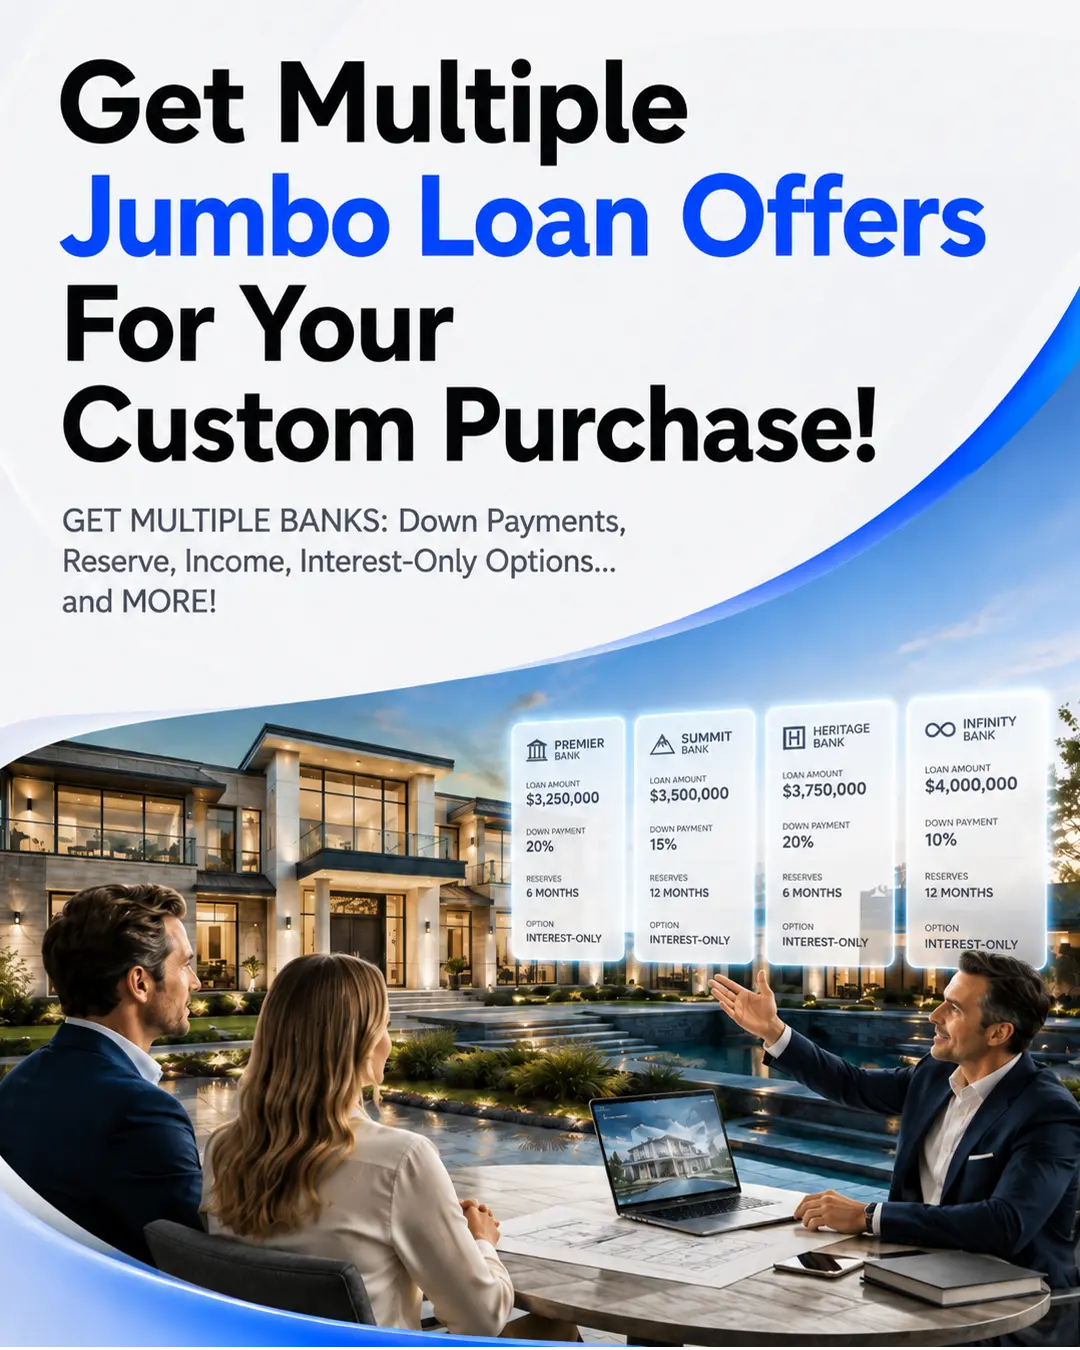
Purchasing a second home in a luxury market like Miami or Palm Beach is an exciting venture, but the financing process is distinctly different from buying a primary residence. When the loan amount exceeds the conforming loan limits set by the Federal Housing Finance Agency (FHFA), it enters 'jumbo' territory. For a second home, lenders view this as a higher-risk loan, which translates to more stringent qualification requirements. You're not just proving you can afford one mortgage; you're proving you can comfortably manage the costs of multiple high-value properties without financial strain. This guide breaks down the essential requirements to help you prepare for a smooth and successful jumbo loan application for your Florida vacation home.
What is the minimum down payment for a second home jumbo loan in Miami?
The down payment is one of the most significant differences when financing a second home with a jumbo loan. While primary residences might qualify for lower down payments, lenders require more 'skin in the game' for a second home because it's considered a luxury, not a necessity.
- Standard Requirement: Expect a minimum down payment of 20% to 30%. For a $2 million property in Miami, this means having $400,000 to $600,000 in liquid cash ready for the transaction. (The data, information, or policy mentioned here may vary over time.)
- Loan-to-Value (LTV) Ratio: Lenders are targeting a lower LTV ratio, typically 70-80%, on second homes. A higher down payment reduces their risk. If a borrower defaults, the lender has a larger equity cushion to absorb potential losses during a foreclosure sale.
- Tiered Down Payments: The required down payment often increases with the loan amount. For example:
- Loan up to $1.5 million: 20% down might be acceptable.
- Loan from $1.5 million to $2.5 million: 25-30% down is more likely.
- Loan over $2.5 million: A 30-40% down payment could be required.
Lenders view a substantial down payment as a sign of strong financial discipline and a lower likelihood of default. It demonstrates that you are not over-leveraging yourself to acquire the property.
How many months of reserves do I need for a Palm Beach property?
Cash reserves are liquid funds you have available after covering the down payment and closing costs. For a high-value property in an area like Palm Beach, lenders need to see a significant financial safety net. These reserves prove you can continue making payments on all your properties, even if your income is unexpectedly interrupted.
- What Counts as Reserves: These funds must be in accessible accounts like checking, savings, or non-retirement investment accounts. Retirement funds like a 401(k) or IRA may sometimes be counted, but usually at a discounted value (e.g., 60-70% of the vested balance).
- Calculating the Requirement: The reserve requirement is calculated in terms of months of PITI (Principal, Interest, Taxes, and Insurance). This isn't just for the new Palm Beach property; it's often the total PITI for your primary home, the new second home, and any other properties you own.
- Typical Reserve Amount: For a jumbo loan on a second home, lenders typically require 6 to 12 months of PITI in reserves. Some may require even more for multi-million dollar properties. (The data, information, or policy mentioned here may vary over time.)
Example:
- Primary Home PITI: $7,000/month
- New Palm Beach Second Home PITI: $12,000/month
- Total Monthly Housing Debt: $19,000
- Required Reserves (12 months): $19,000 x 12 = $228,000
This $228,000 must be in your accounts after you've paid the down payment and all closing costs. It’s a critical component of the underwriting decision.
Are interest rates higher for second home mortgages?
Yes, you should expect a slightly higher interest rate for a second home jumbo loan compared to a primary residence mortgage. The difference isn't usually dramatic, but it reflects the lender's perceived risk.
- Risk-Based Pricing: Mortgages are priced based on risk. Statistically, borrowers are more likely to default on a vacation home than their primary residence during financial hardship. The higher interest rate, often 0.25% to 0.50% higher, compensates the lender for this elevated risk. (The data, information, or policy mentioned here may vary over time.)
- Market Factors: The specific rate depends on your credit score, down payment size, loan amount, and overall financial strength. A borrower with an 800 credit score and a 40% down payment will secure a more favorable rate than someone with a 720 score and 20% down.
- Shopping Around is Key: Because jumbo loans are not backed by government agencies, pricing and guidelines can vary significantly between lenders. Working with a mortgage strategist who has access to a wide network of lenders is crucial to finding the most competitive rate.
Can I use rental income to help qualify for a second home loan?
This is a common point of confusion. The answer is almost always no. Lenders have strict definitions that separate a 'second home' from an 'investment property', and the ability to use rental income is the key differentiator.
- Second Home Definition: A second home must be for your personal use and enjoyment for a portion of the year. You must occupy it yourself, and it generally must be a reasonable distance from your primary residence. Lenders will require you to sign a 'second home rider' at closing, attesting to this intended use.
- Investment Property: An investment property is purchased with the primary intent of generating rental income. The qualification rules are different, and while you can use projected rental income to help qualify, the down payment requirements are often even higher (e.g., 25-40%), and interest rates are typically less favorable than for a second home.
If you tell your lender you plan to rent out your Miami condo to offset costs, they will reclassify the loan as an investment property loan, changing the terms and requirements entirely. Be clear about your intentions from the start.
What are the property type restrictions for these loans in Miami?
Lenders are particularly selective about the types of properties they will finance with a jumbo loan, especially in a market like Miami with a high concentration of condominiums.
- Eligible Properties: Single-family homes, townhouses, and warrantable condos are generally acceptable.
- Ineligible or Difficult-to-Finance Properties:
- Condotels (Condo-Hotels): These are a major red flag for most lenders. If the building operates like a hotel with a front desk, daily cleaning services, and short-term rentals managed through a central system, it's typically non-warrantable and ineligible for traditional jumbo financing.
- Non-Warrantable Condos: A condo project can be deemed non-warrantable for many reasons, such as one entity owning too many units, pending litigation against the HOA, or a high percentage of non-owner-occupied units. Your lender will thoroughly vet the condo association's budget, reserves, and bylaws.
- Co-ops: Cooperative apartments are far less common in Florida but can be very difficult to finance with a jumbo loan.
The property appraisal and condo project review are critical steps in the underwriting process. A 'perfect' borrower can be denied if the property itself doesn't meet the lender's strict guidelines.
How do lenders view my other properties when I apply?
Lenders take a holistic view of your finances. They will analyze the debt associated with every property you own to calculate your debt-to-income (DTI) ratio.
- Calculating Total Housing Expense: The underwriter will sum the full PITI (Principal, Interest, Taxes, Insurance, and any HOA dues) for your primary residence, the proposed second home, and any other financed properties you own.
- DTI Calculation: This total housing expense, plus all other monthly debts (car loans, student loans, credit card payments), is divided by your gross monthly income. For jumbo loans, most lenders cap the DTI ratio at 43%. Some may go slightly higher for exceptionally strong borrowers, but it's a firm ceiling for most. (The data, information, or policy mentioned here may vary over time.)
Example:
- Gross Monthly Income: $50,000
- Primary Home PITI: $7,000
- Proposed Second Home PITI: $12,000
- Other Debts (cars, etc.): $3,000
- Total Monthly Debt: $22,000
- DTI Ratio: $22,000 / $50,000 = 44%
In this scenario, the borrower would be just over the typical 43% DTI limit and might need to pay down other debts or increase their down payment to reduce the second home's PITI and get approved.
Can I purchase the second home in a limited liability company?
For a property designated as a second home, the answer is typically no. Lenders require that second home and primary residence loans be made to an individual borrower, not a business entity.
- Vesting in Personal Name: The loan will be in your name, and the title (deed) to the property will be vested in your name or in a living trust. This provides the lender with a direct recourse to you as the borrower.
- LLCs are for Investment: Purchasing a property in an LLC is standard practice for investment properties. It provides liability protection and is intended for business purposes. Loans made to an LLC are commercial or 'portfolio' loans, which have entirely different terms, rates, and qualification standards. They are not the same as a conventional or jumbo residential mortgage.
Attempting to purchase a second home through an LLC will likely result in your loan application being denied or re-categorized as a more expensive commercial loan.
Does the underwriting process take longer for a second home?
Yes, the underwriting timeline for a jumbo loan on a second home is often longer and more intensive than for a standard conforming loan.
- Complex Financial Review: Underwriters will conduct a deep dive into your financial history. This includes verifying income from multiple sources (W-2s, K-1s, business tax returns), tracing the source of large deposits to ensure your down payment and reserves are not from borrowed funds, and analyzing your credit history in detail.
- Appraisal and Property Vetting: The appraisal for a luxury property in Palm Beach or Miami is more complex. The appraiser must find comparable sales for unique, high-value homes, which can take more time. If it's a condo, the underwriting team must also complete a full review of the condo association, as mentioned earlier.
- Typical Timeline: While a simple conforming loan might close in 30 days, it's wise to plan for a 45 to 60-day closing period for a second home jumbo loan. This extra time allows for the detailed documentation review and any potential hurdles that may arise with the property itself. (The data, information, or policy mentioned here may vary over time.)
The path to securing a jumbo loan for your Florida second home is complex, but you don't have to navigate it alone. When you're ready to explore your options and get a clear picture of your qualifications, take the first step. Apply now to connect with a mortgage expert who can guide you through the process.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.