
What is a 'Pre-Certified' or 'Finance-Ready' Property Listing?
A 'Pre-Certified' or 'Finance-Ready' listing is a property where the lender has proactively underwritten the asset itself before a buyer is even in the picture. This goes far beyond a buyer's pre-approval. While a pre-approval evaluates a buyer's financial health, a pre-certification evaluates the property's financial and legal health. It’s a lender’s stamp of approval on the real estate, signaling to the market that critical due diligence is already complete. (The data, information, or policy mentioned here may vary over time.)
The traditional home sale process puts property vetting on the back end. A seller accepts an offer, and only then does the buyer’s lender order a title search and, if applicable, scrutinize the homeowners association (HOA) or condominium documents. This period is filled with uncertainty. A hidden lien from a past owner, an unresolved permit issue, or a financially unstable condo association can derail the entire transaction weeks into the contract, forcing everyone back to square one.
A pre-certified listing flips this model. A forward-thinking lender partners with the listing agent to clear these hurdles upfront. The process involves a thorough review of:
- Preliminary Title Report: Searching for any clouds on the title, such as outstanding mortgages, judgments, or mechanic's liens that need to be resolved.
- Lien and Permit Searches: Ensuring there are no unexpected municipal liens or open permits that could complicate the closing.
- HOA/Condominium Association Documents: This is especially critical in markets like Miami and Naples. The lender obtains the condo questionnaire, reviews the association's budget for adequate reserves, checks for pending litigation, and confirms owner-occupancy ratios. This step verifies the entire project meets lending guidelines.
By completing this work ahead of time, the property is presented to the market as a clean, financeable asset. It's not just a home for sale; it's a transaction-ready package.
How Does Pre-Underwriting a Property Benefit the Seller Directly?
For a seller, the primary benefit of pre-underwriting their property is a massive reduction in risk and stress. The biggest fear for any seller is accepting an offer, taking their home off the market, and then having the deal collapse weeks later due to a property-related issue they knew nothing about. Pre-certification virtually eliminates this nightmare scenario.
Here are the direct advantages for the seller:
- Certainty and Peace of Mind: Knowing that the title is clear and the HOA is approved removes a huge variable from the selling equation. You can proceed with confidence, knowing a major closing obstacle has been cleared before you even list.
- Superior Marketability: A 'Finance-Ready' designation becomes a powerful marketing tool. Your agent can advertise that the property has been pre-certified by a lender, making it stand out from the competition. In a crowded Miami condo market, this can be the single factor that draws buyers to your unit over others.
- Attraction of Serious Buyers: This certification acts as a filter. It attracts committed, well-informed buyers who appreciate a straightforward process. Their agents will recognize the value and advise them that your property represents a lower-risk, higher-certainty purchase.
- Accelerated Closing Timeline: With title and HOA reviews completed, the timeline from contract to close can be significantly compressed. The buyer's lender doesn't need to start from scratch, potentially shaving one to two weeks off the closing period. (The data, information, or policy mentioned here may vary over time.)
- Strengthened Negotiating Position: Because you are offering a de-risked product, you can be firmer on your price and terms. Buyers have less leverage to ask for concessions related to title or condo association issues, as those concerns have already been addressed.
Imagine you are selling a beautiful waterfront condo in Naples. A pre-certified status assures potential buyers that there are no hidden special assessments looming from the HOA and that the building's financials are sound. This assurance can directly translate into a faster sale at a better price.
What is the Lender's Process to Certify a Listing's Title and HOA?
Certifying a property isn't an informal review; it's a structured process undertaken by the lender's underwriting team. It mirrors the same steps that would traditionally happen after a contract is signed, but it's done proactively. Lenders who offer this service have a specific workflow designed to collaborate with listing agents.
Here is a typical step-by-step breakdown:
- Strategic Partnership: The process begins when a listing agent partners with a mortgage provider that offers a pre-certification program. The agent provides the property address and contact information for the seller, title company, and HOA management.
- Document and Data Collection: The lender's team formally requests all necessary documentation. This includes ordering a preliminary title commitment from the designated title company and sending a condo questionnaire directly to the HOA or management company.
- Thorough Title and Lien Examination: An underwriter meticulously reviews the preliminary title report. They look for any red flags: existing mortgages, judgment liens, tax liens, easements that could affect property use, and breaks in the chain of ownership. If any issues ('clouds') are found, they are identified so the seller and agent can work on resolving them immediately.
- HOA and Condo Document Scrutiny: This step is crucial. The lender analyzes the condo association’s master insurance policy, its annual budget (checking for sufficient reserves), any pending lawsuits against the association, and the ratio of renters to owners. This ensures the entire project is 'warrantable' and meets the strict guidelines set by entities like Fannie Mae and Freddie Mac. (The data, information, or policy mentioned here may vary over time.)
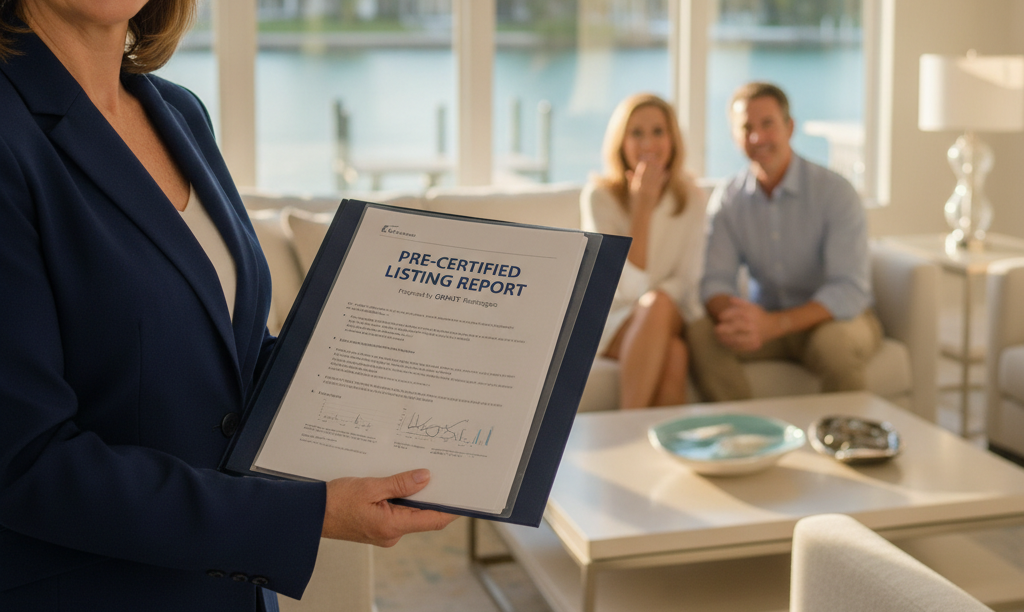
- Issuance of Property Certification: Once the underwriter is satisfied that both the title is clear and the condo project is approved, the lender issues a formal 'Property Certification' or 'Finance-Ready' letter. This document is not a guarantee of a loan but a statement that the property itself has passed underwriting review.
This certification is then provided to the listing agent to be used as a key differentiator in their marketing materials and listing presentation.
How Can This Program Be a Tool in a Miami Listing Presentation?
In a competitive real estate market like Miami, listing agents need to do more than promise professional photos and a spot on the MLS. A pre-certification program is a tangible, high-value service that sets an agent apart and directly addresses a seller’s primary concerns.
When sitting at a seller's kitchen table, an agent can transform the conversation from a typical marketing pitch to a strategic risk-management plan. Instead of saying, 'I will market your home,' they can say, 'My team and I will de-risk the sale of your home.'
Here's how to position it in a listing presentation:
- Lead with the Problem: 'The number one reason real estate deals fall apart after an offer is accepted is due to unexpected title issues or problems with the condo association. It costs sellers time, money, and immense frustration.'
- Present the Solution: 'To prevent this, I've partnered with a lender to offer a Pre-Certified Listing Program. Before we even list your home, we will have their underwriting team fully vet the property's title and HOA status. We solve problems before they become deal-killers.'
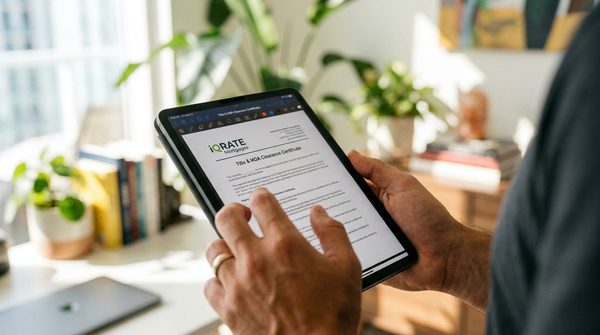
- Showcase the Deliverable: The agent can present a sample of the 'Property Certification' document. This makes the service tangible and shows the seller exactly what they will receive.
- Highlight the Unique Value: 'Most agents wait for problems to arise. My strategy is to eliminate them from the start. This gives you peace of mind, attracts higher-quality buyers, and protects the equity you've built in your home.'
This approach demonstrates a deeper level of expertise and commitment. It shows the agent is a true advisor focused on a successful outcome, not just a salesperson focused on getting a signature.
What is the Impact of a Certified Listing on Offer Quality?
A pre-certified listing doesn't just attract more offers; it attracts better offers. The certification fundamentally changes the buyer's perception of the property, shifting it from an unknown quantity to a known good. This psychological shift has a direct impact on the quality and structure of the offers a seller receives.
First, it leads to cleaner offers with fewer contingencies. A buyer's agent, seeing the property is pre-certified, is more likely to advise their client to submit a strong offer. They know the risk of a title defect or an uncooperative HOA delaying or killing the deal is negligible. This can lead to offers with shortened inspection periods or even waived financing contingencies (when the buyer is very strong), as the property's eligibility is already confirmed.
Second, it often results in stronger offer prices. Buyers are willing to pay for certainty. The confidence that comes with a finance-ready property can motivate them to offer at or above the asking price to secure it. They are competing for a 'sure thing,' and the price reflects that value. The seller is no longer just selling square footage and amenities; they are selling a smooth, predictable transaction.
Finally, it reduces buyer 'flakiness'. The certification process filters out less serious buyers. Those who remain are typically more committed and less likely to use a minor issue as an excuse to back out of the deal. They have been given transparent, upfront information, which builds trust and fosters a more collaborative negotiation environment.
How Does This System Help Defend a Listing Agent's Commission?
The real estate industry is facing increasing pressure on commissions. Sellers often question the value an agent provides, asking, 'Why should I pay a full commission when selling my home seems so easy?' A pre-certification program is a powerful and direct answer to that question.
It allows an agent to move the conversation from cost to value. The agent is no longer just a marketer; they are a risk manager. The value proposition becomes:
- 'My commission reflects the comprehensive service I provide, which includes proactively de-risking your most valuable asset. I invest my resources upfront with my lending partner to ensure your property is certified, which prevents the financial and emotional cost of a failed contract.'
- 'This isn't just about putting a sign in the yard. It's about orchestrating a secure transaction. My program eliminates the common pitfalls that cost sellers thousands in lost time, carrying costs, and legal fees.'
By offering a concrete service that directly protects the seller's bottom line and provides peace of mind, an agent can confidently justify their professional fee. It reframes the commission not as a cost, but as an investment in a successful and predictable outcome.
Why Don't All Lenders Offer to Pre-Certify the Property Itself?
If this program is so beneficial, it's natural to wonder why it isn't standard practice. The reality is that this service requires a business model and operational structure that most traditional lenders don't have.
Here are the main reasons it's not widely available:
- Upfront Cost and Risk: The lender incurs the cost of the underwriting work (time, resources) with no guarantee that they will ultimately finance the loan for the eventual buyer. The buyer may come with their own lender, meaning the pre-certifying lender's investment yields no direct return. (The data, information, or policy mentioned here may vary over time.)
- Reactive Business Model: Most mortgage lenders are structured to be reactive. Their process begins when a purchase contract is submitted. They are not operationally set up to engage proactively on the listing side of a transaction.
- Requires Deep Agent Partnerships: This model only works through strong, trusted relationships between a loan officer and a real estate agent. It requires collaboration and a shared philosophy of client service, which goes beyond a simple transactional relationship.
- Specialized Expertise: Reviewing complex condo documents or resolving title issues requires a high level of underwriting expertise. Not all lenders or loan officers have the in-house talent to confidently and efficiently handle this proactive work. Sellers and agents in Florida looking to gain a competitive edge can explore how a pre-certified listing strategy strengthens their position. Connect with a mortgage strategist who understands how to underwrite the property, not just the buyer, for a smoother, more secure transaction.
Whether you're buying a pre-certified property or starting a traditional search, a solid financing strategy is key. Begin your secure application to get a clear picture of your options and experience a smoother path to homeownership.
Author Bio
David Ghazaryan is the expert mortgage strategist and founder behind iQRATE Mortgages. With a mission to fund home loans that traditional banks won't touch, David specializes in helping clients with unique financial situations, including those recovering from foreclosure or bankruptcy. He expertly crafts smart, strategic, and stress-free mortgages by leveraging a vast network of over 100 lenders to secure competitive rates for investors and homebuyers alike. Praised for exceptional customer service, David has helped hundreds of families with a 97% satisfaction rate, guiding them to the mortgage they deserve.