Reviewed by David Ghazaryan, Mortgage Broker, NMLS 1486726 · iQRATE Mortgages, NMLS 1862492 · Updated November 9, 2026
Quick answer: An Anaheim DSCR loan is a mortgage for a non-owner-occupied rental. It qualifies on the property's monthly rent divided by its full monthly payment (PITIA: principal, interest, property taxes, insurance and HOA dues), not on your tax returns, W-2s or debt-to-income ratio. Three Anaheim facts shape the math:
- Long-term rent only. Anaheim has not issued new short-term rental permits since 2016, so the ratio has to work on a monthly lease, even near the Disneyland Resort.
- The tax resets. Proposition 13 resets the tax bill to your purchase price, usually about 1.1–1.3% in total once local bonds are added. The seller's old bill is not your number.
- The conforming limit is high. Orange County's 2026 one-unit conforming limit is $1,249,125. That matters when you compare a DSCR loan with a conventional investment loan.
iQRATE Mortgages (NMLS 1862492) is licensed in California and compares DSCR lenders, more than 100 on complicated deals.
Start your application · Call or text (702) 766-3744 · Schedule a free consultation
David Ghazaryan: 5.0 stars from 87 reviews on Experience.com (October 2026)
Investor loans are for business purposes only. Not all borrowers qualify. Terms are subject to underwriting and change. Nothing on this page is a rate quote, and it is not a commitment to lend. iQRATE Mortgages LLC NMLS 1862492. David Ghazaryan NMLS 1486726. Equal Housing Opportunity.
What is an Anaheim DSCR loan, and how does the ratio work?
DSCR stands for debt service coverage ratio. The lender takes the property's gross monthly rent and divides it by the full monthly payment:
DSCR = monthly rent ÷ monthly PITIA
- A ratio of 1.00 means the rent covers the payment exactly.
- A ratio of 1.25 means the rent is 25% more than the payment.
- Below 1.00, the rent falls short. Some lenders still lend at a higher rate. Others stop at 1.00.
The ratio uses gross rent. Vacancy, management, turnover and repairs are not in the lender's math, so run your own numbers separately.
You generally don't send tax returns, W-2s or pay stubs. The lender still: - pulls credit, - verifies assets and reserves, - orders an appraisal with a rent analysis, and - reviews the property type and, if you close in an LLC, the entity documents.
A DSCR loan is business-purpose financing for investment property only. You can't live in the home, including one unit of a duplex. If you plan to live there, see our Anaheim mortgage broker page for owner-occupied options.
This page covers how the ratio behaves on an Anaheim rental. For the general program, see our DSCR loans guide.
Anaheim DSCR key facts
| Local factor | Figure or rule | Where it shows up in a DSCR file |
|---|---|---|
| Short-term rentals | No new permits since 2016; only permits that predate the ban can continue | Qualify on long-term (monthly lease) rent |
| Property tax after purchase | Reassessed to your price; usually about 1.1–1.3% in total with local bonds | The tax line of PITIA, based on your price |
| Annual assessed-value increase | At most 2% a year after purchase | Keeps the tax line predictable in later years |
| Supplemental tax bill | Expected after you buy | Cash planning in the first year |
| Special assessments | Possible in the Platinum Triangle and other newer projects | Adds to the tax line and lowers the ratio |
| County documentary transfer tax | $1.10 per $1,000; Anaheim adds no city transfer tax | Cash to close, not PITIA |
| Orange County 2026 conforming limit, one unit | $1,249,125 | Matters when you compare a DSCR loan with conventional |
| Fire hazard zones | Some Anaheim Hills hillside areas are in high fire hazard severity zones | The insurance line of PITIA, and whether coverage can be placed |
| Housing age | Much of Anaheim and Fullerton was built in the 1950s–1970s | Updates, permits and ADU status |
Sources: iQRATE's Anaheim mortgage broker guide (updated October 13, 2026); FHFA conforming loan limits; California Board of Equalization, change in ownership.
Why does an Anaheim DSCR loan have to work on long-term rent?
Anaheim's ordinance prohibits new short-term rentals. Only permits that existed before the 2016 ban can continue. A home a few blocks from the Resort District, or an older listing that once advertised nightly stays, still has to qualify on a monthly lease.
What this means for the ratio:
- Ignore nightly income in the listing. Past vacation-rental revenue is not the rent a DSCR lender will use for a new Anaheim owner.
- Use the appraiser's long-term market rent. That is the number that decides the file. Many DSCR lenders use long-term rent only.
- Treat a grandfathered permit as a special case. If a seller claims a pre-2016 permit, confirm with the City of Anaheim whether it survives a sale before you count on it. Then ask the lender in writing whether it will use that income at all.
- Check the city first. Anaheim's ordinance covers Anaheim city limits, including Anaheim Hills; check the rules of the city where the property sits.
There is an upside to a long-term-only market. The rent the appraiser uses is the rent you can actually charge under a lease, so the ratio is less likely to rest on a projection.
How does Proposition 13 change the payment side of an Anaheim ratio?
Taxes are the line investors most often get wrong in California. Under Proposition 13, a home is reassessed to its purchase price when it sells. The tax is 1% plus local voter-approved levies, usually about 1.1–1.3% of the price in total. After that, assessed value rises at most 2% a year. The Board of Equalization explains the change-in-ownership rules.
| Situation | Which tax number to use in PITIA | What to watch |
|---|---|---|
| The seller owned the home for years | Your purchase price times the local total, not the seller's bill | The seller's bill may reflect a much older assessment |
| A newer project, including parts of the Platinum Triangle | Your reassessed tax plus any special assessment | Special assessments sit on the tax bill and count in the payment |
| The first year after closing | The regular bill plus a supplemental bill | Plan cash for the supplemental bill |
| Later years | The prior assessed value plus at most 2% a year | A steadier tax line helps when you plan a future refinance |
How to use this: before you write an offer, ask for the current tax bill so you can see any special assessments. Then build the tax line yourself from your own price. If the ratio only clears 1.00 on the seller's bill, it may not clear once the bill resets.
How do insurance and HOA dues affect an Anaheim ratio?
Insurance and HOA dues go straight into PITIA, so they move the ratio dollar for dollar.
- Anaheim Hills. Hillside homes east of the 55 and 91 freeways often come with views, HOAs and wildfire insurance questions. Some areas are in high fire hazard severity zones, which can make insurance harder to place. Get a written landlord (dwelling fire) policy quote before you remove contingencies.
- Condos near the Resort District and the Platinum Triangle. HOA dues count in the payment. Condos may need a project review. A condo with high dues can produce a lower ratio than a house at a similar price.
- Older homes. Much of West and Central Anaheim and Fullerton was built in the 1950s–1970s. Updates and permits matter to the appraisal and to the insurance quote, so ask for both early.
Can ADU rent help an Anaheim DSCR loan?
Sometimes. Some programs count rent from an existing permitted ADU. We confirm the permit before counting it.
On a property with a permitted ADU, ask the lender whether the ADU rent will be added to the main home's rent in the ratio. Because so much of Anaheim's housing dates from the 1950s–1970s, lot size and permit history are worth checking before you offer.
Areas and ZIPs we lend in around Anaheim
iQRATE Mortgages arranges DSCR loans on rentals across Anaheim and North Orange County. The right-hand column lists sourced items to check in each area. It does not describe our past files.
| Area | ZIPs | What to check before running the ratio |
|---|---|---|
| Anaheim Hills | 92807, 92808 | HOA dues and fire-zone insurance in PITIA; Anaheim's short-term rental ban applies |
| West Anaheim | 92801, 92804 | Older housing stock; permits and updates; long-term rent only |
| The Colony and Downtown Anaheim | 92805 | Older homes; ADU permit status; long-term rent only |
| Platinum Triangle | 92806 | Special assessments on newer projects; possible condo project review |
| Fullerton | 92831, 92833, 92835 | Anaheim's ordinance covers Anaheim city limits; check the rules of the city where the property sits; Cal State Fullerton rental demand |
| Orange | 92865, 92866, 92867 | Anaheim's ordinance covers Anaheim city limits; check the rules of the city where the property sits, and the tax bill |
| Garden Grove | 92840, 92841, 92843 | Anaheim's ordinance covers Anaheim city limits; check the rules of the city where the property sits |
| Buena Park | 90620, 90621 | Anaheim's ordinance covers Anaheim city limits; check the rules of the city where the property sits |
Placentia and Yorba Linda sit next door. Yorba Linda's larger homes may mean larger loan amounts, which narrows the list of lenders.
Own more than 10 rentals? See our guides to financing more than 10 rentals in Anaheim and San Jose and financing over 10 rentals in Anaheim and Sacramento.
Does Orange County's $1,249,125 conforming limit matter for a DSCR loan?
It matters mostly when you compare options. Orange County's 2026 one-unit conforming limit is $1,249,125, among the highest in the country (FHFA 2026 announcement).
- Conventional investment loans stop at the conforming limit. Above it, a conventional loan becomes jumbo.
- DSCR lenders set their own loan sizes. As an example, one lender we place DSCR loans with offered loans from $75,000 to $5,000,000 as of October 2026: up to $2.5 million at a 720+ credit score and up to $5 million at 800+. Very small and very large loans narrow the list of lenders.
So in Anaheim, a rental above $1,249,125 doesn't need a separate "jumbo" decision on a DSCR file. It does mean fewer lenders, and shopping matters more.
How do lenders decide what an Anaheim rental rents for?
The rent figure is the most important input in a DSCR file.
- Vacant home: the appraiser sets market rent. On a single-family home this usually comes on Fannie Mae Form 1007, the Single-Family Comparable Rent Schedule. The redesigned agency appraisal report (UAD 3.6) is required for new agency appraisals submitted on or after November 2, 2026, and moves market rent into the report itself. DSCR lenders set their own requirements, so you may see either format.
- Leased home: some lenders use the signed lease, some use the appraiser's market rent, and some use the lower of the two. Ask which rule applies before you pay for the appraisal.
- 2–4 units: the ratio uses the combined rent from all units against one PITIA. Provide every lease.
From David: "You can close a DSCR deal with just about any problem as long as you put a bit more down. That's why we always tell clients the rate and down payment are tentative until the appraiser's value and rent come in."
How much can a low rent opinion move the ratio?
| Ratio you expected | Rent comes in one-twentieth low | Rent comes in one-tenth low |
|---|---|---|
| 1.25 | 1.19 | 1.13 |
| 1.20 | 1.14 | 1.08 |
| 1.10 | 1.05 | 0.99 |
| 1.00 | 0.95 | 0.90 |
This is arithmetic, not a forecast. Your taxes, insurance and HOA dues don't fall when the rent opinion does, so a low rent hits the ratio directly. A deal that just clears 1.00 on the seller's rent can fall short once the appraiser's figure comes back.
Run the ratio on your Anaheim property
The ratio is the total monthly rent (all units, or the main home plus a permitted ADU) divided by the total monthly payment: principal and interest, property tax at your purchase price, landlord insurance, any flood insurance, HOA dues and any special assessments. No rate is assumed. The result is a starting point, not a quote and not a commitment to lend. For loan-to-value and cash-out math, see our mortgage calculators. For short explainers, see our videos.
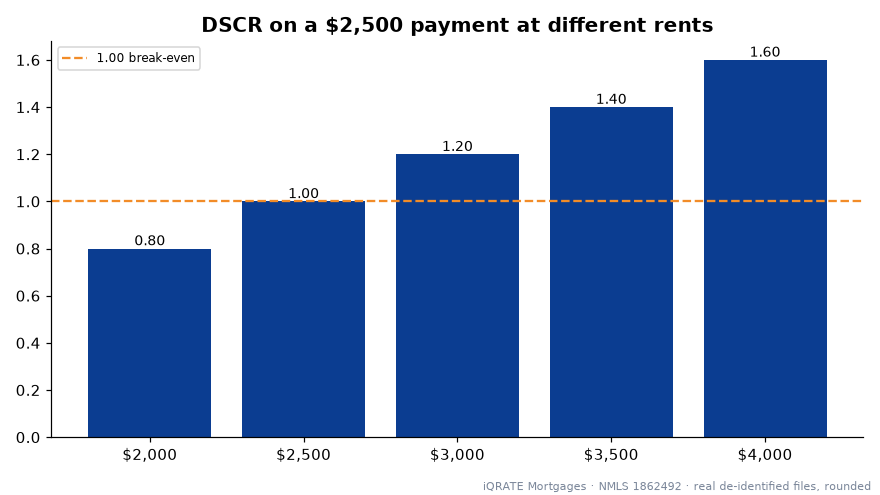
Rent divided by the full payment. 1.00 means the rent equals the payment.
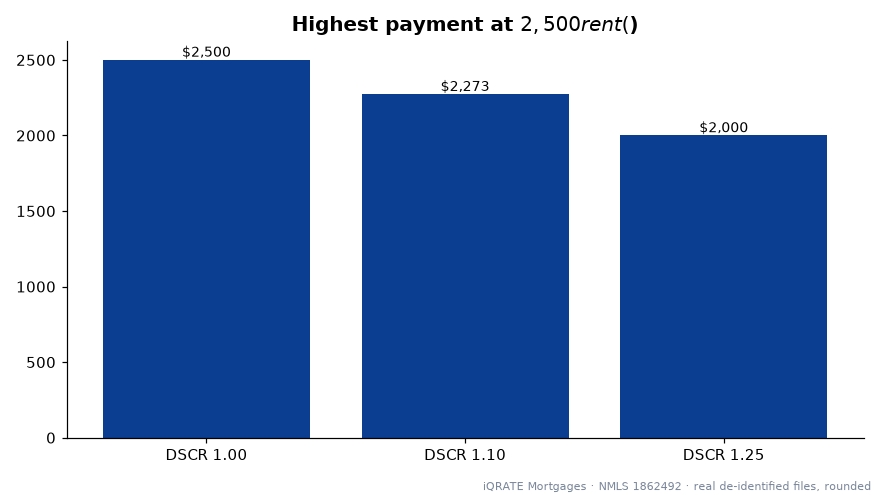
The most PITIA a rent can carry is the rent divided by the target ratio.
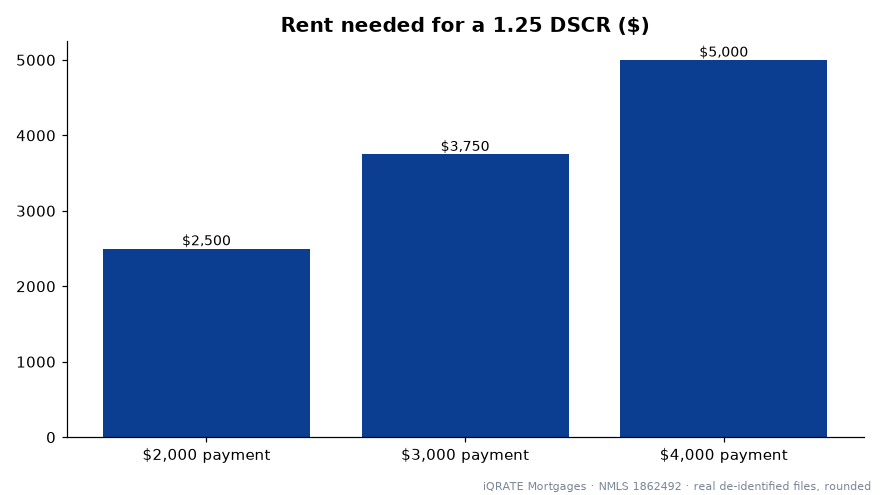
The rent you need is the full payment times the target ratio.
What are your options if an Anaheim ratio comes in below 1.00?
You have more choices than walking away, though walking away is sometimes right.
- Put more money down. A smaller loan lowers the payment and raises the ratio.
- Use a lender that accepts a lower ratio. One lender we place loans with accepted ratios as low as 0.75 as of October 2026, at a higher rate. Some lenders stop at 1.00.
- Consider a no-ratio program. See no-ratio DSCR loans. The rate is higher, so reaching 1.00 is usually the better route if you can.
- Ask about interest-only. Some lenders offer it. It raises the ratio, but you pay down no principal during that period.
- Buy down the rate. It costs cash at closing. Seller or builder credits can sometimes pay for it.
- Reduce the payment lines. A different insurance quote, or a home with lower HOA dues or no special assessment, moves the ratio too.
- Pick a different property, or walk away if the deal only works on optimistic rent.
What do DSCR terms look like from a lender we place loans with?
The terms below are example terms from one DSCR lender we place loans with, as of October 2026. Every lender sets its own grid, and grids change often. That is why we compare.
| Term | Example (one lender, October 2026) | How lenders differ |
|---|---|---|
| Minimum DSCR | 0.75 | Some lenders stop at 1.00 |
| Ratio of 0.75 to 0.99 | Allowed at a higher rate | The rate add-on differs by lender |
| Minimum credit score | 680 | Minimums differ by lender |
| Loan amounts | $75,000 to $5,000,000 | Very small and very large loans narrow the list |
| Larger loan sizes | Up to $2.5 million at 720+; up to $5 million at 800+ | Each lender has its own credit and size grid |
| Reserves | 12 months of PITIA; cash-out proceeds can count on a refinance | Some lenders ask for less |
| Prepayment penalty | 5, 4, 3, 2 or 1 year, or none; our clients pick 2 years most often | Each choice prices differently |
| LLC vesting | Allowed by some of our lenders, always with a personal guarantee | Entity rules differ |
| First-time investors | Some lenders allow it, with extra occupancy review | Ask several lenders |
| Cash-out seasoning | At least 6 months on title at most lenders; some non-QM lenders allow cash-out right after an all-cash purchase | Pricing for exceptions differs |
Example terms only. Not every lender offers every option. Terms depend on credit, property and lender approval. This is not a rate quote or a commitment to lend.
We don't publish DSCR rates because pricing changes daily. What moves it most: - your credit score and equity, - the ratio, - the prepayment penalty you choose, and - loan size, property type, interest-only and cash-out.
Our own broker compensation is charged separately from the lender's rate.
How should an Anaheim investor think about the prepayment penalty?
A DSCR loan can carry a prepayment penalty because it is business-purpose credit. Regulation Z limits prepayment penalties on most consumer mortgages, but credit extended primarily for a business purpose, such as a loan on a non-owner-occupied rental held as an investment, is exempt.
You usually choose the length. With the example lender above, the options run from 5 years down to none, and each prices differently. Match the penalty to your exit plan. Before you choose, ask:
- Does it apply to a sale as well as a refinance?
- Can you prepay part of the balance each year without a penalty?
- How is the penalty calculated?
Get each answer in writing on the term sheet.
From David: "One thing being a real estate investor has taught me is that getting a loan approved and making a good investment are two different things. ... They focus on the interest rate. I look at the entire transaction: cash invested, monthly carrying costs, reserves, prepayment penalties, and the exit strategy. A loan that saves you money today can become expensive if you need to refinance or sell before a prepayment penalty expires."
Why do investors' tax returns understate what an Anaheim rental earns?
Rental income and expenses are reported on Schedule E. IRS Publication 527 and Tax Topic 414 explain the expenses a landlord can deduct, including depreciation. Those deductions can make a profitable rental look thin on a tax return, which is exactly the problem a full-documentation loan runs into. A DSCR loan sidesteps it by looking at the property's rent against its payment instead.
David is a real estate investor himself and has prepared more than 6,000 tax returns. Investor files get read the way an owner reads them: rent, taxes, insurance and HOA dues first, then the loan.
If your documented income carries the payment easily, a conventional investment loan may cost less. See the comparison below.
Can you close an Anaheim DSCR loan in an LLC?
Yes, with some of our lenders, and a personal guarantee is always required by the lenders we use for LLC closings. Expect to provide:
- articles of organization,
- the operating agreement,
- the EIN letter (see the IRS EIN page), and
- proof the entity is in good standing with the California Secretary of State.
Set up the LLC before closing, not during underwriting. If the purchase contract is in your personal name, ask early whether the lender accepts an assignment to the LLC. Talk with your attorney and tax adviser about whether an LLC fits you. This is not legal or tax advice.
How does a DSCR cash-out refinance work on an Anaheim rental?
A cash-out refinance replaces your loan with a larger one and pays you the difference. The new, larger payment still has to clear the lender's ratio floor. The more cash you take, the lower the ratio.
- Seasoning: at least 6 months on title at most lenders. Some of our non-QM DSCR lenders allow cash-out right after an all-cash purchase, if you document the funds you used to buy.
- Reserves: at the example lender above, cash-out proceeds can count toward the reserve requirement.
- Your current loan: check for a prepayment penalty before you refinance.
Can you use a DSCR loan in a 1031 exchange into Anaheim?
Yes. A DSCR loan can finance the replacement property, and its lighter income documentation helps on the exchange timeline. You generally have 45 days to identify the replacement and 180 days to close (IRS like-kind exchange tips).
Give us your sale date and both deadlines on day one. Get the ratio reviewed before you identify properties, because the appraisal is usually the longest step. Coordinate with your qualified intermediary and tax adviser. This is not tax advice.
Which Anaheim property types fit a DSCR loan?
| Property type | DSCR fit | What to check in Anaheim |
|---|---|---|
| Single-family home | The most widely accepted | Prop 13 tax at your price; insurance in fire zones |
| Townhome | Widely accepted | HOA dues count in PITIA |
| Warrantable condo | Widely accepted | Possible project review, HOA dues, special assessments |
| Non-warrantable condo | Fewer lenders; usually more down | Tell us early so we shop the right lenders |
| 2–4 units | Combined rent against one PITIA | Every lease; the rules of the city where the property sits |
| Home with a permitted ADU | ADU rent may count | Permit confirmed before counting |
| 5–8 units | Some lenders offer residential-style DSCR programs | See DSCR loans for 5-8 unit buildings |
Is a DSCR loan or a conventional loan better for an Anaheim rental?
| Question | DSCR loan | Conventional investment loan |
|---|---|---|
| How you qualify | The property's rent against PITIA | Your income and debt-to-income ratio, with tax returns |
| Loan size in Orange County | Set by each DSCR lender | Up to $1,249,125 for one unit; jumbo above that |
| Number of financed properties | Set by each lender | No more than 10 financed properties |
| Title in an LLC | Allowed by some lenders, with a personal guarantee | Generally in your personal name |
| Prepayment penalty | Common; you choose the length or none | None |
| Pricing | Usually higher | Usually lower if you qualify |
Choose conventional if your documented income carries the payment, you're under the property limit and you don't need an LLC. It's usually cheaper. Choose DSCR if your returns understate your income, your debt-to-income ratio is maxed out, you're past the property limit, or you want an entity.
How do you choose a DSCR lender or broker for an Anaheim rental?
There is no official ranking of DSCR lenders. The best one for an Anaheim deal is the one whose rules fit the property. Ask every lender or broker:
- What is your minimum DSCR, and which rent figure do you use: the lease, the appraiser's market rent, or the lower of the two?
- Will you count rent from a permitted ADU?
- Do you lend on this condo project, and does it need a project review?
- Can I close in an LLC, and what guarantee do you require?
- What prepayment penalty options do you offer, and does each apply to a sale as well as a refinance?
- How many months of reserves do I need, and can cash-out proceeds count?
- What is your NMLS number, and are you licensed in California?
If a lender can't answer in writing, keep shopping.
How we shop: DSCR loans aren't standardized, so the same property can get a "no" from one lender and a good offer from another. We build your scenario once, ask DSCR lenders for their terms on your actual file, and show you the trade-offs before you commit.
From David: "On a complicated deal, I'll personally email more than 100 lenders and sift through what comes back. It's a lot of work, so I do it once the client is committed, with a full application and documents in hand."
What do real iQRATE DSCR files show? (Las Vegas files and one Midwest rental owned by a Nevada investor; none are Anaheim closings)
The files below are real iQRATE DSCR loans: Las Vegas files and one Midwest rental owned by a Nevada investor (none are Anaheim closings). We show them because the ratio rules work the same way on a California rental. Names and details are removed, and figures are rounded.
Las Vegas file: the builder's lender said no
A client came to us after the financing on a brand-new Las Vegas investment property fell apart. To get the builder's incentives, the client was required to apply through the builder's preferred lender. The client did, and that lender denied the loan. Because the client had satisfied the builder's requirement, the builder agreed to honor the incentives with outside financing.
We arranged a DSCR mortgage using the property's rental income and applied the incentives toward a rate buydown. The ratio was approximately 1.00, with rent covering the full monthly qualifying payment. We closed in less than three weeks.
From David: "The lesson I took from that transaction is that a lender's denial doesn't necessarily mean a good investment opportunity is dead. Sometimes the solution is understanding the purchase contract, preserving the buyer's negotiating position, and choosing a financing program that fits the actual investment."
Las Vegas file: rent that covered only 83% of the payment
In fall 2023, an investor wanted to pull cash out of a Las Vegas condo rental appraised at $280,000. The rent covered only about 83% of the new payment, a DSCR of 0.83. Low leverage did the heavy lifting, and the cash-out refinance funded in fall 2023.
Las Vegas file: two condos below 1.00, closed the same day
In fall 2024, a Las Vegas investor with five or more rentals bought two condos in the same southwest Las Vegas complex and closed both on the same day. The appraiser's rent pushed the ratio down to 0.82, below 1.0. The loan stayed approved because the down payment and reserves carried it.
Las Vegas file: a 200% debt ratio that did not matter
In fall 2023, a buyer with strong credit wanted a Las Vegas rental home near $420,000. The buyer's income came mostly from capital gains and dividends. Run through a full-doc loan, the debt ratio came out above 200%. On the home's rent, the DSCR was 1.18, and the purchase closed in fall 2023.
Las Vegas file: $130,000 low, and the loan still went up
In 2024, an investor was refinancing a rental owned in an LLC. We expected a $1 million value, and the appraisal came in at $870,000. The loan started small relative to the value, so there was room to spare. We raised it from $400,000 to $435,000, and final pricing improved.
Las Vegas file: an investor from overseas
In spring 2023, a past client referred a foreign-national investor who wanted a Las Vegas rental home near $435,000. The buyer's funds sat in overseas bank accounts. We used a DSCR loan that qualifies on the home's rent and documented the funds with the overseas statements. The purchase closed in spring 2023, and pricing improved between the first and the final approval.
| Las Vegas file | What nearly stopped it | What decided it | The Anaheim takeaway |
|---|---|---|---|
| New construction | The builder's lender denied the loan | The client had met the builder's requirement | Keep a written record of every step a builder or seller requires |
| Condo cash-out | DSCR of 0.83 | Low leverage | Know how much loan the long-term rent can carry |
| Two condos | Appraiser's rent pushed the ratio to 0.82 | Down payment and reserves | Run the ratio on a lower rent before you offer |
| Investment-income buyer | Full-doc debt ratio above 200% | Qualifying on rent at 1.18 | Don't force a full-doc loan when the property qualifies on its own |
| LLC refinance | Value came in $130,000 low | Room between the loan and the value | Equity can absorb a low appraisal |
| Foreign national | Funds in overseas accounts | Documented statements | Start the funds paper trail early |
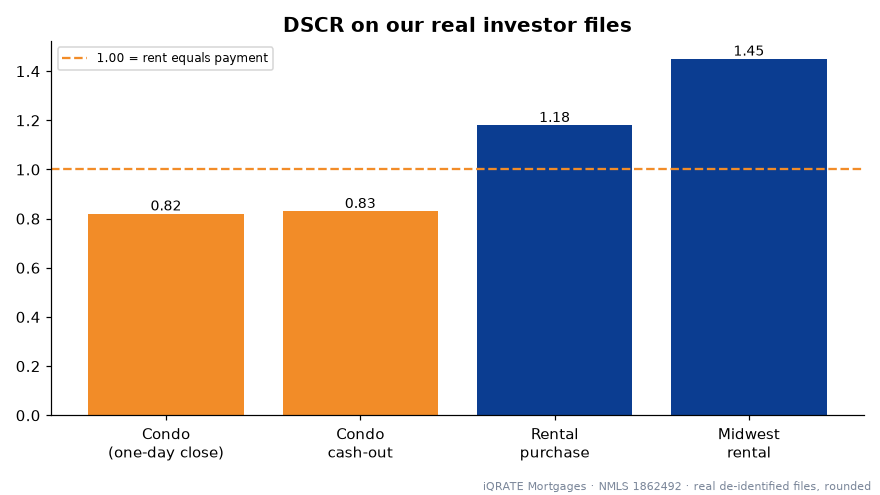
Ratios on closed iQRATE DSCR files. Two closed with rent below the payment.
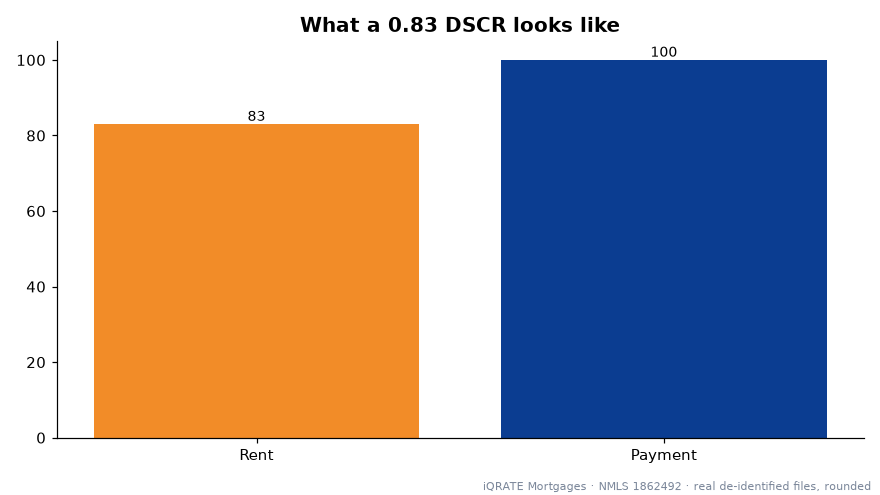
The Las Vegas condo cash-out: rent paid 83 cents of every payment dollar, and the loan still closed.
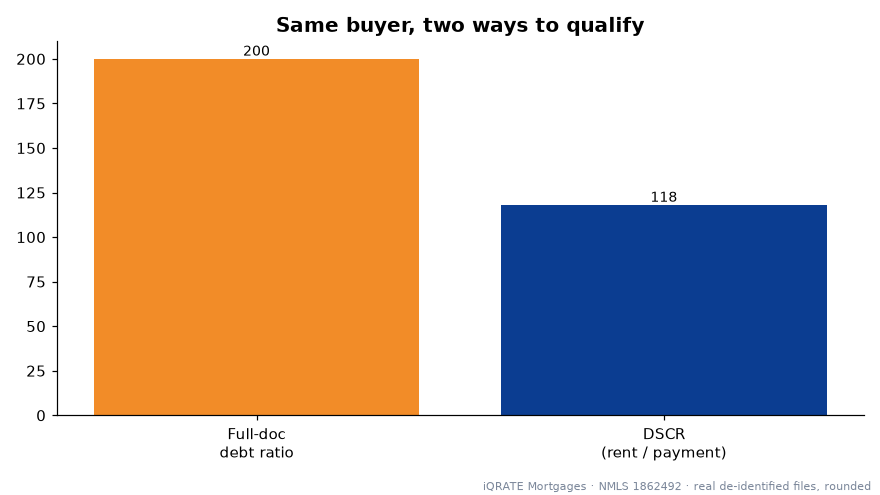
Full-doc math said no. On rent, the property covered itself.
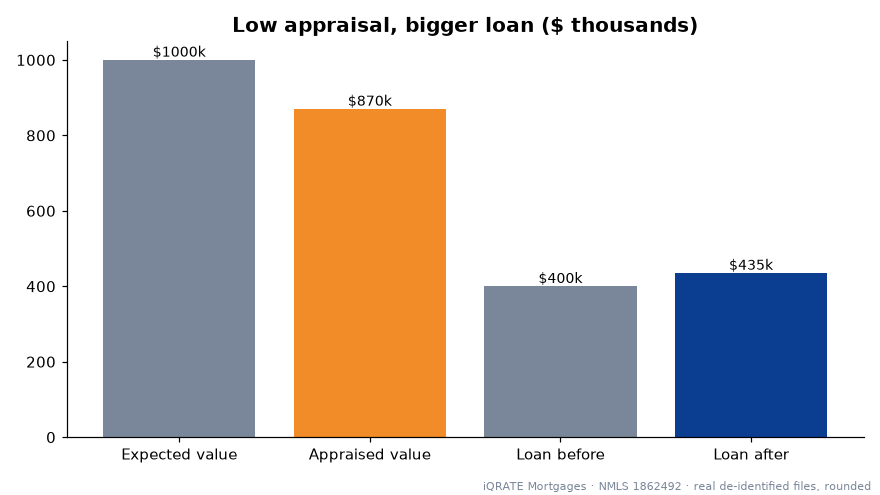
The value came in $130,000 low. The loan still went up.
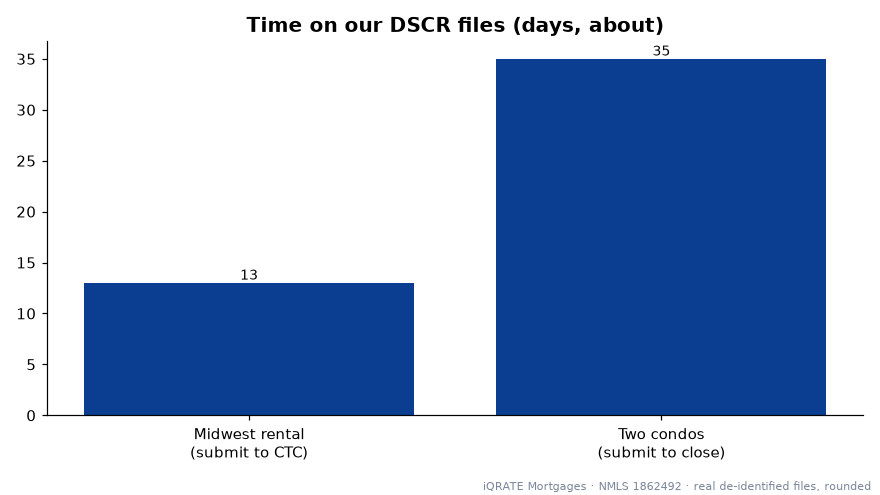
A clean small-balance file moved in 13 days. A two-condo project review took about five weeks.
Real iQRATE files: Las Vegas files and one Midwest rental owned by a Nevada investor (none are Anaheim closings), de-identified and rounded. Past results do not guarantee future outcomes. All loans are subject to credit approval.
How does an Anaheim DSCR file move through iQRATE?
- Send the scenario: address, price, expected long-term rent, the current tax bill, an insurance quote, HOA dues and how you'll hold title.
- We confirm the city and run the ratio conservatively. We use the full payment, the tax at your price and a realistic rent.
- We shop DSCR lenders for ratio floor, rate, prepayment options, reserves and how they count rent. We run the full search once your application and documents are in.
- Application and credit. No tax-return package.
- Appraisal with rent analysis. Ordered right away. It is usually the longest step.
- Underwriting: assets, reserves, insurance, entity documents and the final ratio.
- Clear to close and funding, with local escrow and title.
iQRATE Mortgages is based at 6360 S Rainbow Blvd, Suite 101, Las Vegas, NV 89118, and is licensed in California, Nevada, Texas and Florida.
The most common delays are a low appraised rent, a late insurance quote and LLC paperwork that isn't ready.
What documents do you need?
| Item | Purchase | Refinance | In an LLC |
|---|---|---|---|
| Photo ID and credit authorization | Yes | Yes | Yes, for each guarantor |
| Purchase contract | Yes | No | In the LLC's name, or an assignment the lender accepts |
| Lease or rent evidence | Lease if occupied; otherwise the appraiser's rent | Current lease and proof of rent received | Same as the transaction type |
| Bank or brokerage statements | Funds to close and reserves | Reserves | LLC or personal accounts |
| Current tax bill | To spot special assessments | Current bill | Same |
| Insurance | Landlord (dwelling fire) policy quote | Current policy | Policy naming the LLC as insured |
| HOA information | Contact and dues; condo questionnaire for condos | Current dues | Same |
| ADU permit | If counting ADU rent | If counting ADU rent | Same |
| Entity documents | Not needed in your own name | Only if vested in an entity | Articles, operating agreement, EIN letter, California good standing |
Tax returns, W-2s and pay stubs are generally not required. Lenders may ask for more. For comparison, Fannie Mae publishes its own reserve requirements for agency loans; DSCR lenders set their own.
What do clients say about iQRATE Mortgages?
These are real reviews of iQRATE Mortgages, quoted word for word. The reviewers are not identified as Anaheim clients, and the reviews describe the company overall, not a promise about your loan.
"Andrei and David were so great! They're helpful and communicated everything with me through the whole process. I am so pleased and look forward to using iqrate for my future investment properties. 10/10 Will be reccomending to friends."
— Kassandra Arthur, review on Google
"David and Andrei and team were very knowledgeable and really helped in the whole process. Even though the economy is going through a rough time they were able to explain every detail and really looked out for our best interest! I would highly recommend their team as they will find a way to get it done!"
— Lydia Z. (Menifee, CA), 5-star review on Yelp
Read more of David's reviews on Experience.com.
Anaheim DSCR loan FAQs
Can I qualify an Anaheim DSCR loan on vacation-rental income near the Disneyland Resort?
Generally no. Anaheim prohibits new short-term rentals, and only permits that predate the 2016 ban can continue. Expect the lender to qualify the file on long-term market rent. If a seller claims a pre-2016 permit, confirm its status with the city and ask the lender in writing whether that income counts.
Which tax number goes into the payment on an Anaheim DSCR purchase?
The tax on your purchase price, not the seller's bill. Proposition 13 reassesses the home when it sells. The total is usually about 1.1–1.3% of the price with local bonds, plus any special assessment on the bill.
Does Anaheim's transfer tax affect my DSCR ratio?
No. Orange County's documentary transfer tax of $1.10 per $1,000 is a one-time closing cost, and Anaheim adds no city transfer tax. It affects your cash to close and reserves, not PITIA.
How do Platinum Triangle special assessments affect a DSCR loan?
Special assessments on the tax bill count in the payment and lower the ratio. Ask for the current tax bill before you offer, and enter the assessment in the calculator's special-assessments line.
Will fire-zone insurance in Anaheim Hills hurt my ratio?
It can. Some hillside areas are in high fire hazard severity zones, which can make insurance harder to place. Whatever the premium is, it goes into PITIA. Get a written landlord policy quote before you remove contingencies.
Can rent from an ADU on an Anaheim lot count toward the ratio?
Sometimes, if the ADU is permitted and the lender allows it. We confirm the permit before counting it.
Do I need a jumbo loan for an Anaheim rental above $1,249,125?
Not on a DSCR loan. The $1,249,125 Orange County conforming limit applies to conventional loans. DSCR lenders set their own loan sizes; one lender we place loans with offered $75,000 to $5,000,000 as of October 2026. Larger balances narrow the list of lenders.
Does Anaheim's short-term rental ban apply in Fullerton, Orange or Garden Grove?
Anaheim's ordinance covers Anaheim city limits, including Anaheim Hills. Fullerton, Orange, Garden Grove and Buena Park are separate cities, so check the rules of the city where the property sits before you count on any rental income.
What rent figure will the lender use on an Anaheim rental?
Usually the appraiser's market rent on a vacant home. On a leased home, some lenders use the lease, some use the appraiser's figure, and some use the lower of the two. Ask before you pay for the appraisal.
What if the appraiser's rent makes my ratio fall below 1.00?
You can put more down, move to a lender that accepts a lower ratio at a higher rate, look at interest-only where offered, or buy down the rate. If the deal only works on optimistic rent, walking away may be right.
Do I need tax returns for an Anaheim DSCR loan?
Generally no. Tax returns, W-2s and pay stubs are usually not required. The lender still checks credit, assets, reserves, the appraisal and the property.
Can I hold an Anaheim rental in an LLC with a DSCR loan?
Yes, with some of our lenders, always with a personal guarantee. Expect to provide the articles of organization, operating agreement, EIN letter and proof of California good standing. Set up the LLC before closing.
Can I live in an Anaheim home I buy with a DSCR loan?
No. A DSCR loan is business-purpose financing for non-owner-occupied property only. If you plan to live in the home, see our Anaheim mortgage broker page.
How long before I can do a cash-out refinance on an Anaheim rental?
At least 6 months on title at most lenders. Some of our non-QM DSCR lenders allow cash-out right after an all-cash purchase if you document the funds you used to buy.
Can I buy an Anaheim rental with a DSCR loan in a 1031 exchange?
Yes. You generally have 45 days to identify the replacement and 180 days to close. Tell us the deadlines on day one, and coordinate with your qualified intermediary and tax adviser.
Why doesn't this page list DSCR rates?
Pricing changes daily and moves with credit, equity, the ratio, the prepayment option, loan size and property type. Terms are confirmed in writing on your actual file.
Is iQRATE Mortgages licensed to arrange DSCR loans in California?
Yes. iQRATE Mortgages (NMLS 1862492) is licensed in California, Nevada, Texas and Florida. David Ghazaryan's individual NMLS number is 1486726. Both can be verified on NMLS Consumer Access.
Get started on your Anaheim rental
Send us the address, price, expected long-term rent, tax bill, insurance quote and HOA dues. We'll run the ratio, shop DSCR lenders and tell you plainly whether the deal works.
Start your application · Call or text (702) 766-3744 · Schedule a free consultation
Related: DSCR loans · No-ratio DSCR loans · Anaheim mortgage broker · California mortgage broker · Calculators · Videos
Related iQRATE pages
- DSCR loans in Sacramento and the Inland Empire
- Investors
- Portfolio loans
- Serial investor loans
- Foreign national DSCR loans
- Blanket loans
- Non-QM loans
- Bank statement
- P&L statement loans
- Self employed
- Refinance
- Closing costs by state
- Reviews
- Guarantees
- About
- FAQ
- Jumbo
- FHA loans
- VA loans
- First time home buyer
- Blog
Other California cities iQRATE lends in
- Bakersfield
- Beverly Hills
- Carlsbad
- Coachella Valley
- Fremont
- Fresno
- Irvine
- Long Beach
- Los Angeles
- Modesto
- Oakland
- Oceanside
- Pasadena
- Riverside
- Roseville
- Sacramento
- San Diego
- San Francisco
- San Jose
- Stockton
- Temecula
Check your DSCR ratio
Enter the rent and each part of the monthly payment for an Anaheim rental. The tool divides total rent by total PITIA. It does not use interest rates, quote a payment or approve a loan.
Each lender sets its own minimum ratio and decides which rent it counts (lease or appraiser market rent). This is a starting estimate, not a commitment to lend.
Talk with iQRATE about this loan
Apply now or contact us to get a quote on the property you have in mind. You can also schedule a call or book a call with David at (702) 766-3744. This is not a commitment to lend.
Sources
- iQRATE Mortgages, Anaheim mortgage broker guide, updated October 13, 2026: Anaheim short-term rental ordinance (no new permits since 2016), Orange County transfer tax and no Anaheim city transfer tax, Proposition 13 tax range, special assessments, Anaheim Hills fire hazard zones, housing age, ADU permits, and areas and ZIPs.
- FHFA, conforming loan limits and FHFA 2026 conforming loan limit announcement: Orange County one-unit limit of $1,249,125.
- California Board of Equalization, change in ownership: Proposition 13 reassessment on sale.
- iQRATE Mortgages, DSCR loans, updated October 30, 2026: example lender terms (October 2026), the Form 1007 and UAD 3.6 notes, cash-out seasoning, the business-purpose exemption, and the client files (Las Vegas files and one Midwest rental owned by a Nevada investor).
- IRS, like-kind exchanges: 45-day and 180-day periods.
- IRS, Schedule E, Publication 527 and Tax Topic 414: reporting rental income and expenses.
- IRS, employer identification number and California Secretary of State: LLC documents.
- Fannie Mae Selling Guide B3-4.1-01, minimum reserve requirements.
Licensing and disclosures
iQRATE Mortgages LLC · NMLS 1862492 · 6360 S Rainbow Blvd Ste 101, Las Vegas, NV 89118 · Licensed in Nevada, California, Texas and Florida · David Ghazaryan, Mortgage Broker, NMLS 1486726 · (702) 766-3744.
DSCR loans are business-purpose loans for non-owner-occupied investment property, not for a home you or your family will live in. Investor loans are for business purposes only. Not all borrowers qualify. Lender terms on this page are examples from a specific lender as of October 2026, and ratio examples are arithmetic only. None is a rate quote or loan offer, and nothing on this page is a commitment to lend. Programs are subject to credit, property and lender approval, and terms can change without notice. Client files shown are de-identified Las Vegas files and one Midwest rental owned by a Nevada investor (none are Anaheim closings). Past results do not guarantee future outcomes. Reviews describe iQRATE Mortgages overall. Nothing on this page is tax or legal advice. Equal Housing Opportunity. iQRATE Mortgages LLC NMLS 1862492. David Ghazaryan NMLS 1486726.






