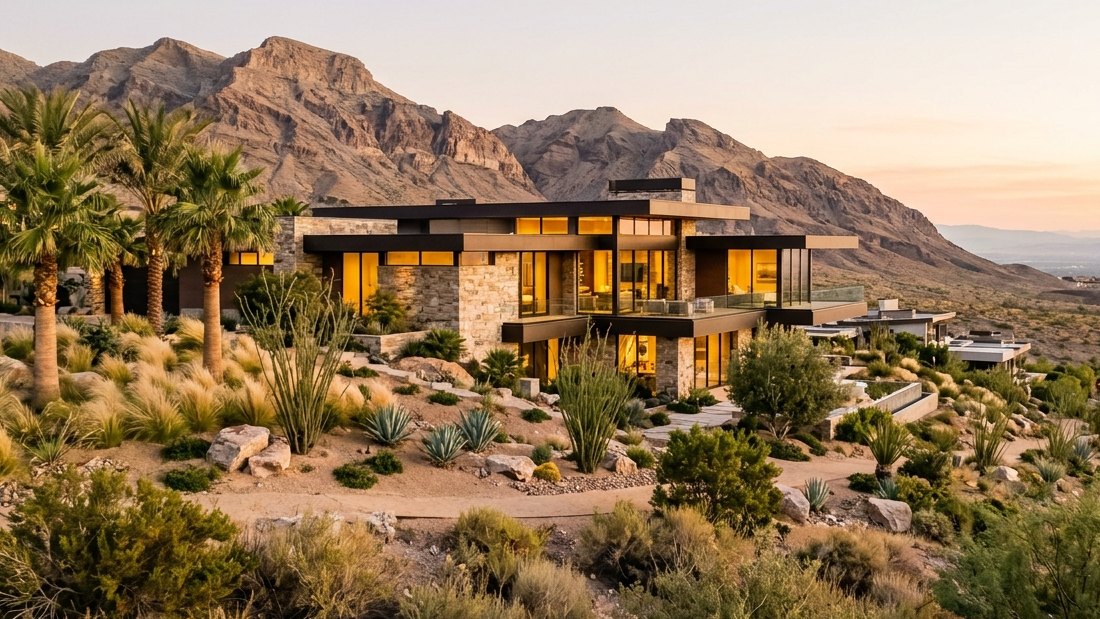
MacDonald Highlands is in Henderson, inside Clark County, so your loan is jumbo if it is larger than the one-unit conforming limit FHFA sets for the county. Nevada has no high-balance tier, so the line is clean. If your loan is jumbo, the appraisal, every layer of dues, your income documents and your choice of lender shape the outcome.
This guide covers one community: a finished home in MacDonald Highlands, whether you are buying it or refinancing the one you own. If you are comparing several Henderson communities, our Henderson luxury jumbo guide for Ascaya, Anthem and Lake Las Vegas covers the wider picture. Here we focus on what a MacDonald Highlands loan file has to get through.
The jumbo line in MacDonald Highlands
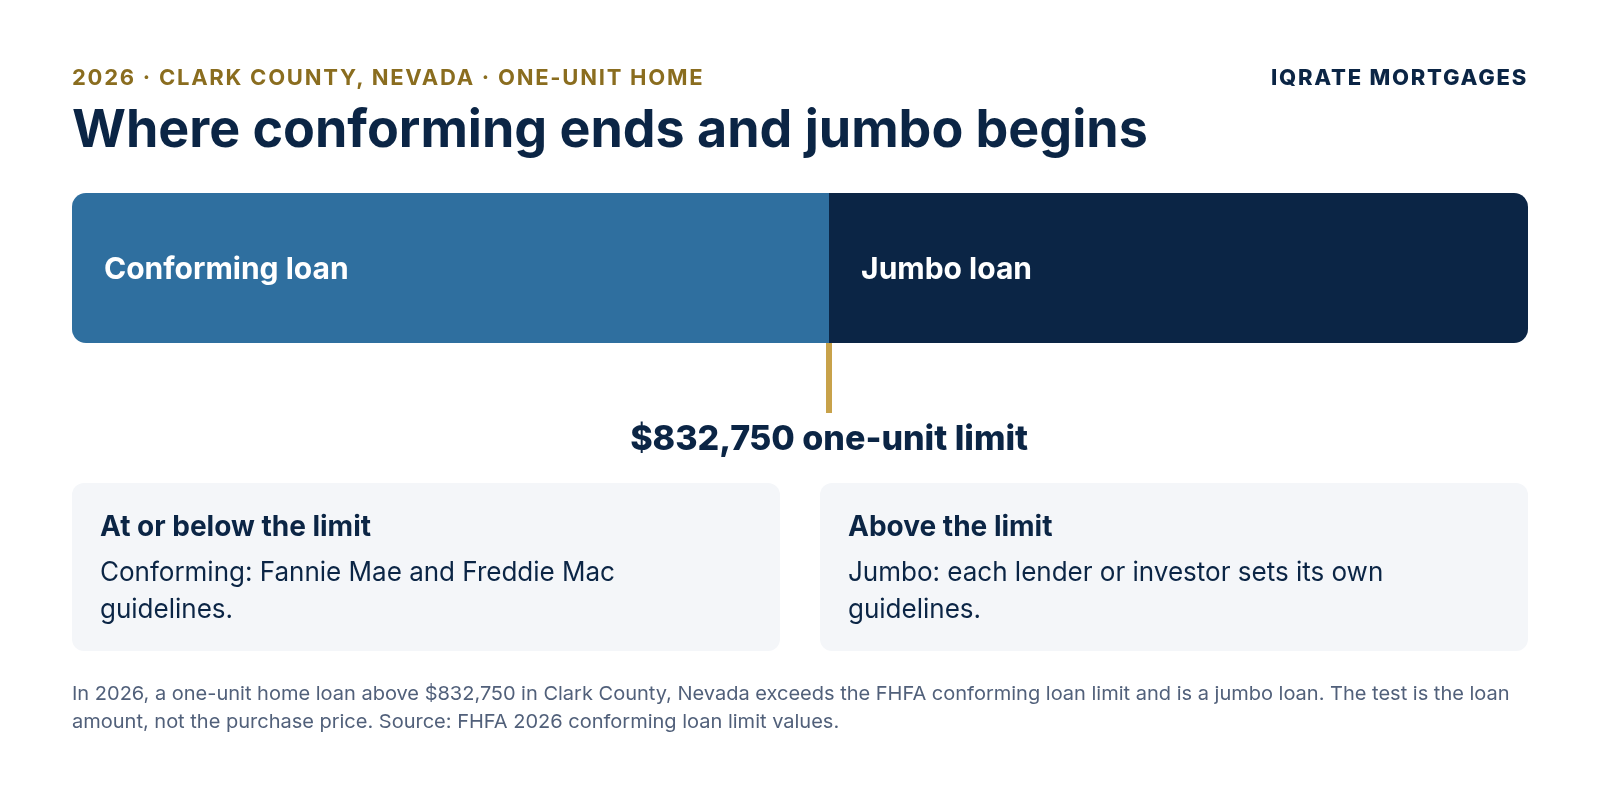
In 2026, a one-unit home loan above $832,750 in Clark County, Nevada exceeds the FHFA conforming loan limit and is a jumbo loan.
The jumbo test looks at the loan amount, not the purchase price. A buyer with a large down payment can buy an expensive home with a conforming loan. A buyer who puts less down on a smaller home can end up in jumbo territory. What matters is the number on the note.
FHFA sets the conforming limit each year. Clark County and every other Nevada county sit at the national baseline limit, so there is no high-cost area in Nevada and no high-balance tier between conforming and jumbo.

These limits come from the FHFA conforming loan limit values published for Clark County, Nevada.
You can check the 2026 figures yourself in FHFA's full county loan limit list.
For a single-family home, the one-unit limit applies. If your loan amount is above it, you need jumbo financing. If it is at or below it, you can use a conforming loan that follows Fannie Mae and Freddie Mac rules.
HUD's 2026 FHA limit for a one-unit home in Clark County is $541,287 (HUD FHA mortgage limits), well below the conforming limit, so FHA loans do not reach jumbo loan sizes here.
Staying conforming or going jumbo
Some buyers sit close enough to the limit that they have a real choice. You can bring more cash to keep the loan conforming, or borrow more and accept jumbo rules. Neither path is always better.
Reasons to stay conforming. Conforming loans follow one national rulebook. Documentation is more predictable, and the appraisal and reserve rules are standard. If you have the cash and want the simplest approval, a larger down payment can keep you on that side.
Reasons to go jumbo. Extra cash put into the house is cash you no longer hold. On a high-value home, some buyers would rather keep liquid assets for reserves, business needs or investments. Jumbo pricing varies by lender, so compare real quotes issued on the same day.
A middle path. Some buyers pair a conforming first mortgage with a second lien to keep the main loan under the limit. Whether that makes sense depends on the second lien's terms and how long you plan to keep both loans.
Conforming vs jumbo for a MacDonald Highlands purchase
| Feature | Conforming | Jumbo |
|---|---|---|
| Rules | Fannie Mae, Freddie Mac; FHFA limits | Each lender's own |
| Documents | Standard list | Deeper review; bank-statement or asset options |
| Appraisal | Standard; sometimes waived | Full review of view, lot, sales; sometimes two |
| Reserves | Lower, agency rules | Higher; grow with loan size |
| Flexibility | Limited | Interest-only, ARM, asset-based (varies) |
Underwriting a high-value MacDonald Highlands home
The loan program may be a standard jumbo. A high-value home is often less standard. That gap is where a file can slow down.
The appraisal is the hard part
Luxury homes in MacDonald Highlands have few comparable sales.
If the home you are buying has a standout view, golf-course frontage or a hillside position, the appraiser has to support that premium with closed sales that are truly similar. When those sales are scarce, the appraiser may reach further back in time or further out in distance and make larger adjustments. The underwriter then reads each adjustment closely.
A low appraisal on a jumbo loan matters. The lender bases the loan on the lower of price or appraised value. A short appraisal can mean more cash at closing, a renegotiation with the seller or a smaller loan.
Preparing for a view-home appraisal
You cannot pick the appraiser, and you should never pressure one. You can make sure the appraiser has the facts. Before the appraisal:
- Ask your agent to gather recent closed sales in the community with similar views, lot position and finish level, plus notes on why each is or is not comparable.
- List upgrades with rough completion dates: pool and outdoor living, smart-home systems, finishes, casitas, elevators and other features that add value.
- Gather permits for additions or remodels. Unpermitted work can raise underwriting questions, and it is better to know early.
- Note the view corridor, orientation and any features that help protect the view.
- Ask your lender how its reconsideration of value process works, before you need it.
- Keep the appraisal contingency in your contract long enough to act on the result.
Association dues and club costs
Lenders count every required housing cost in your payment. In a master-planned community, that can mean more than one line item:
- Master association dues. These apply to every home and are counted.
- Sub-association dues. In some master-planned communities, a neighborhood has its own association on top of the master. Check whether the home you want has one. If it does, those dues count too.
- Special assessments. If the association has levied one, the lender will want to know how it is paid.
- Club membership. If membership in a golf or social club is optional, many lenders leave those dues out of your ratios. If a neighborhood's documents make dues mandatory, expect them to be counted. The lender decides, based on the documents.
Ask for the association documents, budgets and dues statements as soon as your offer is accepted. A missed dues layer can shift your debt-to-income ratio late in a file.
Primary home or second home
How you will use the home changes the loan. A primary residence gets the broadest set of jumbo options. Many jumbo programs allow second homes, which may come with tighter down payment and reserve rules. You must actually use a second home yourself and not rent it out.
If you plan to rent the home, it is an investment property. That means different lenders and different pricing. Tell your broker the real plan at the start. Changing occupancy mid-file can mean starting over with a different lender.
Income paths for MacDonald Highlands buyers
If your income does not come from a simple W-2, the documentation path matters more than almost anything else on a jumbo file.
Self-employed and business owners
Self-employed buyers can use bank-statement jumbo programs.
Bank-statement programs qualify you on deposits instead of tax-return income. Full-documentation jumbo loans use your tax returns. Pricing differs by program and by lender, so a good broker prices both before choosing. Switching programs halfway through underwriting can cost time.
Asset-based income
Retirees and asset-rich buyers can use asset depletion.
Asset depletion turns eligible investment balances into a qualifying income figure. Each lender sets its own rules for which accounts count and how. If your wealth is in brokerage or retirement accounts and your reported income is modest, this path is worth pricing.
Interest-only and adjustable-rate options
Some jumbo programs offer interest-only payment periods or adjustable rates. These suit some plans and not others, so ask how the payment can change over the life of the loan.
Adjustable-rate jumbo options can include 5-, 7- and 10-year ARMs; terms vary by lender.
Relocating from California
A loan size that was conforming in California may be jumbo in Las Vegas.
California's high-cost counties have higher conforming limits than Clark County. Buyers moving from there can be surprised to land in jumbo financing on a loan they consider ordinary. Some also want to buy here before selling there.
Options include a bridge loan, a HELOC on your California home, or qualifying with both payments (varies by lender).
Our guide to buying a Las Vegas jumbo home before selling in California walks through each option.
VA above the conforming limit
Veterans with full VA entitlement have no VA loan limit.
Individual lenders may set their own maximum loan amounts, so compare a VA option with a conventional jumbo.
VA appraisals and property rules have their own requirements, and a high-value home with few comparable sales can test them. Price both paths side by side.
Providers to compare for a MacDonald Highlands jumbo loan
There are four main types of jumbo providers. Each fits a different kind of borrower.
Retail banks. A bank can only offer its own jumbo product. Some banks offer relationship pricing to clients who bring deposits or investment assets. If your file does not fit that bank's guidelines, though, you start over somewhere else.
Mortgage brokers. A broker can shop the same file to many lenders, which matters more on jumbo loans than on conforming ones. Every jumbo lender writes its own rules on reserves, loan-to-value, second homes and income. A broker can match your file to the lender whose rules fit it, instead of reshaping your file to fit one lender.
Credit unions. Some credit unions keep jumbo loans on their own books and can be flexible for members. Their programs, maximum loan sizes and turn times vary widely, so ask specific questions.
Private banks and wealth-management lenders. These lenders may tie jumbo pricing to the assets you move to them. That can work if you already want that relationship. Read the terms on asset minimums and what happens if balances drop.
Comparing jumbo providers
- Start with NMLS Consumer Access. Check that the loan officer and the company are licensed in Nevada on NMLS Consumer Access before you share documents.
- Ask how many jumbo programs the provider can actually offer for your file, and which ones fit your income type.
- Ask how the provider handles a view-home appraisal with few comparable sales, including second-appraisal rules and reconsideration of value.
- Get the reserve requirement in writing, including how retirement and brokerage assets are counted.
- Ask whether optional club dues and every association layer will be counted in your ratios.
- Ask whether the quote depends on moving assets or opening accounts.
- Compare Loan Estimates issued the same day for the same loan amount, so pricing differences are real.
- Ask who underwrites the file and who your contact is from application to closing.
- Ask what happens if your file needs a different program halfway through.
- Read reviews, but weigh them alongside the answers to the questions above.
Our approach to a MacDonald Highlands jumbo file
iQRATE Mortgages, a Las Vegas brokerage led by David Ghazaryan (NMLS 1486726), compares full-doc, bank-statement, asset-depletion and interest-only jumbo options.
We shop local jumbo files with more than 100 banks and private lenders.
Before you write an offer, we work through a short list with you:
- Decide whether the loan should stay conforming or go jumbo, based on cash, reserves and pricing.
- Total the real monthly housing cost with every association layer, assessment and mandatory due.
- Pick the income documentation path that fits your situation and price it against the alternatives.
- Plan for the appraisal, including comparable sales your agent can share.
- Confirm occupancy, primary or second home, so we shop the right lenders.
For program details, see our jumbo loan program page. If you are also comparing homes in Summerlin, our Summerlin jumbo guide covers that market. If you are buying a homesite or building rather than buying a finished home, read our guide to jumbo loans for new construction and custom homes instead.
MacDonald Highlands jumbo loan questions
Does every MacDonald Highlands purchase need a jumbo loan?
No. The jumbo test is based on the loan amount, not the price. A buyer who makes a large enough down payment can stay at or under the Clark County conforming limit and use a conforming loan. Some buyers choose jumbo anyway so they can keep more cash in reserve.
What happens if my MacDonald Highlands view home appraises below the contract price?
The lender bases the loan on the lower of price and appraised value. You can bring more cash, renegotiate with the seller, ask the lender for a reconsideration of value with stronger comparable sales, or use your appraisal contingency to step away. Sharing comparable sales and an upgrade list before the appraisal helps the appraiser see the full picture.
Are optional club dues counted when I qualify for a MacDonald Highlands jumbo loan?
Lenders count required housing costs. Optional club membership dues are often left out. Required master and sub-association dues are counted. If a neighborhood's documents make any club dues mandatory, expect them to be included. The lender makes the final call based on the association documents.
Can I buy in MacDonald Highlands as a part-time resident with a jumbo loan?
Many jumbo programs allow second homes, which may come with tighter down payment and reserve rules than a primary home. You have to use the home yourself and not rent it out. If you plan to rent it, the home is an investment property, which uses different lenders and pricing.
Can I refinance my MacDonald Highlands jumbo into a conforming loan?
Possibly. If your balance is now at or under the Clark County conforming limit, or you pay it down to that level, a conforming refinance may be available. If you want cash out and the new balance goes above the limit, the refinance stays jumbo. Compare both before deciding.
Talk to a MacDonald Highlands jumbo broker
If you are buying or refinancing in MacDonald Highlands, send us the property, your price range and how you earn your income. We can review whether the loan is likely conforming or jumbo, which documentation path may fit, and what to prepare for the appraisal.
Call or text (702) 766-3744 or apply online.
Our office is at 6360 S Rainbow Blvd, Suite 101, Las Vegas, NV 89118.
You can also reach us through our contact page, or see our Henderson mortgage broker page and Las Vegas mortgage broker page for other loan types.
iQRATE Mortgages is a mortgage broker, not a lender, and does not make credit decisions. Borrowers can confirm that the loan officer and the company are licensed in Nevada on NMLS Consumer Access. If an affiliated business relationship applies to your transaction, you will receive a separate written Affiliated Business Arrangement disclosure. This page is general information, not a commitment to lend; all loan programs, terms and approvals are subject to lender underwriting and may change without notice. Equal Housing Opportunity.
iQRATE Mortgages company NMLS 1862492.
References