In 2026, any one-unit home loan above $832,750 in Clark County, Nevada is a jumbo loan (FHFA). Above that amount, the loan is jumbo. The same line applies in the City of Las Vegas, Summerlin, Henderson and North Las Vegas, because no Nevada county has a higher limit. In 2025, 190 home purchase loans inside the Las Vegas city limits were above the conforming limit, with a median loan of $1,085,000 (iQRATE analysis of public HMDA data).
By David Ghazaryan, NMLS 1486726, iQRATE Mortgages (NMLS 1862492) Updated November 4, 2026
Key numbers: jumbo loans in the City of Las Vegas
- Jumbo line, 2026, one unit: loans above $832,750 (FHFA). Nevada has no high-balance tier.
- City jumbo share of purchase loans, 2025: 3.1% (190 of 6,154). Clark County was 4.0%.
- Median city jumbo loan, 2025: $1,085,000, on a median home value of $1,355,000. The median loan-to-value was 80%.
- City jumbo denial rate, 2025, all loan purposes: 16.4%. The conforming rate was 16.3%.
- Top denial reason: debt-to-income ratio, in 17 of 57 denials.
- Lenders: 190 city jumbo purchase loans came from 81 different lenders.
- Top ZIP: 89144 (Summerlin North). 18.2% of its in-city purchase loans in 2024–2025 were jumbo.
Las Vegas jumbo requirements at a glance (2026)
| Requirement | Typical range across lenders we compare | What moves it |
|---|---|---|
| Jumbo threshold, one unit | Loan above $832,750 (FHFA 2026) | Set by FHFA each year |
| Down payment | Often 10–20% | Loan size, credit, property type, occupancy |
| Credit score | Many lenders start around 700 | Higher for larger loans or smaller down payments |
| Debt-to-income (DTI) | Commonly up to about 43%; some go higher with strong reserves | Lender and program |
| Reserves after closing | About 6–12 months of the full housing payment; more on larger loans or with several properties | Loan amount, occupancy, documentation type |
| Appraisal | Full appraisal; larger loans may need a second appraisal or a review | Loan amount and lender |
What usually counts as reserves: - checking, savings and money market accounts - brokerage accounts - vested retirement accounts, often at a discounted value
What usually doesn't count: - gift funds - HELOC or other borrowed money - business assets, in many cases, unless the lender accepts a CPA letter
Seasoning: lenders want reserves seasoned in your accounts, commonly about two months of statements. Large recent deposits need a paper trail.
DTI in practice: across the Las Vegas metro in 2025, 73.1% of jumbo purchase loans with a reported DTI were at or below 43%. The other 26.9% were above 43% (HMDA).
| DTI, 2025 metro jumbo purchases | Loans | Share of loans with a reported DTI |
|---|---|---|
| Under 36% | 419 | 42.7% |
| 36% to 43% | 299 | 30.4% |
| 44% to 49% | 180 | 18.3% |
| 50% or higher | 84 | 8.6% |
These are typical ranges, not a commitment to lend. Each lender sets its own rules. For tier-by-tier detail, see our jumbo loan program guide. For other Las Vegas loan types, see our Las Vegas mortgage broker page.
Want to know where your file stands before you write an offer? Call or text (702) 766-3744 or start an application.
Where is the jumbo line for a Las Vegas home in 2026?
The limit applies to the loan amount, not the price.
2026 conforming loan limits, Clark County, NV (FHFA)
| Property | 2026 conforming limit | Jumbo if the loan is above |
|---|---|---|
| 1 unit | $832,750 | $832,750 |
| 2 units | $1,066,250 | $1,066,250 |
| 3 units | $1,288,800 | $1,288,800 |
| 4 units | $1,601,750 | $1,601,750 |
Source: FHFA conforming loan limits.
- No high-balance loan exists here. Every Nevada county uses the national baseline.
- California buyers: Los Angeles and Orange County allow conforming loans up to $1,249,125 in 2026. The same loan can be jumbo in Las Vegas.
- With 20% down, a one-unit loan turns jumbo once the price passes about $1,040,938. With 10% down, the line is about $925,278. With 30% down, it is about $1,189,643.
How many Las Vegas buyers actually use jumbo loans?
About 3 in 100 inside the city limits. We pulled every reported home purchase loan in Clark County from public HMDA records, then isolated the City of Las Vegas.
Share of home purchase loans above the conforming limit: City of Las Vegas vs Clark County (HMDA)
| Year | City purchase loans | City jumbo loans | City jumbo share | County purchase loans | County jumbo loans | County jumbo share |
|---|---|---|---|---|---|---|
| 2024 | 6,867 | 207 | 3.0% | 29,562 | 1,009 | 3.4% |
| 2025 | 6,154 | 190 | 3.1% | 26,769 | 1,082 | 4.0% |
- The city is a smaller jumbo market than the county. Much of the valley's luxury housing sits outside city limits, in Summerlin South and Henderson.
- City jumbo loans fell less than city purchase loans overall. From 2024 to 2025, city purchase loans changed −10.4% and city jumbo purchase loans changed −8.2%. The median city jumbo loan changed +5.9%. (iQRATE calculation from the counts shown.)
How we built this data (method) - Source: FFIEC/CFPB HMDA Data Browser, loan-level files for Clark County, NV, activity years 2024 and 2025. Computed by iQRATE in Python on November 4, 2026. - City of Las Vegas = the 148 census tracts whose Census Bureau internal point lies inside city limits (TIGERweb 2020). These tracts hold 621,520 of the city's 641,903 residents in the 2020 Census, about 97%. - Jumbo = the HMDA flag "NC," meaning above the conforming limit in force that year. In 2025 that limit was $806,500, so these are 2024–2025 loans, not 2026 loans. - Purchase loans = originated, first-lien, closed-end home purchase loans. No HELOCs and no reverse mortgages. - Loan amounts: HMDA reports each one as the midpoint of a $10,000 band. - Not in the city figures: Summerlin South (including all of ZIP 89135) and Henderson. They are outside city limits. The Clark County figures include them. - Coverage: HMDA covers loans reported by lenders that must report. It does not capture every loan.


What does a typical City of Las Vegas jumbo loan look like?
The typical in-city jumbo loan is just over $1 million, has 20% down, is on a primary home and has a 30-year term. A real minority use ARMs, interest-only payments, VA loans or short-term financing.
City of Las Vegas jumbo purchase loans: profile (HMDA)
| Measure | 2024 | 2025 |
|---|---|---|
| Jumbo purchase loans | 207 | 190 |
| Median jumbo loan amount | $1,025,000 | $1,085,000 |
| Median value of the home bought | $1,315,000 | $1,355,000 |
| Median loan-to-value | 80.0% | 80.0% |
| Median reported borrower income | $440,500 | $402,500 |
| Total jumbo purchase volume | $260,355,000 | $259,410,000 |
| Conventional jumbo loans | 169 | 162 |
| VA loans above the conforming limit | 38 | 28 (14.7%) |
| Primary residence | 167 | 157 (82.6%) |
| Investment property | 29 | 30 (15.8%) |
| Second home | 11 | 3 |
| Adjustable-rate (intro fixed period) | 55 | 50 (26.3%) |
| Interest-only payments | 36 | 32 (16.8%) |
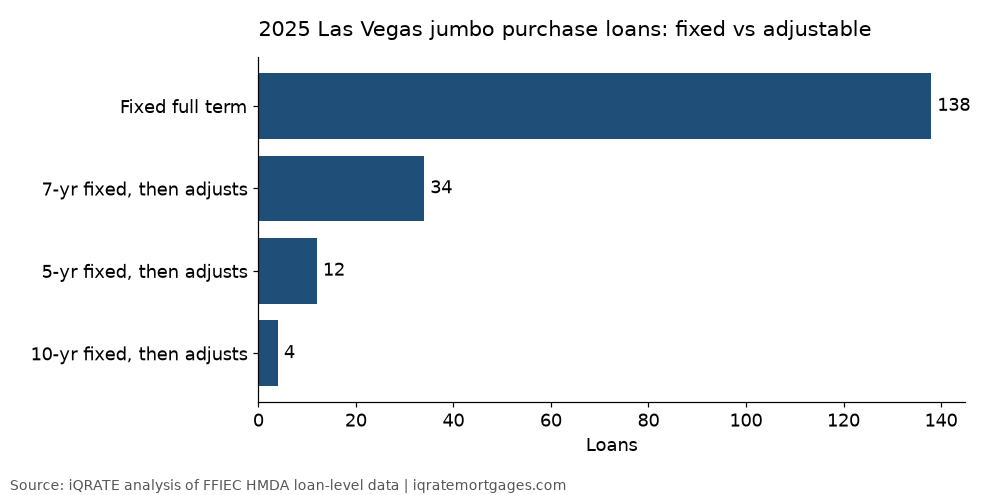
| 7-year fixed, then adjusts | 39 | 34 |
| 5-year fixed, then adjusts | 4 | 12 |
| 10-year fixed, then adjusts | 11 | 4 |
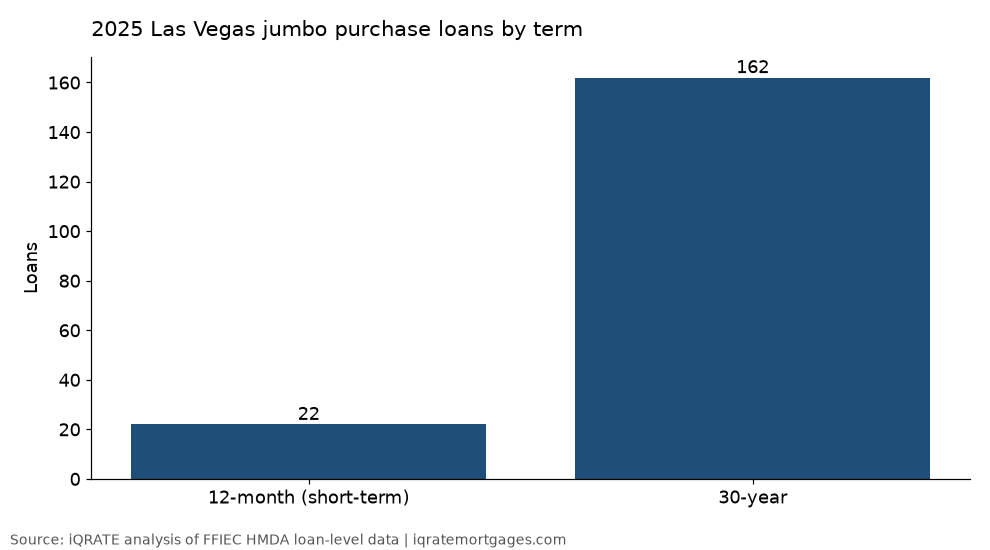
| 30-year term | 184 | 162 |
| 12-month term (short-term loans) | 18 | 22 |
| Different lenders making these loans | 88 | 81 |
Four takeaways:
- About one in four chose an ARM. The 7-year fixed period led, with 34 loans in 2025.
- About one in six used interest-only payments. That share was higher than across the metro.
- VA shows up above the limit. Veterans with full entitlement have no VA loan limit, so compare a VA loan before you assume a conventional jumbo.
- The market is spread thin. 190 loans came from 81 lenders, about 2.35 loans per lender. Each lender writes its own jumbo rules, which is why shopping the file matters.
Very short terms, like the 22 twelve-month loans in 2025, usually signal bridge or short-term financing.
City vs metro, 2025
| Measure | City of Las Vegas | Las Vegas metro |
|---|---|---|
| Median jumbo loan | $1,085,000 | $1,135,000 |
| Median home value | $1,355,000 | $1,505,000 |
| Adjustable-rate share | 26.3% | 29.8% |
| Interest-only share | 16.8% | 14.2% |
| VA share of loans above the limit | 14.7% | 13.0% |
The metro figures cover MSA 29820 (1,088 jumbo purchase loans) as published on our jumbo guide. The county figures above (1,082) come from the Clark County file pulled November 4, 2026.




How big are Las Vegas jumbo loans, and how much do buyers put down?
2025 City of Las Vegas jumbo purchase loans by size (HMDA)
| Loan amount | Loans |
|---|---|
| Above $806,500 to under $1,000,000 | 74 |
| $1,000,000 to under $1,500,000 | 64 |
| $1,500,000 to under $2,000,000 | 20 |
| $2,000,000 to under $3,000,000 | 27 |
| $3,000,000 or more | 5 |
| Total | 190 |
2025 City of Las Vegas jumbo purchase loans by loan-to-value (HMDA)
| Loan-to-value | Loans |
|---|---|
| 50% or less | 5 |
| Over 50% to 70% | 25 |
| Over 70% to 80% | 104 |
| Over 80% to 90% | 21 |
| Over 90% | 28 |
183 of the 190 loans fall in these LTV ranges.
What this means for you:
- Most loans were under $1.5 million. 138 of 190 (72.6%) were. A Las Vegas jumbo is usually a move-up home in Summerlin North, The Lakes or the northwest, not an eight-figure estate.
- Most borrowers financed 80% or less. 134 loans did. 49 loans (26.8% of the 183) financed more than 80%: 21 over 80% to 90%, and 28 over 90%. These ranges cover all loan types: the 190 loans include 28 VA loans, and we did not split LTV by loan type, so don't read these counts as typical for conventional jumbo loans.
- Second homes and rentals need more down. Across the metro in 2025, the median conventional second-home jumbo LTV was 75%. No investment-property jumbo in the sample went above 80% (jumbo guide). Plan on 20% to 25% or more.


Where in Las Vegas do jumbo loans happen?
Inside city limits, jumbo loans cluster in Summerlin North, Summerlin West, The Lakes and Desert Shores. The top five ZIPs held 235 of the city's 397 jumbo purchase loans in 2024–2025 (59.2%).
City of Las Vegas jumbo purchase loans by ZIP, 2024 and 2025 combined (HMDA, in-city tracts only)
| ZIP | Area (approximate) | Purchase loans | Jumbo loans | Jumbo share | Typical value, Sep 2026 (Zillow middle tier) |
|---|---|---|---|---|---|
| 89144 | Summerlin North | 379 | 69 | 18.2% | $512,147 |
| 89117 | The Lakes and Desert Shores | 534 | 53 | 9.9% | $471,730 |
| 89134 | Summerlin North | 692 | 47 | 6.8% | $483,505 |
| 89145 | West central (Rampart and Charleston) | 537 | 33 | 6.1% | $383,423 |
| 89138 | Summerlin West | 210 | 33 | 15.7% | $757,906 |
| 89129 | Lone Mountain and northwest | 1,042 | 31 | 3.0% | $437,005 |
| 89131 | Centennial Hills | 952 | 29 | 3.0% | $532,899 |
| 89166 | Skye Canyon and Providence | 1,521 | 23 | 1.5% | $492,502 |
| 89107 | Charleston Heights | 543 | 16 | 2.9% | $347,084 |
| 89143 | Centennial Hills and Providence | 1,130 | 16 | 1.4% | $468,383 |
| 89149 | Centennial Hills (Durango and Elkhorn) | 965 | 14 | 1.5% | $489,680 |
| 89128 | Desert Shores and Rancho | 905 | 11 | 1.2% | $379,198 |
| 89102 | Scotch 80s, Rancho Circle, Charleston corridor | 302 | 10 | 3.3% | $364,478 |
| 89130 | Northwest (Craig and Rainbow) | 741 | 9 | 1.2% | $436,707 |
ZIP = the 2020 ZIP Code Tabulation Area holding each tract's internal point. Parts of these ZIPs outside the city are not counted. Typical values come from Zillow's Home Value Index (all homes, middle tier, September 2026), as published on our Las Vegas mortgage broker page.
- One tract stands out. Census tract 32003003223, in 89144, had 47 of its 76 purchase loans above the limit in 2024–2025 (61.8%).
- ZIP averages hide jumbo streets. 89102 has a typical value of $364,478, yet 10 of its in-city purchase loans were jumbo. Price your own home, not the ZIP average.
Jumbo pockets outside city limits: top-tier home values
Summerlin South (including The Ridges and all of 89135) is unincorporated Clark County. Henderson is its own city. Neither appears in the city data above. Zillow's top tier is the typical value of the most expensive third of homes, the best public proxy for jumbo prices. Compare each value with the 20%-down jumbo line of about $1,040,938.
Typical home values in Las Vegas-area jumbo ZIPs (Zillow ZHVI, September 30, 2026)
| ZIP | Area | Middle-tier typical value | Top-tier typical value | Top tier, Sep 2025 |
|---|---|---|---|---|
| 89135 | Summerlin South (The Ridges, Red Rock Country Club) | $714,717 | $1,762,834 | $1,748,502 |
| 89138 | Summerlin West | $757,906 | $1,171,535 | $1,192,655 |
| 89144 | Summerlin North (The Hills) | $512,147 | $966,347 | $981,647 |
| 89012 | Henderson (MacDonald Highlands, Ascaya) | $521,350 | $885,763 | $891,870 |
| 89052 | Henderson (Anthem, Green Valley South) | $594,397 | $919,625 | $919,141 |
| 89011 | Henderson (Lake Las Vegas) | $468,182 | $664,174 | $683,057 |
| 89141 | Southern Highlands | $514,085 | $748,756 | — |
Source: Zillow Research, ZIP-level ZHVI, as published on our jumbo guide.
A top-tier average still smooths out the very top. Estates in The Ridges, MacDonald Highlands and Ascaya sell for several million dollars. The jurisdiction also sets your property-tax district. See our Summerlin and Henderson pages.
Market backdrop, September 2026 (Las Vegas REALTORS). - The median single-family sale was $470,000. - The average price of available single-family homes was $872,781. - Supply was 4.6 months. - 23.5% of sales were cash.
More of the unsold inventory sits at upper prices, which gives jumbo buyers room to negotiate. A fully documented pre-approval still matters when about one buyer in four pays cash.


Why do Las Vegas jumbo applications get denied?
Jumbo status alone doesn't explain it. In the city, jumbo and conforming denial rates were almost the same.
Decided first-lien applications, City of Las Vegas, all loan purposes (HMDA)
| Year | Jumbo decided | Jumbo denied | Jumbo denial rate | Conforming decided | Conforming denied | Conforming denial rate |
|---|---|---|---|---|---|---|
| 2024 | 346 | 59 | 17.1% | 11,085 | 1,873 | 16.9% |
| 2025 | 347 | 57 | 16.4% | 11,045 | 1,804 | 16.3% |
"Decided" means originated, approved but not accepted, or denied.
Main reason given for the 57 denied City of Las Vegas jumbo applications, 2025 (first reason listed)
| Reason | Denials |
|---|---|
| Debt-to-income ratio | 17 |
| Credit application incomplete | 15 |
| Credit history | 7 |
| Other | 6 |
| Collateral (appraisal or property) | 5 |
| Insufficient cash (down payment or closing costs) | 4 |
| Unverifiable information | 3 |
32 of the 57 denials (56.1%) came down to debt-to-income or an incomplete application. Both are problems of structure and paperwork. A different income method can sometimes change the DTI picture, for example bank statements, asset depletion, or a different way to count bonus income. Sending the full document package up front addresses the incomplete-application problem.
Here is how I approach these files:
I don't begin by assuming the first lender made a mistake. I begin by finding out exactly why that lender couldn't approve the transaction. Was it income calculation? Insufficient reserves? Restricted stock? A debt-to-income limit? A property that didn't satisfy the lender's appraisal requirements? Those are very different problems. The next step is to identify whether the issue is something that can be corrected through documentation or whether the borrower genuinely needs a different loan program. … A successful mortgage strategy starts with understanding the financial facts, not simply submitting the same file to another bank. — David Ghazaryan
Denied elsewhere, or worried you will be? Call or text (702) 766-3744 and tell us the reason the lender gave.


How much cash does a Las Vegas jumbo purchase take?
This section is arithmetic only. It uses no rates and no payments.
Near the line: a $1,000,000 home
| Down payment | Cash down | Loan amount | Over $832,750 by | Loan type |
|---|---|---|---|---|
| 10% | $100,000 | $900,000 | $67,250 | Jumbo |
| 15% | $150,000 | $850,000 | $17,250 | Jumbo |
| 20% | $200,000 | $800,000 | $0 | Conforming |
With $167,250 (16.7%) down or more, this loan stays conforming. Some buyers near the line instead pair a conforming first mortgage with a second lien (a "piggyback"). Which route costs less depends on your credit, reserves, how long you'll keep the loan and that day's pricing. Read jumbo vs piggyback in Las Vegas and Henderson.
Well above the line: a $1,500,000 home
This price is close to the 2025 metro median value of a home bought with a jumbo loan ($1,505,000).
| Down payment | Cash down | Loan amount | Loan-to-value | Loan type |
|---|---|---|---|---|
| 10% | $150,000 | $1,350,000 | 90% | Jumbo |
| 15% | $225,000 | $1,275,000 | 85% | Jumbo |
| 20% | $300,000 | $1,200,000 | 80% | Jumbo |
| 25% | $375,000 | $1,125,000 | 75% | Jumbo |
| 30% | $450,000 | $1,050,000 | 70% | Jumbo |
| 44.5% | $667,250 | $832,750 | — | Conforming |
- At 20% down, the loan is $1,200,000, which is $367,250 above the 2026 limit.
- Transfer tax on this sale is $7,650: 3,000 units of $500 at $2.55 each. By custom the seller pays it, but the contract decides.
- Reserves come on top of the down payment. They are money left over after closing, counted in months of the full housing payment: principal, interest, taxes, insurance and HOA dues.
- On a $5,000 monthly payment: 6 months = $30,000; 12 months = $60,000.
- On a $10,000 monthly payment: 6 months = $60,000; 12 months = $120,000.
- Ask for the reserve figure in dollars before you write an offer. Reserves are the most common reason a jumbo file is restructured.
- Your down payment is not your cash to close. Add closing costs and prepaids (insurance, daily interest, tax escrow).
Figures are iQRATE arithmetic on the sourced limit and transfer-tax rate. Not a quote or an offer. Lender minimums vary.


What Las Vegas costs hit jumbo buyers?
Clark County transfer tax at jumbo prices
The tax is $2.55 per $500 of value: the $1.95 state rate plus $0.60 for Clark County.
| Sale price | Transfer tax |
|---|---|
| $1,000,000 | $5,100 |
| $1,500,000 | $7,650 |
| $2,000,000 | $10,200 |
| $3,000,000 | $15,300 |
By local custom the seller pays it, but the purchase contract controls. Sources: Nevada Department of Taxation; NRS chapter 375.

City of Las Vegas property tax: rough math before abatements
The FY 2026–27 City of Las Vegas district rate is about $3.2782 per $100 of assessed value. Assessed value is 35% of taxable value. If taxable value equaled the price, the yearly bill before abatements would be about:
| Taxable value | Estimated yearly tax before abatements |
|---|---|
| $832,750 | about $9,555 |
| $1,000,000 | about $11,474 |
| $1,500,000 | about $17,211 |
| $2,000,000 | about $22,947 |
| $3,000,000 | about $34,421 |
iQRATE arithmetic; estimate only. The Assessor sets taxable value, which is often below the price, and the caps below limit yearly increases. Summerlin South, Henderson and other areas outside city limits are in different tax districts. Check the parcel's district with the Clark County Treasurer. Lenders use the projected tax bill in your payment and DTI.
The 3% cap, HOAs and homestead
- 3% cap: under NRS 361.4723, the yearly increase on a primary residence's tax bill is capped at 3%. Second homes and rentals get a cap of up to 8%.
- After you buy, claim the cap. Recording a new ownership document removes the 3% cap until the new owner claims it. Claim your primary residence with the Clark County Assessor after closing.
- New construction: no cap in the first fiscal year.
- HOA dues and SIDs count in your DTI. That includes master and sub-association dues and any special improvement district (SID) assessment. Guard-gated communities often add HOA transfer and capital contribution fees at closing.
- Homestead: Nevada protects up to $605,000 of equity in a primary home from most creditors (NRS 115.010). You must record a declaration of homestead. It does not protect against your mortgage lender.
Refinancing a Las Vegas jumbo loan
Jumbo refinances are a smaller market than purchases. 2025 HMDA data shows 404 originated first-lien jumbo refinances in the Las Vegas metro, against 1,088 jumbo purchases.
- The line is judged on the new loan amount. If you've paid the balance down, or bring cash to the refinance, a new loan at or below $832,750 can be conforming. That holds even if the original loan was a jumbo.
- Cash-out usually allows less leverage. Lenders typically set a lower maximum loan-to-value on a cash-out refinance than on a rate-and-term refinance.
- Your 3% tax cap is safe. A refinance that does not record a new ownership document does not affect it.
- ARM nearing its first adjustment? Before the reset, compare three options: a new ARM, a fixed-rate jumbo, and a conforming loan with a principal paydown.
See refinance options or call (702) 766-3744. Terms vary by lender.
Which jumbo programs fit which Las Vegas borrowers?
Jumbo is not one product. - Published wholesale jumbo programs extend to $5 million. - Separate bank-statement and asset-utilization programs serve borrowers who don't fit full-documentation underwriting. - Some programs allow fixed rates, ARMs or interest-only payments. Others have strict reserve rules, different credit-score thresholds or limits on investment properties.
| Borrower | What the lender needs to understand | Programs we compare |
|---|---|---|
| Self-employed owners and content creators | Business ownership, cash flow, 1099 income, personal and business bank statements, and the expenses each program applies | Full-doc, bank-statement, P&L, non-QM |
| Casino and hospitality executives | Bonuses, incentive pay, commissions and equity awards, and which the lender will count | Full-doc fixed or ARM; interest-only where it fits |
| Retirees and high-net-worth buyers | Millions invested but little employment income | Asset-depletion / asset-utilization |
| Californians relocating | Proceeds from the prior home, reserves, employment continuation | Full-doc or non-QM; buy-before-sell options |
| Investors | Qualifying rent, debt-service coverage, down payment, reserves, exit strategy | Investor jumbo, DSCR (business purpose only) |
The right structure depends on more than the loan amount. Occupancy, credit score, leverage, assets, documentation type and how long you plan to keep the home all matter.
Condo and high-rise buyers: lenders review the building as well as you. Projects can fail review for any of these reasons: - high investor ownership - litigation - hotel-style rentals - one entity owning too many units
Order the HOA questionnaire early. See how warrantability works for Las Vegas high-rise jumbo loans.
New construction: ask early how long the rate lock can run if the home won't finish for months. See jumbo loans for new construction and custom homes.
From my desk: Las Vegas jumbo borrowers who don't fit the template
David Ghazaryan, NMLS 1486726
One of the most unusual clients I've worked with was a YouTube gamer buying a home in Henderson for approximately $3 million. Twenty years ago, a buyer purchasing a house at that price was probably a physician, an executive, or a business owner with traditional financial statements. This buyer had built a career playing video games in front of an online audience. His original purchase file dates to 2020, and his team returned in January 2022 about refinancing his primary residence. I wouldn't quote a bank-versus-broker savings figure without comparing the actual offers.
He wasn't my only unconventional high-income client. I've also worked with a music producer and an Instagram influencer. A person can have extraordinary earning power without ever receiving a traditional paycheck. The challenge is making sure the lender understands the real financial picture rather than judging somebody's ability to repay based on their job title.
Consider a music producer. Revenue might arrive through royalties, licensing agreements, production fees, and business entities. Some revenue can be irregular even when the underlying business is well established. An Instagram influencer may receive advertising revenue, sponsorship payments, and other business income. A bank's standard tax-return calculation may not always provide the best available qualification method.
That doesn't mean we can count every dollar that enters the account. It means we need to understand which receipts represent eligible income and identify a lender whose documentation requirements fit the borrower.
I started in the mortgage industry in 2005 and have also worked in tax preparation since 2008. That combination is particularly valuable when evaluating complicated self-employed borrowers.
Past results do not guarantee future outcomes. All loans are subject to credit approval. More closed jumbo files, with names removed, are on our jumbo guide.
What documents do you need for a Las Vegas jumbo loan?
Send everything at once. In 2025, 15 of the 57 denied city jumbo applications were coded "credit application incomplete." Requirements vary by lender and program.
| Document | W-2 or executive | Self-employed / creator | Retiree or asset-based | Relocating Californian | Investor (business purpose) |
|---|---|---|---|---|---|
| Photo ID, credit authorization | Yes | Yes | Yes | Yes | Yes |
| Pay stubs, 2 years of W-2s | Yes | If any W-2 income | No | If employed | If using W-2 income |
| Bonus, commission or RSU history | If counted | No | No | If applicable | No |
| Personal tax returns | Often 2 years | 2 years for full-doc | Usually not | If full-doc | Varies |
| Business returns, CPA letter or business license | No | Full-doc: returns; bank-statement: CPA letter or license | No | If self-employed | Entity documents if buying in an LLC |
| 12 or 24 months of bank statements | No | For bank-statement programs | No | If using bank-statement income | Sometimes |
| Brokerage and retirement statements (2 most recent) | For reserves | For reserves | Yes, to calculate income | For reserves | For reserves |
| Royalty, licensing, sponsorship or platform payout records | No | If applicable | No | If applicable | No |
| Current home: mortgage statement, sale contract or listing | If you own | If you own | If you own | Yes | Statements and leases on every property |
| Purchase contract, HOA contact, condo questionnaire and budget | Yes | Yes | Yes | Yes | Yes |
| Gift letter and donor statements | If gifted funds | If gifted funds | If gifted funds | If gifted funds | If gifted funds |
For more on income without W-2s, read qualify for a Las Vegas jumbo loan with no W-2s.
How does a Las Vegas jumbo loan work, step by step?
- Strategy call. We review your price range, down payment, income type, assets and the address. If you're near $832,750, we check whether more down keeps you conforming.
- Confirm the jurisdiction. Is the home in the City of Las Vegas, unincorporated Summerlin South or Henderson? That sets the tax district.
- Full documents up front. We read your income the way an underwriter will, before any lender sees it.
- Lender comparison and Loan Estimates. We price your file across wholesale lenders. You get a Loan Estimate within 3 business days of a full application (12 CFR 1026.19).
- Pre-approval and offer. Your offer carries a documented approval.
- Appraisal, title and HOA. The appraisal is ordered right after the contract. Some jumbo programs need a second appraisal above certain loan amounts. Condo buyers order the HOA questionnaire on day one.
- Underwriting and conditions. We answer conditions from the package you already sent.
- Closing Disclosure. You receive it at least 3 business days before signing.
- Sign, fund, record. The deed records with the Clark County Recorder. Then claim your primary residence with the Assessor and record a homestead declaration.
How do you choose a jumbo lender or broker in Las Vegas?
In 2025, 81 different lenders made the city's 190 jumbo purchase loans. Each sets its own credit, reserve, LTV and income rules. Use these checks on anyone you interview, including us:
- Verify licensing on NMLS Consumer Access. iQRATE Mortgages is NMLS 1862492. David Ghazaryan is NMLS 1486726.
- Confirm the 2026 limit. The one-unit line is $832,750. A quote built on $806,500 (the 2025 limit) is out of date.
- Ask how many jumbo lenders will see your file, and which programs: full-doc, bank-statement, asset-depletion, interest-only.
- Get reserves in dollars before you write an offer.
- Compare official Loan Estimates collected on the same day, line by line.
- Ask how the broker is paid. Broker compensation is disclosed on the Loan Estimate and Closing Disclosure.
iQRATE Mortgages is a Las Vegas brokerage at 6360 S Rainbow Blvd Ste 101, Las Vegas, NV 89118. We are a broker, not a lender. Our full broker checklist is on the jumbo guide and the Las Vegas mortgage broker page.

What do clients say about iQRATE Mortgages?
These are real reviews, quoted word for word. They describe our company overall. None is confirmed to be a jumbo loan.
“The best experience that I have ever had with mortgage company, David and his team are awesome and they always keep me updated on a daily basis about my mortgage process. They are professional, down to earth, helpful and they always available to answer all your questions. Thank you David and iQRate mortgages”
— Edmond B., review on Google
“David’s experience in the greater Las Vegas area has been a tremendous help in every aspect of buying my home. His work is quick, efficient, and reliable.”
— eddieyervinyan (Las Vegas, NV), 5-star review on Zillow
“By and far the best service and people. David and Andrei were instrumental in helping me buy my first home. They are efficient, organized, and highly knowledgable. They made me feel comfortable and informed throughout the entire process. We closed on my home in 2 weeks because my apartment lease was ending. Unbelievable teamwork from IQ Mortgage and can't wait to work with them again soon!”
— Anita A. (Las Vegas, NV), 5-star review on Yelp
"He was there and ensured a smooth transaction."
— Jasmin, Zillow-verified review
Our ratings: Google 5.0 from 77 reviews. Yelp 5.0 from 51 reviews. Zillow 5.00 from 9 reviews.
Read our reviews on Google, Yelp and Zillow, or on our reviews page.
Videos from David
For Las Vegas condo and high-rise buyers
Why Banks Reject Your Las Vegas Condo Hotel Loan. Why many Las Vegas condo-hotels fail conventional guidelines, and how a DSCR loan can qualify an investor on the unit's rental income instead (business purpose only). Video notes.
Your 'Rejected' Condo Is Actually A Goldmine. How investors finance non-warrantable condos in Las Vegas and Henderson when conventional and FHA loans are ruled out. Video notes.
General Las Vegas buying videos (not jumbo-specific)
Stop Paying FHA Mortgage Insurance For 30 Years. FHA vs conventional for a first home in the Las Vegas valley. Video notes.
Nevada Down Payment Help: Grant or Forgivable Loan? The two kinds of Nevada down payment assistance and the rules that usually apply. Video notes.
What does the Las Vegas jumbo data look like in charts?

Las Vegas jumbo loans: frequently asked questions
Does the jumbo line change inside the City of Las Vegas?
No. The 2026 one-unit line is $832,750 everywhere in Clark County. That includes the city, unincorporated Summerlin South, Henderson and North Las Vegas. Your jurisdiction changes your property-tax district, not the jumbo line.
What share of City of Las Vegas home purchases use jumbo financing?
About 3%. In 2025, 190 of 6,154 home purchase loans inside city limits (3.1%) were above the conforming limit. Countywide, the share was 4.0% (1,082 of 26,769). Source: iQRATE analysis of public HMDA data.
How much did City of Las Vegas jumbo borrowers put down in 2025?
Most put down 20% or more. The median loan-to-value was 80%, and 134 loans financed 80% or less. Of the 183 loans in the reported LTV ranges, 21 financed over 80% to 90% and 28 financed over 90%. Those counts include VA loans (28 of the 190), and we did not split LTV by loan type. Your own minimum depends on the lender, loan size and occupancy.
What credit score, reserves and DTI should I plan for on a Las Vegas jumbo?
Plan around a credit score near 700 or higher, about 6–12 months of reserves after closing, and a DTI commonly up to about 43%. In the 2025 metro data, about one jumbo borrower in four closed above 43% DTI. Each lender sets its own rules.
Why do City of Las Vegas jumbo applications get denied?
Debt-to-income was the top reason, in 17 of 57 denials in 2025. An incomplete application came next, with 15. Those two reasons cover 32 denials (56.1%). Credit history, collateral and insufficient cash were less common.
Is a jumbo application in Las Vegas more likely to be denied than a conforming one?
Not by the 2025 city numbers. Across all loan purposes, 16.4% of decided jumbo applications were denied, compared with 16.3% for conforming. Jumbo files still need more documentation and larger reserves.
Which Las Vegas ZIP codes have the most jumbo purchases inside city limits?
89144 led 2024–2025 with 69 jumbo purchase loans, 18.2% of its in-city purchase loans. Next came 89117, 89134, 89145 and 89138. Together, these five held 235 of 397 city jumbo purchases (59.2%).
Why aren't The Ridges, MacDonald Highlands or Ascaya in the city data?
They are outside Las Vegas city limits. The Ridges is in Summerlin South (89135), which is unincorporated Clark County. MacDonald Highlands and Ascaya are in Henderson (89012). Zillow's September 2026 top-tier typical value in 89135 was $1,762,834.
How common are VA loans above the limit in the City of Las Vegas?
Fairly common. In 2025, 28 of the 190 city purchase loans above the conforming limit (14.7%) were VA loans. Veterans with full entitlement have no VA loan limit, though individual lenders may cap loan amounts.
Do City of Las Vegas jumbo buyers choose ARMs or interest-only loans?
A real minority do. In 2025, 50 city jumbo purchase loans (26.3%) were adjustable-rate, and 34 of those had a 7-year fixed period. 32 loans (16.8%) had interest-only payments. Ask for the payment after any adjustment or interest-only period before you choose.
Do Las Vegas jumbo loans carry mortgage insurance?
Usually not standard PMI. Most jumbo lenders ask for a larger down payment instead. Some programs with lower down payments price that risk in other ways. Terms vary by lender.
Can a piggyback loan keep my Las Vegas purchase under the jumbo line?
Sometimes. Some buyers pair a conforming first mortgage at or below $832,750 with a second lien. Others put more down: on a $1,000,000 home, $167,250 or more keeps the loan conforming. We compare total cash to close and fees for each route.
Can a content creator or music producer get a jumbo loan in Las Vegas?
Yes, when the income can be documented in a way a lender accepts. Royalties, sponsorships and platform payouts must be sorted into eligible and ineligible income. Options include full-doc, bank-statement, P&L and asset-based programs.
Can I refinance a Las Vegas jumbo into a conforming loan?
Possibly. The test uses the new loan amount. If the new loan is at or below $832,750, it can be conforming even though the original was a jumbo. A refinance without an ownership change does not affect your 3% property-tax cap.
How large can a Las Vegas jumbo loan be?
Published wholesale jumbo programs extend to $5 million. In 2025, five City of Las Vegas jumbo purchase loans were $3 million or more. Maximum loan-to-value usually falls as the loan size rises.
Where can I read more about Las Vegas and Nevada loans?
These are our own guides. Each link opens a page on this site.
Which Nevada city pages should I compare?
- Nevada mortgage broker.
- Henderson mortgage broker.
- North Las Vegas mortgage broker.
- Summerlin mortgage broker.
- Boulder city mortgage broker.
- Reno mortgage broker.
- Sparks mortgage broker.
- Carson city mortgage broker.
- Mesquite mortgage broker.
- Pahrump mortgage broker.
Which iQRATE loan program pages fit a jumbo buyer?
- Jumbo.
- Las Vegas mortgage broker.
- Bank statement.
- Non-QM.
- Asset depletion loans Nevada.
- DSCR.
- VA loans.
- Investors.
- Hard money loans Nevada.
- Calculators.
- Reviews.
- Apply now.
- Contact.
- Rates and how we quote.
- Guarantees.
- BRRRR loans Las Vegas.
Which Las Vegas jumbo and luxury guides should I read?
- A DSCR loan for a Las Vegas non warrantable condo guide.
- A foreign buyers guide to Nevada rental property loans.
- A guide to de risking new construction loans in Nevada.
- A Nevada agents guide to appraisal defense systems.
- A proactive appraisal strategy for Nevada real estate agents.
- An agents guide to appraisal rebuttals in Nevada.
- Bank statements vs tax returns for a Las Vegas mortgage.
- Buying a home from a trust in Las Vegas a guide.
- California investors buying Las Vegas rentals with a DSCR loan.
- California to Las Vegas jumbo loan before selling your home.
- Covering an fha appraisal gap in Nevada without cash.
- DSCR loan reserve rules in Las Vegas Nevada explained.
- DSCR loan reserves in Las Vegas Nevada a guide for investors.
- DSCR loans finance a Las Vegas condo hotel unit.
- DSCR loans for Las Vegas condo hotels your guide.
- DSCR loans for new construction rentals in Las Vegas.
- Fha vs conventional appraisal for older Nevada homes.
- Fha vs conventional loan for a Las Vegas condo.
- Financing a Las Vegas condo hotel with a DSCR loan.
- Foreign national jumbo loans in Nevada a guide.
- Get a mortgage on a home in a trust in Nevada.
- Guide to foreign national loans in Nevada.
- Henderson jumbo loans MacDonald Highlands Ascaya Lake Las Vegas.
- How lenders average 1099 income in Las Vegas & Reno.
- How lenders combine 1099 incomes in Las Vegas & Reno.
- How to read Nevada HOA docs for a condo loan.
- Jumbo loans for a home in a trust in Las Vegas Nevada.
- Jumbo vs high balance loans in Nevada which is best.
- Jumbo vs piggyback loan in Las Vegas & Henderson Nevada.
- Las Vegas high rise condo jumbo loans and warrantability.
- Las Vegas jumbo loan down payment and reserves 2026.
- Las Vegas jumbo loans for new construction and custom homes.
- Navigating jumbo loan appraisal gaps in Reno Nevada.
- Nevada 1099 mortgage guide for gig worker income.
- Nevada condo hotel financing a guide to DSCR loans.
- Nevada DSCR loan guide for LLCs with partners.
- Nevada foreign investor portfolio loan Reno & Las Vegas.
- Nevada foreign national loan documents you need.
- Nevada itin vs foreign national loan a direct comparison.
- Nevada mortgage after business change a self employed guide.
- Nevada portfolio loans for foreign investors guide.
- Passing an fha appraisal on a Nevada fixer upper.
- Piggyback vs jumbo loan in Reno Nevada a cost guide.
- Prep s corp taxes for Las Vegas jumbo loan approval.
- Qualify for a Las Vegas jumbo loan with no W-2s.
- Summerlin jumbo loans for guard gated and golf course homes.
- Systematize appraisals for success in Las Vegas Nevada.
- Use your portfolio for a Nevada jumbo loan in 2026.
- Using a va loan to buy a Las Vegas condo in Nevada.
- Using foreign funds for a Nevada mortgage a guide.
- Using home equity to buy a second home in Reno Nevada.
- VA condo approval in Las Vegas and Henderson Nevada.
- What is a seller bridge solution in Las Vegas Nevada.
- What to do after a failed va appraisal in Nevada.
- When to apply for a self employed mortgage in Nevada.
- Why fha condo loans are denied in Las Vegas Nevada.
- Why your Nevada fha condo loan request was denied.
What other Las Vegas home loan guides do we have?
- 2025 guide Nevada DSCR investor loans.
- 720 credit score but low cash in Nevada fha vs conventional.
- A guide to buying a Las Vegas home anonymously.
- A guide to Las Vegas & Reno rental portfolio blanket loans.
- A guide to pre certified listings in Las Vegas Nevada.
- A letter of explanation can save your Las Vegas mortgage.
- A Nevada agents guide to vetting financed offers.
- A Nevada s corp guide to mortgage qualification.
- A predictable commission forecast for Reno & Las Vegas agents.
- A pros guide to vetting buyer financing in Nevada.
- Are mortgage points a waste of money in Nevada.
- Authorized user accounts & your Nevada mortgage approval.
- Avoid closing costs on a Nevada home 2026 guide.
- Best loan for a multi gen home in Las Vegas Nevada.
- Best loan to buy a Reno brrrr property in Nevada.
- Best property type for a DSCR loan in Nevada.
- Beyond 10 mortgages in Nevada a guide for investors.
- Build a commission certainty pipeline in Reno Nevada.
- Buy a Las Vegas home before you sell your current one.
- Buy a Las Vegas rental after foreclosure sooner than you think.
- Buying a Las Vegas rental with an itin investor loan.
- Bypass mortgage seasoning rules in Las Vegas & Reno.
- Can a lender revoke a mortgage commitment in Nevada.
- Can a non relative gift my down payment in Nevada.
- Can DSCR loans use casita rent in Las Vegas Nevada.
- Can manual underwriting save your Las Vegas fha loan app.
- Cash from a Nevada rental with a DSCR refinance.
- Certify your Las Vegas listing to attract more buyers.
- Clark county property tax and transfer tax on a Las Vegas DSCR rental.
- Cover fha closing costs with seller credits in Nevada.
- Credit dispute halting your Las Vegas Nevada mortgage.
- Credit mistakes that kill a mortgage in Las Vegas Nevada.
- Deed in lieu and your next mortgage in Nevada.
- Defensible diligence a listing agents guide for Nevada.
- Dpa vs seller credits for a Las Vegas Nevada home loan.
- DSCR cash out refinance to scale a Las Vegas rental portfolio.
- DSCR loan calculation for Las Vegas & Reno investors.
- DSCR loan for a Las Vegas house hack a smart guide.
- DSCR loan guide for fixer upper rentals in Nevada.
- DSCR loan guide for mid term rentals in Nevada.
Sources
- Original analysis: iQRATE Mortgages, City of Las Vegas jumbo purchase loans, 2024–2025, computed November 4, 2026 from the FFIEC/CFPB HMDA Data Browser. Geography from Census TIGERweb 2020. The method is stated above.
- Metro jumbo figures (MSA 29820), DTI split and refinance count: iQRATE HMDA analysis, as published on iqratemortgages.com/jumbo.
- Loan limits:FHFA, conforming loan limits; FHFA 2026 announcement.
- Home values:Zillow Home Value Index, ZIP level, September 2026.
- Market data:Las Vegas REALTORS, September 2026 market report.
- Transfer tax:Nevada Department of Taxation; NRS chapter 375.
- Property tax:Clark County Assessor, tax abatement (NRS 361.4723); Clark County Treasurer, tax rate by district.
- Homestead:NRS 115.010 and 115.020.
- Disclosure timing:CFPB, 12 CFR 1026.19.
- VA loan limits:VA loan limits.
- Licensing:NMLS Consumer Access, iQRATE Mortgages 1862492; David Ghazaryan 1486726.
Go deeper: - Jumbo loan program guide - Las Vegas mortgage broker - Jumbo down payment and reserves in 2026 - Summerlin jumbo loans - Henderson jumbo loans - Calculators
Talk to a Las Vegas jumbo broker
Shopping above $832,750 in Las Vegas, Summerlin or Henderson? Tell David three things: - your price range - the area - how you earn your income
He will tell you which documents to gather and which programs fit.
- Call or text (702) 766-3744
- Apply now
- Schedule a free consultation
iQRATE Mortgages · 6360 S Rainbow Blvd Ste 101, Las Vegas, NV 89118 · Mon to Fri 9 am – 5 pm; Sat and Sun by appointment only.
iQRATE Mortgages LLC, NMLS 1862492. David Ghazaryan, Mortgage Broker, NMLS 1486726. Verify licensing on NMLS Consumer Access.
iQRATE Mortgages is a mortgage broker, not a lender, and does not make credit decisions. Broker compensation is disclosed on your Loan Estimate and Closing Disclosure. This page is general information. It is not a loan offer, a rate quote or a commitment to lend. All loans are subject to credit approval, underwriting and property eligibility. Down payment, reserve, credit, debt-to-income and loan-amount requirements vary by lender and change often. Not all borrowers will qualify. Past results do not guarantee future outcomes.
No interest rates or APRs are shown. Dollar figures are arithmetic on the cited public sources, not predictions. HMDA figures describe 2024–2025 loans under the limits in force in those years. Investor, DSCR and other business-purpose loans are for non-owner-occupied property only. Local tax figures are estimates, not legal or tax advice.
Equal Housing Opportunity.