By David Ghazaryan, Mortgage Broker, NMLS 1486726 · iQRATE Mortgages, NMLS 1862492 · Updated November 9, 2026
Short answer: In Irvine, a one-unit home loan above $1,249,125 is a jumbo loan in 2026. That is the Orange County conforming limit published by the FHFA. The loan amount decides it, not the price. Public HMDA records show 536 of 1,583 first-lien purchase loans on Irvine homes were above the conforming limit in 2025. iQRATE Mortgages (NMLS 1862492) is a mortgage broker licensed in California, led by David Ghazaryan (NMLS 1486726). We compare full-doc, bank-statement, asset-depletion, adjustable-rate and interest-only jumbo options across more than 100 lenders on complex files. Call or text (702) 766-3744.
This page covers jumbo loans only. Our Irvine mortgage broker guide has Irvine's full loan data, Mello-Roos tables, property tax math and Census profile. This page covers what changes once a loan crosses $1,249,125: how many Irvine buyers cross it, how their loans are built, what underwriters check, and how to plan a file that closes.
Irvine jumbo key facts
- 2026 jumbo line, one unit, Orange County: a loan above $1,249,125 (FHFA).
- High-balance band: above $832,750, up to $1,249,125. These loans follow agency rules, not a jumbo lender's own rules.
- Irvine jumbo purchase loans: 417 in 2023, 484 in 2024 and 536 in 2025 (HMDA).
- Lenders that made at least one Irvine jumbo purchase loan in 2025: 100.
- Adjustable-rate Irvine jumbo purchase loans, 2025: 314 of 536. A 7-year fixed period was the most common choice.
- Licensed in:Nevada, California, Texas and Florida. Company NMLS 1862492. David Ghazaryan NMLS 1486726.
Our ratings: 5.0 stars from 87 reviews on Experience.com (October 2026). Google 5.0 from 77 reviews (read our Google reviews). Yelp 5.0 from 51 reviews. Zillow 5.00 from 9 reviews (read our Zillow reviews).
Next step:Apply now, schedule a free consultation or call or text (702) 766-3744.
What loan amount makes an Irvine mortgage a jumbo loan in 2026?
A loan is jumbo when the amount you borrow is above the conforming limit for the county. Irvine is in Orange County. Orange County is an FHFA high-cost area. Its 2026 one-unit limit is $1,249,125, which is also the national high-cost ceiling. You can check the figure in the FHFA conforming loan limit data, the FHFA 2026 announcement and the full 2026 county list.
That gives Irvine three loan bands, not two:
- Conforming: up to $832,750, the national baseline.
- High-balance conforming: above $832,750, up to $1,249,125. These loans follow agency rules for high-cost areas.
- Jumbo: above $1,249,125. Each lender or investor writes its own rules for credit, reserves, income and property type.
Two-to-four-unit homes have higher lines. In Orange County, a two-unit loan stays conforming up to $1,599,375. The three-unit line is $1,933,200, and the four-unit line is $2,402,625 (FHFA).
How the 2026 line sorts Irvine loan amounts (one-unit home)
| Loan amount | Loan type in Irvine | Amount above $1,249,125 | Matching 2025 Irvine HMDA size band |
|---|---|---|---|
| $800,000 | Conforming | Not above | Under $1,249,125 |
| $1,000,000 | High-balance conforming | Not above | Under $1,249,125 |
| $1,250,000 | Jumbo | $875 | $1,249,125 to $3 million |
| $5,500,000 | Jumbo | $4,250,875 | $5 million or more |
The math is the loan amount minus $1,249,125. A loan just $875 over the line is a jumbo. Property type matters too. On a two-unit Irvine home, a loan above $1,249,125 stays high-balance conforming up to the two-unit line of $1,599,375.
In a baseline county, the 2026 one-unit line is $832,750. In Irvine, it is $1,249,125. A $1,000,000 loan is high-balance conforming in Irvine. In Clark County, Nevada, a baseline county, the same loan is a jumbo.
Does the purchase price decide whether you need a jumbo?
No. Loan-to-value (LTV) is the loan divided by the home value. The same Irvine home can carry a high-balance loan for one buyer and a jumbo for another, depending on how much each borrows. Compare your planned loan amount, not the price, with $1,249,125. Each lender sets its own maximum LTV.
Want to test your own numbers? Our Irvine mortgage broker guide includes a rate-free tool that checks your numbers against the $1,249,125 limit. More rate-free tools are on our mortgage calculators page.
Can you check an Irvine price against the 2026 jumbo line?
Yes. Enter a purchase price and the share you plan to finance. The tool does simple math only. It shows the loan amount and whether that amount is above Orange County's 2026 one-unit conforming limit of $1,249,125, or above the $832,750 national baseline. If you also enter taxes, Mello-Roos, HOA dues, insurance or other assessments, it adds those monthly costs. It does not use an interest rate, quote a payment or approve a loan. The starting price is an example, not an Irvine median.
The calculator script is a page-footer payload named iqirvjumbo, not inline in this body. This estimate is not a Loan Estimate, a quote or a commitment to lend. Use the tax bill and insurance quote for the specific address.
How many Irvine home purchases use a jumbo loan?
Lenders report almost every mortgage application under the Home Mortgage Disclosure Act (HMDA). iQRATE counted the 48 census tracts whose center sits inside Irvine city limits. The method and every all-loan table are in our Irvine mortgage broker guide. Below is only the jumbo slice.
Irvine jumbo purchase loans, 2023 to 2025 (HMDA)
| Year | Jumbo purchase loans | All first-lien purchase loans | Jumbo share |
|---|---|---|---|
| 2023 | 417 | 1,513 | 27.6% |
| 2024 | 484 | 1,413 | 34.3% |
| 2025 | 536 | 1,583 | 33.9% |
Jumbo share is iQRATE arithmetic: jumbo loans divided by all first-lien purchase loans.
Three things stand out:
- Jumbo grew faster than the market. Jumbo purchase loans rose 28.5% from 2023 to 2025. All purchase loans rose 4.6%.
- Jumbo held up in a slow year. In 2024, total purchase loans fell from 1,513 to 1,413. Jumbo loans still rose, from 417 to 484.
- Irvine sits well above the county. About one in three 2025 Irvine purchase loans was above the limit. Across Orange County, 19.1% were.
Many lenders, many rulebooks. In 2025, 100 different lenders made at least one Irvine jumbo purchase loan. Each writes its own rules on credit, reserves, income and property type. A file one lender declines may fit another lender's rules. That is the main reason to have a broker shop a jumbo file.
How large are Irvine jumbo loans?
2025 Irvine purchase loans above $1,249,125, by size (HMDA)
| Loan amount | Loans | Share of loans above $1,249,125 |
|---|---|---|
| $1,249,125 to $3 million | 470 | 94.9% |
| $3 million to $5 million | 20 | 4.0% |
| $5 million or more | 5 | 1.0% |
| Total | 495 | 100% |
Shares are iQRATE arithmetic and are rounded. Roughly 19 of every 20 Irvine purchase loans above the line were under $3 million. Only 25 were $3 million or more.
Why 495 and not 536? The two counts are measured differently. These size bands are cut at the 2026 line of $1,249,125, and HMDA rounds each loan amount to the middle of a $10,000 band. Read the bands as the shape of the market, not an exact recount.
What this means for planning: most Irvine jumbo files fall in the $1,249,125 to $3 million band. Above $3 million, Irvine purchases were rare in 2025. At larger loan sizes, lenders commonly ask for more reserves, and a second appraisal or a review appraisal may be required (varies by lender).
Do Irvine jumbo borrowers choose fixed or adjustable rates?
Most chose an adjustable-rate mortgage (ARM). An ARM has a rate fixed for a set period. After that, the rate can change on a schedule, within caps.
Fixed period on Irvine jumbo purchase loans, 2025 (HMDA)
| Loan structure | Loans | Share |
|---|---|---|
| Fixed for the full term | 203 | 37.9% |
| 7-year fixed, then adjusts | 175 | 32.6% |
| 5-year fixed, then adjusts | 69 | 12.9% |
| 10-year fixed, then adjusts | 42 | 7.8% |
| 3-year fixed, then adjusts | 28 | 5.2% |
| Other or not reported | 19 | 3.5% |
Adding the four ARM rows gives 314 of 536 Irvine jumbo purchase loans, or 58.6%. The 7-year ARM alone was 175 of those 314, or 55.7%. For contrast, 44.0% of all 2025 Irvine purchase loans were adjustable. In the Las Vegas metro, 29.8% of 2025 jumbo purchase loans were ARMs, per our Las Vegas jumbo loan guide. The two areas were measured differently (a city's tracts versus a whole metro), so treat that comparison as context.
When do 2025 Irvine jumbo ARMs reach the end of their fixed period?
| Fixed period | Irvine jumbo ARMs, 2025 | Fixed period ends in |
|---|---|---|
| 3 years | 28 | 2028 |
| 5 years | 69 | 2030 |
| 7 years | 175 | 2032 |
| 10 years | 42 | 2035 |
Years are simple arithmetic from a 2025 start. The exact date depends on each loan's note.
How to use an ARM with your eyes open:
- Match the fixed period to your plan. An ARM can suit a buyer who expects to sell, move or refinance before the fixed period ends. The risk is keeping the loan past that point.
- Read the caps. Your Loan Estimate shows how often the rate can change and how far it can move. Ask to see the highest possible payment before you choose.
- Plan the exit early. As the fixed period nears its end, compare a new ARM, a fixed-rate loan and, if your balance has come down, a high-balance loan.
Interest-only jumbo loans. Some lenders allow interest-only payments for an initial period. After it ends, payments rise to cover principal over the remaining term. You do not pay down principal through your payments during that period. Lenders usually ask for more down and more reserves. Read our California interest-only jumbo loan guide before you choose one.
Why do Irvine loan applications get denied, and what does that mean for a jumbo file?
The HMDA data on this page does not split out denials for jumbo applications. The figures below cover all Irvine applications of every loan type in 2025, not jumbo loans alone.
- 19.9% of all Irvine applications decided in 2025 were denied. Home purchase applications were denied 11.6% of the time.
- Of 1,034 denials, debt-to-income (DTI) was the first reason given in 51.3%.
- Incomplete applications came next at 12.3%, then collateral (appraisal) at 11.5%.
The full denial tables are in our Irvine mortgage broker guide.
Why this matters more on a jumbo: DTI is your monthly debts divided by your monthly income. Your new housing payment counts. So do the property tax, any Mello-Roos special tax, insurance and every HOA due. On a larger loan, the housing line is larger too.
Debt-to-income is simple arithmetic, not a quote or a lender's limit. Each lender sets its own maximum ratio. In an Irvine file, the debts include the full housing line: tax, any special tax, insurance and HOA dues.
How we prepare an Irvine jumbo file before you write an offer:
- Use the real tax figure. We take the Mello-Roos amount from the tax bill or the seller's disclosure, not a guess.
- Count every HOA. Most Irvine homes pay a master HOA plus a village HOA. Lenders count both.
- Match the income method to the borrower. A business owner whose returns show write-offs may fit a bank-statement program. A buyer with large investments may fit asset depletion.
- Plan the appraisal. Homes with few comparable sales, such as new construction, can take longer to value.
- Send a complete file. A full document list at the start avoids the second most common denial reason.
How do Mello-Roos and HOA dues change a jumbo approval?
Many Irvine villages carry a Mello-Roos special tax from a community facilities district (CFD). It is billed with your property tax, and lenders count it. In the Great Park neighborhoods, the City of Irvine says the charge can rise up to 2% a year. Village-level figures and worked examples are in the Mello-Roos section of our Irvine mortgage broker guide.
On a jumbo loan, these costs hit your file twice:
- In your debt-to-income ratio. The lender adds the base property tax, the special tax, insurance and both HOA dues to your monthly housing payment.
- In your reserves. Jumbo lenders measure reserves in months of the full housing payment: principal, interest, taxes, insurance and HOA dues. A special tax and two HOA dues raise the dollar amount you need to keep after closing.
Two more cash items to plan for:
- Supplemental tax bill. Prop 13 resets your assessed value to your purchase price. Expect a supplemental tax bill after you close.
- Tax escrow at closing. Escrow for taxes at your new Prop 13 value, plus the special tax, are among the largest prepaid items. Our closing costs by state page explains how cash to close is built.
Get the exact special tax figure before you write an offer. It changes by village, home type and the year the home was built.
How much in reserves do Irvine jumbo lenders want, and what counts?
Reserves are liquid funds left after your down payment and closing costs. They are one of the biggest differences between jumbo and conforming loans. Lenders often want about 6 to 12 months of the full housing payment left after closing. They may want more on larger loans or if you own several financed properties (varies by lender).
- What usually counts: checking, savings, money market and brokerage accounts, plus vested retirement accounts, often at a discounted value.
- What usually doesn't count: gift funds, HELOC or other borrowed money and, in many cases, business assets unless the lender accepts a CPA letter.
- What raises the requirement: a larger loan, second-home or investment occupancy, non-QM documentation and each additional financed property.
- Seasoning: lenders commonly want about two months of statements showing the funds. Large recent deposits need a paper trail.
- Funds from abroad: plan on statements, wire records and a currency conversion.
Ask for your reserve requirement in dollars, not just months, before you write an offer. If you plan to move money from a brokerage account or sell another property, tell us first.
Which income paths work for an Irvine jumbo loan?
As our Irvine guide notes, Irvine buyers include tech and biotech staff, UC Irvine faculty, business owners and families from abroad. Many have strong finances that do not fit a simple W-2 file. Jumbo and non-QM lenders offer other ways to show your ability to repay.
| Income path | Often used by | What the lender looks at | Read more |
|---|---|---|---|
| Full-doc jumbo | Salaried borrowers | Pay stubs, W-2s and tax returns | How to shop for a California jumbo loan |
| Bonus and vested stock | Employees paid partly in bonus or stock | A lender may average two years of bonus income. Vested stock can count as an asset. | Vested stock and a California jumbo |
| 12- or 24-month bank-statement jumbo | Business owners and 1099 earners whose returns show write-offs | Deposits on personal or business statements, with an expense factor on business accounts. A CPA letter or P&L is commonly required. | Bank statement loans |
| P&L-only | Some independent contractors and business owners | A CPA-prepared profit-and-loss statement (varies by lender) | P&L loans |
| Asset-depletion jumbo | Retirees, people between business sales, investors with large portfolios | Eligible liquid assets converted into a monthly qualifying income | Asset depletion loans (Nevada guide) |
| Foreign national or foreign income | Buyers with income or assets abroad, or no U.S. credit score | Foreign bank letters, statements, wire records and a currency conversion | Foreign funds for a California jumbo |
Non-QM programs usually carry their own minimum credit scores and larger down payment and reserve requirements than full-doc jumbo loans. Pricing differs too, so we compare a full-doc option and a non-QM option side by side when a file could fit either. See our non-QM loans, portfolio loans and self-employed borrower pages.
David on borrowers whose income does not look like a paycheck:
“That doesn't mean we can count every dollar that enters the account. It means we need to understand which receipts are eligible income and find a lender whose documentation requirements fit the borrower.”
“I started in the mortgage industry in 2005 and have worked in tax preparation since 2008, and that combination matters on files like these.”
More on complex income: qualifying with RSUs for a California jumbo, using unvested RSUs, combining business incomes, excluding business debt, jumbo loans for high-revenue businesses and jumbo loans with unique assets.
Should an Irvine buyer choose high-balance, jumbo, or a first and second lien?
The limit applies to the loan amount, so some Irvine buyers can keep a first mortgage at or below $1,249,125 even on a higher-priced home. Others combine a first mortgage at or below the line with a second lien. Which route costs less depends on your credit, reserves, how long you will keep the loan and the pricing available that day.
| Question | High-balance conforming | Jumbo | First mortgage plus second lien |
|---|---|---|---|
| Loan amount, one unit | Above $832,750, up to $1,249,125 | Above $1,249,125 | First mortgage at or below $1,249,125, with a second lien on top |
| Who writes the rules | Agency guidelines | Each lender or investor | Two loans, each with its own terms |
| Income documents | Standard full documentation | Full-doc, or non-QM paths such as bank-statement, asset-depletion or P&L | Both loans must be approved |
| Reserves | Follow agency guidelines and your file | Often 6 to 12 months of payments after closing (varies by lender) | Set by the lender on each loan |
| Condo or townhome project | Must pass the lender's project review | Must pass the lender's project review | Each lender reviews the property |
We lay out the total cash to close and the fees for each route on official Loan Estimates before you decide. For a closer look, read high-balance vs. jumbo loans in Los Angeles and San Diego. Los Angeles County shares Orange County's $1,249,125 limit.
What usually goes wrong on an Irvine jumbo file, and how is it fixed?
Most jumbo problems are not about credit scores. They come from documentation and structure. Most can be solved if they are caught before escrow.
- Reserves fall short after closing. Buyers plan the down payment and closing costs but forget the months of payments the lender wants left over. Moving a brokerage account into your name or waiting for a bonus can fix it.
- Large deposits cannot be sourced. Transfers between your own accounts are easy to document. Cash deposits, business-to-personal transfers and wires from abroad take longer.
- Self-employed income drops on paper. Write-offs that lower your tax bill also lower qualifying income. A bank-statement or asset-depletion jumbo may qualify the same borrower another way. See California jumbo loan denied? Use bank statements instead.
- The appraisal comes in low. A lower value means more cash, a price renegotiation or a different lender. Larger loans may need two appraisals or a review appraisal.
- The condo or townhome project does not pass review. Lenders review the HOA budget, reserves and any lawsuits. Order the HOA documents early. See our jumbo condo guide for Los Angeles and San Diego.
- The builder's timeline slips. On new construction, the final price and completion date can move. Build the loan around the loan amount early.
- Your current home has not sold. Carrying two housing payments raises your DTI. Options include a bridge loan, a HELOC on your current home or qualifying with both payments (varies by lender). See buy before you sell in California.
- The house has unpermitted work. See jumbo loans for a home with unpermitted work in California.
David's approach when another lender has already said no:
“I don't begin by assuming the first lender made a mistake. I find out exactly why it couldn't approve the transaction: income calculation, insufficient reserves, restricted stock, a debt-to-income limit, or a property that didn't meet appraisal requirements. Those are very different problems.”
“A successful strategy starts with the financial facts, not with submitting the same file to another bank.”
Watch: Why banks deny your jumbo loan despite high revenue. Also read why Los Angeles lenders devalue income on jumbo files.
Can you refinance an Irvine jumbo loan, or tap equity without touching it?
- The line follows the new loan amount. If you have paid your balance down, or bring cash to the refinance, a new loan at or below $1,249,125 is high-balance conforming, even if your original loan was a jumbo.
- Cash-out versus rate-and-term. Lenders usually allow a lower maximum loan-to-value on a cash-out refinance than on a rate-and-term refinance.
- ARMs nearing the end of the fixed period. Each of the 314 Irvine jumbo ARMs from 2025 will reach this point if the owner keeps the loan. Before the first adjustment, compare a new ARM, a fixed-rate jumbo and, if the balance allows, a high-balance loan.
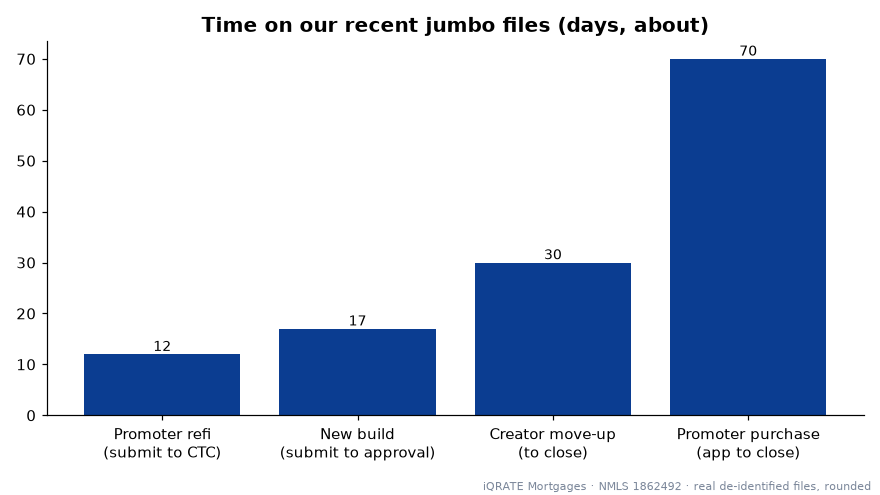
- A standalone HELOC. A standalone HELOC is a separate line, so the first mortgage stays where it is. We closed a $400,000 standalone HELOC in Orange County on a home worth about $1.44 million. It reached clear-to-close in 8 days. Across all Irvine owners, lenders opened 902 Irvine HELOCs in 2025.
See our refinance page or call (702) 766-3744 to compare options. Terms vary by lender.
Can veterans use VA financing above $1,249,125?
Often, yes. Veterans with full VA entitlement have no VA loan limit, per the VA loan limits page. Individual lenders may still set their own maximum loan amounts. Compare a VA option with a conventional jumbo before you choose. See our VA loans page.
What should Irvine investors and second-home buyers know?
- Short-term rentals are out. Irvine's Zoning Code bans rentals of 30 days or less in residential zones. Plan an Irvine rental on long-term rent.
- Occupancy changes the rules. Second-home or investment occupancy usually raises the reserve requirement.
- Rent-based qualifying. If the property's rent, not your personal income, should qualify the loan, see our DSCR loans page. Investor loans are business-purpose financing for non-owner-occupied property only.
- Prepayment penalties. Owner-occupied jumbo loans rarely carry one. Some investor loans do. As David puts it: “A loan that saves you money today can become expensive if you need to refinance or sell before a prepayment penalty expires.”
- Title in a trust or LLC. Read buying a California home in a trust and closing a jumbo loan in an LLC in California. More investor topics are on our investors page.
Moving between Irvine and Nevada? Watch the jumbo line drop
The jumbo line changes at the state line. Orange County's one-unit line is $1,249,125. In Clark County, Nevada, it is $832,750, and Nevada has no high-balance tier in 2026. A loan that is high-balance in Irvine can be a jumbo in Las Vegas, in Henderson, Nevada, or in Reno.
Measured against Clark County's 2026 line of $832,750, a $1,000,000 loan is a jumbo. Against Irvine's one-unit line of $1,249,125, the same loan is high-balance conforming, not jumbo.
Context from our Nevada data: in 2025 the Las Vegas metro had 1,088 jumbo purchase loans. That was 4.04% of 26,898 first-lien purchase loans, with a median jumbo loan of $1,135,000. In Irvine, 33.9% of 2025 purchase loans were above the limit. The Irvine figure covers city tracts and the Las Vegas figure covers a whole metro, so treat the gap as context, not a ranking.
- Buy before you sell: options include a bridge loan, a HELOC on your Irvine home or qualifying with both payments (varies by lender). See California to Las Vegas: a jumbo loan before selling your home and buy a Las Vegas home before you sell your current one.
- One team on both sides: iQRATE is licensed in both California and Nevada.
- Nevada jumbo data: our Las Vegas jumbo loan guide covers Clark County. We publish separate city data for inside Las Vegas city limits, for Henderson, Nevada, for North Las Vegas, for Reno, for Sparks and for Carson City.
Nevada jumbo guides for a move from Irvine
- Jumbo vs. high-balance loans in Nevada: which is best?
- Jumbo vs. piggyback loan in Las Vegas and Henderson, Nevada
- Get a Reno and Incline Village loan with California income
- Henderson jumbo loans: MacDonald Highlands, Ascaya and Lake Las Vegas
- Summerlin jumbo loans for guard-gated and golf course homes
- Jumbo loans for new construction and custom homes in Las Vegas
- Las Vegas high-rise condo jumbo loans: how warrantability works
- Use your portfolio for a Nevada jumbo loan in 2026
- Qualify for a Las Vegas jumbo loan with no W-2s
- Navigating jumbo loan appraisal gaps in Reno, Nevada
- Foreign national jumbo loans in Nevada
- Nevada mortgage broker pages: Nevada, Las Vegas, Henderson, Nevada, Summerlin and Reno.
Real files from David's desk
These are real closed loans, told without names and with figures rounded. None of them is an Irvine jumbo loan. Each one carries only the location its source names. They show how hard jumbo files get solved. They are not a promise about your loan.
Across our files: in summer 2025 we closed an owner-occupied Nevada jumbo purchase, application to funding in about nine weeks. A California jumbo purchase closed in 22 days. In Henderson, Nevada, we worked with a full-time online content creator buying a roughly $3 million home, whose income did not come from a paycheck.
California's Central Valley: a new-build jumbo qualified on one income
Two names on the application. Then one of them stopped counting.
The stakes: In early 2026 a couple was buying a brand-new home from a builder in California's Central Valley, priced near $2.5 million.
Where it almost fell apart: The builder would not set the final price until the house was nearly done. Then the income review showed the co-borrower's business was running at a loss. That loss could sink the debt ratio.
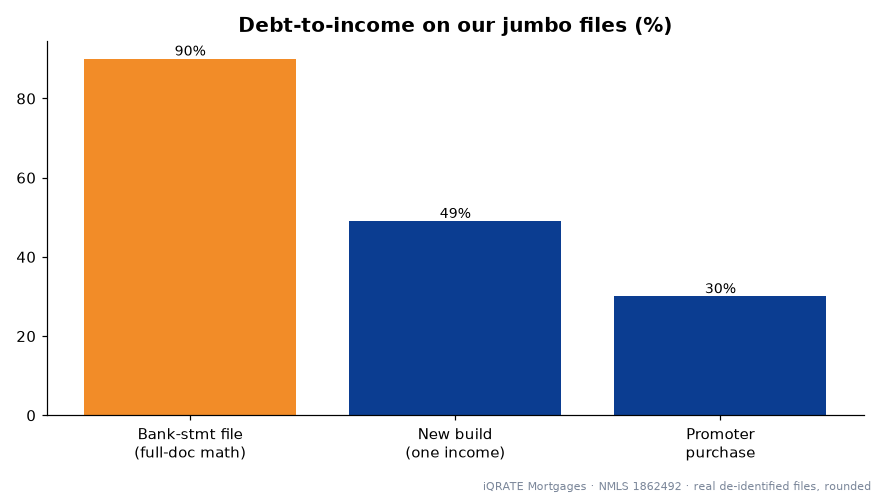
The turn: We built the whole file around the loan amount months ahead. Then we qualified the loan on one borrower's income alone. The debt ratio landed near 49%, inside the limit.
The payoff: About $2 million in jumbo financing moved from submission to approval in about two and a half weeks.
Why it matters in Irvine: The Great Park and Portola Springs areas are still adding homes, often with builder incentives and Mello-Roos. Builder timing and a co-borrower's business income both need a plan months ahead.
Las Vegas: a content creator who grew into a jumbo
The income was real. The paperwork just had not caught up yet.
In spring 2023 a self-employed social media content creator came to us to buy a first home. One older tax year showed low income and capped the pre-approval near $400,000. We did not force it. The client filed the next year's return first. We recalculated two years of income and counted a car payment made through the business, so underwriting would find no surprises. In spring 2024 the client bought a Las Vegas home near $600,000.
In spring 2026, with a bigger business, the client came back and bought a Las Vegas home with a jumbo loan near $2 million. At that size the file went to a credit committee and through several approval revisions. The loan amount never moved. It closed in about a month.
Las Vegas: lumpy income on a luxury jumbo purchase
In summer 2025 a self-employed entertainment and event promoter wanted a luxury primary home in Las Vegas, with a jumbo loan near $2.4 million. Self-employed income does not arrive like a paycheck. We built the file around reserves and a clear income story. The appraisal came back a bit above the price. The debt ratio landed near 30%. The purchase closed about ten weeks after application.
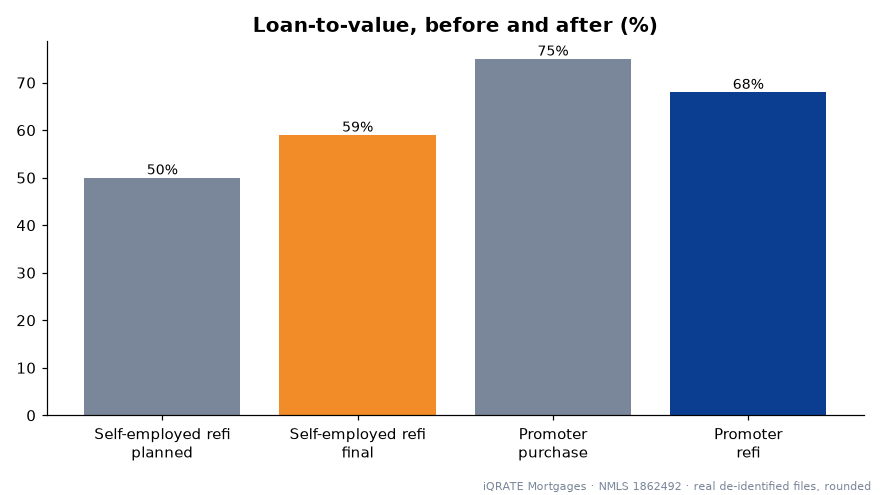
In summer 2026 the client returned for a no-cash-out refinance. The loan-to-value dropped to about 68%, and the file went from submission to clear-to-close in about 12 days.
Las Vegas: an appraisal that came in low
The appraisal came back, and the room went quiet.
In 2025 a self-employed Las Vegas homeowner was refinancing about $1.1 million. Their tax returns did not show their real cash flow, so we used 12 months of bank statements instead. We expected a value near $2.2 million. The appraisal said about $1.85 million. In one email, the loan-to-value jumped from 50% to about 59%. Because the loan started at low leverage, there was room to absorb the hit. We held the loan amount where it was, and the loan funded in winter 2025.
Why it matters in Irvine: Irvine buyers brought a lot of equity in 2025. Across all Irvine purchase loans, the median loan was 69% of the home's value. Equity is what gives a file room when an appraisal disappoints.
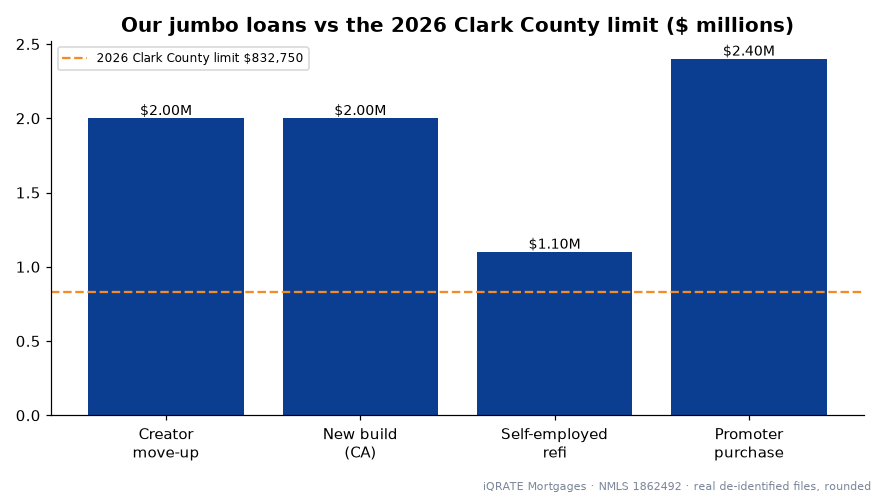
Loan sizes from our own files, shown against the Clark County, Nevada line of $832,750. In Irvine the one-unit line is higher, at $1,249,125.
A gift-funded jumbo that looked like a no
On paper, the answer was no. The paper was the problem.
In 2024 a family needed a loan near $775,000, a jumbo. The down payment was a gift from family. Measured the full-doc way, the debt ratio came out near 90%, and no full-doc lender approves that. We switched to business bank statements to show income and documented the family gift step by step. The loan closed in summer 2024. In fall 2025 the borrower came back and refinanced into a high-balance conventional loan.
Las Vegas valley: income that does not look like a paycheck
One of David's most unusual clients was a YouTube gamer buying a home in the Las Vegas valley for roughly $3 million. The client's team later came back about refinancing that primary residence. The challenge was making sure the lender understood the real financial picture rather than judging the client's ability to repay by a job title. David has also worked with a music producer and an Instagram influencer. A producer's revenue might arrive through royalties, licensing agreements, production fees and business entities. An influencer may receive advertising revenue, sponsorship payments and other business income.
California files that stayed under the line
- Burbank: a condo purchase with a $918,000 loan. Los Angeles County shares Orange County's $1,249,125 limit, so the loan was high-balance conforming, not jumbo. Many Irvine condos and townhomes can fit the same way.
- Newport Beach: a $970,000 refinance, one of 15 jumbo-size loans we closed from 2020 to 2023. At today's Orange County line, a loan of that size sits in the high-balance band.
- Orange County: the $400,000 standalone HELOC described above, clear-to-close in 8 days.
These are real files. Names and details are removed, and figures are rounded to protect client privacy. Past results do not guarantee future outcomes. All loans are subject to credit approval. Investor loans are for business purposes only. Equal Housing Opportunity.
How should you compare Irvine jumbo brokers and lenders?
Use this checklist with anyone you interview, including us.
| What to check | Why it matters on an Irvine jumbo | Question to ask | How iQRATE handles it |
|---|---|---|---|
| California license | Only licensed companies and loan officers can arrange your loan | What are your company and personal NMLS numbers? | Company NMLS 1862492; David Ghazaryan NMLS 1486726, both searchable on NMLS Consumer Access |
| The correct 2026 line | Treating $832,750 as the jumbo line is wrong in Orange County | What is the 2026 one-unit limit in Orange County? | $1,249,125, per FHFA |
| Number of lenders | 100 lenders made at least one Irvine jumbo purchase loan in 2025, each with its own rules | How many jumbo lenders will you quote my file with? | More than 100 lenders on complex files |
| Full monthly cost | Lenders count the special tax and every HOA in your debt ratio | Will you use my exact Mello-Roos figure and both HOA dues? | We price the file with tax, Mello-Roos, insurance and HOA dues included |
| Income method | Many Irvine buyers are self-employed or paid partly in stock | Can you do full-doc, bank-statement and asset-depletion jumbo? | Yes; terms vary by lender |
| ARM terms | 314 of 536 Irvine jumbo purchase loans in 2025 were ARMs | What are the caps, and what is the highest possible payment? | Your Loan Estimate shows the caps. Ask to see the highest possible payment before you choose. |
| High-balance comparison | Many Irvine loans sit below the line | Can my loan stay at or below $1,249,125? | We run both scenarios side by side |
| Written comparison | Verbal quotes are not binding | Will I get Loan Estimates I can compare line by line? | Yes, within 3 business days of application |
| Compensation | Broker pay must appear on the Loan Estimate | How are you paid on this loan? | Disclosed on the Loan Estimate and Closing Disclosure |
Red flags on an Irvine jumbo quote:
- A quote that treats $832,750 as the jumbo line for an Irvine home.
- A rate quoted before anyone has reviewed your credit, income, assets and the property.
- No mention of reserves, appraisal review or condo project review on a large loan.
- Pressure to sign an intent to proceed before you compare Loan Estimates.
- A lender with one program that calls every other option impossible.
More help: how to shop for a jumbo loan in California.
How does an Irvine jumbo loan move from first call to funding?
- Strategy call. Call or text (702) 766-3744. Tell us the price range, the area and how you earn your income. We check whether your loan can stay at or below $1,249,125.
- Pre-approval with documents reviewed. We pull credit and review income and assets up front. Your agent can send the written pre-approval with your offer.
- Lender comparison. As a broker, we price your file with many lenders. You see the full monthly cost, including base tax, Mello-Roos, insurance and both HOA dues.
- Loan Estimate. You receive it within 3 business days of application (Regulation Z, 12 CFR 1026.19).
- Contract and appraisal. Once you are under contract, the appraisal is ordered right away. Larger loans may need a second appraisal. You get a copy of each appraisal promptly on completion, or 3 business days before closing, whichever is earlier (Regulation B, 12 CFR 1002.14).
- Underwriting and conditions. The underwriter reviews income, reserves, the HOA or condo project and title. Fast answers keep the file moving.
- Closing Disclosure and funding. You receive the Closing Disclosure at least 3 business days before signing (12 CFR 1026.19). Then you sign with escrow and the loan funds.
Higher-priced loan test. Under 12 CFR 1026.35, a jumbo first mortgage counts as higher-priced when its annual percentage rate is 2.5 or more percentage points above the average prime offer rate for a comparable loan. The threshold for a conforming loan is 1.5 points. Higher-priced loans carry extra appraisal and escrow rules, and some lenders will not make them. That is one more reason to compare offers.
What documents does an Irvine jumbo lender ask for?
| Document | W-2 employee | Self-employed, full doc | Bank-statement jumbo | Asset-depletion jumbo | Buyer with funds abroad |
|---|---|---|---|---|---|
| Government ID | Yes | Yes | Yes | Yes | Yes |
| Pay stubs and W-2s | Yes | If any W-2 income | No | No | If employed in the U.S. |
| Personal tax returns | Often 2 years | Usually 2 years | Usually not | Usually not | Varies |
| Business tax returns | No | Usually 2 years | No | No | If self-employed |
| 12 or 24 months of bank statements | No | No | Yes | Statements for the qualifying assets | If using bank-statement income |
| Brokerage and retirement statements | For reserves | For reserves | For reserves | Yes, to calculate income | Yes |
| Stock vesting records | If counting vested stock | No | No | If counting vested stock | No |
| CPA letter or business license | No | Sometimes | Often | No | If self-employed |
| Wire records and currency conversion | No | No | No | No | Yes |
| Gift letter and proof of transfer | If gifted funds | If gifted funds | If gifted funds | If gifted funds | If gifted funds |
| Mello-Roos disclosure and HOA statements | Yes | Yes | Yes | Yes | Yes |
Requirements vary by lender and program. If you are selling a current home, add a signed sale contract or listing agreement. For foreign documents, see foreign docs for a San Diego jumbo loan.
What do clients say about working with iQRATE?
These are real reviews, quoted word for word. Two reviewers are from Menifee and Los Angeles in California. Several others are from Nevada, and some list no location. They describe working with David Ghazaryan and the iQRATE team overall. None is confirmed to be an Irvine jumbo loan, and they are not a promise about your loan.
“David and Andrei and team were very knowledgeable and really helped in the whole process. Even though the economy is going through a rough time they were able to explain every detail and really looked out for our best interest! I would highly recommend their team as they will find a way to get it done!”
— Lydia Z. (Menifee, CA), 5-star review on Yelp
“Very efficient and transparent service. They go above and beyond to deliver the loan closure on time even in a very tight time line. Also very resourceful and knowledgeable staff. I'll go to them again next time I need a loan.”
— Rita S. (Los Angeles, CA), 5-star review on Yelp
“Well I’ve known David for many years. His office prepares my taxes. I had been putting off buying a home since I am a 1099 sales person. I thought mortgages were for wage earners. Never really thought I would qualify. They I mentioned to him in a conversation that I couldn’t get a home, because of the type of income I have and all these reasons. In less than 10 minutes he had me qualified. Had to pay a couple of credit cards off, that was it, I own a home now. The only regret I have is not asking him sooner. This guy knows his numbers, taxes, rules and whatever else goes into that paperwork nightmare. Needless to say, I highly recommend him.”
— garik 82 (Las Vegas, NV), 5-star review on Zillow

“iQrate Mortgage and all of their staff work very hard to make sure every single person that walks into their office leaves with ALL their questions answered. I just completed my refinance with iQRate Mortgage and I am extremely happy of the turnaround. They are fast, honest, and fair. I highly recommend everyone to their office, you will not regret it.”
— Marine G. (South Shores, Las Vegas, NV), 5-star review on Yelp

“Outstanding service with the help from this team! Everything was smooth, effortless, and headache free! They answered all my questions with ease & I will recommend friends and family as well! I most definitely will continue using this company for future mortgage needs!”
— Ryan L., 5-star review on Google
“Great professional work! Because of exceptional coordination from Andrei and the team, our escrow was closed seamlessly several days earlier. All our questions and concerns were addressed promptly. My husband and I would highly recommend this team to whoever is looking for a new mortgage or refinancing.”
— Oksana K., 5-star review on Google
“David was very professional and went above and beyond to make sure I understand the loan procedure. In addition, he went with me to my closing because I expressed that I would be more comfortable with him there to explain the documents to me. He was there and ensured a smooth transaction. Everything completed as expected. I would definitely recommend him to my friends and family.”
— Jasmin (Las Vegas, NV), 5-star review on Zillow
Our ratings: 5.0 stars from 87 reviews on Experience.com (October 2026). Google 5.0 from 77 reviews. Yelp 5.0 from 51 reviews. Zillow 5.00 from 9 reviews. Read our Google reviews, read our Zillow reviews or see our client reviews page. Questions? Call or text (702) 766-3744.
Irvine jumbo loan FAQs
What loan amount is a jumbo loan in Irvine in 2026?
For a one-unit home, any loan above $1,249,125 is a jumbo loan, based on FHFA's 2026 Orange County limit. Two-, three- and four-unit homes have higher lines: $1,599,375, $1,933,200 and $2,402,625.
Is a $1.1 million loan a jumbo loan in Irvine?
No. A $1.1 million loan falls in Orange County's high-balance band, which runs from above $832,750 up to $1,249,125. It follows agency rules. In a baseline county such as Clark County, Nevada, the same loan would be a jumbo.
Are jumbo loans becoming more common in Irvine?
Yes. Irvine jumbo purchase loans rose from 417 in 2023 to 484 in 2024 and 536 in 2025 (HMDA). That is a 28.5% increase, while all Irvine purchase loans rose 4.6%.
How big is a typical Irvine jumbo loan?
Most fall between $1,249,125 and $3 million. In 2025's size bands, 470 of the 495 Irvine purchase loans above $1,249,125 were under $3 million. Twenty were $3 million to $5 million, and five were $5 million or more.
Do most Irvine jumbo borrowers choose an ARM?
In 2025, yes. 314 of 536 Irvine jumbo purchase loans were adjustable, about 58.6%. The 7-year fixed period was the most common choice, on 175 loans. 203 loans were fixed for the full term.
What happens when my Irvine jumbo ARM's fixed period ends?
The rate can change on the schedule and within the caps in your note. Before the first adjustment, compare a new ARM, a fixed-rate jumbo and, if your new loan would be at or below $1,249,125, a high-balance loan.
Are Irvine jumbo denials mostly about debt-to-income?
We don't have jumbo-only denial data for Irvine. For all Irvine applications of every loan type in 2025, debt-to-income was the first reason in 51.3% of 1,034 denials. On a jumbo, the larger housing payment, special tax and HOA dues make DTI planning even more important.
How does Mello-Roos affect my jumbo reserves?
Jumbo reserves are counted in months of the full housing payment, and that payment includes the special tax and HOA dues. A higher special tax raises the dollars you need left after closing. Get the exact tax figure from the tax bill or the seller's disclosure.
Can I keep my Irvine loan out of jumbo territory?
Often, yes. The line applies to the loan amount, so a first mortgage at or below $1,249,125 is high-balance conforming. Some buyers add a second lien. We compare total cash to close and fees for each route on official Loan Estimates.
Can I get an Irvine jumbo loan if I'm self-employed?
Yes, through programs such as 12- or 24-month bank-statement jumbo, P&L-only or asset-depletion loans. These have their own credit, down payment and reserve rules (varies by lender).
Does vested stock help me qualify for an Irvine jumbo loan?
Vested stock can count as an asset, which helps with reserves. A lender may also average two years of bonus income. How stock pay counts as income depends on the lender. See our guide to qualifying with RSUs for a California jumbo.
Can a veteran get a loan above $1,249,125?
Veterans with full VA entitlement have no VA loan limit. Lenders may set their own maximum loan amounts, so compare a VA option with a conventional jumbo.
Can I refinance my Irvine jumbo into a high-balance loan?
Yes, if the new loan amount is at or below $1,249,125. That can happen after you pay the balance down or bring cash to the refinance. Terms vary by lender.
Will a large Irvine jumbo need two appraisals?
Sometimes. Larger loans may need a second appraisal or a review appraisal. You are entitled to a copy of each appraisal promptly on completion, or three business days before closing, whichever is earlier (12 CFR 1002.14).
Is iQRATE licensed to arrange jumbo loans in Irvine?
Yes. iQRATE Mortgages (NMLS 1862492) is licensed in California to arrange and broker mortgage loans. It is also licensed in Nevada, Texas and Florida. David Ghazaryan's NMLS number is 1486726. iQRATE is a broker, not a lender, and does not make credit decisions. You can verify both numbers on NMLS Consumer Access.
How do I start an Irvine jumbo loan with iQRATE?
Call or text (702) 766-3744, apply now or schedule a free consultation. Tell us the price range, the area and how you earn your income. We will tell you which documents to gather and whether high-balance or jumbo fits you better.
More iQRATE guides for Irvine jumbo borrowers
California jumbo guides
- Jumbo loans: all articles
- Jumbo loan in a trust: a guide for California buyers
- California jumbo loan in a living trust
- Anonymous jumbo loans in California: a privacy guide
- Anonymous jumbo loans in Beverly Hills and La Jolla
- Beverly Hills jumbo loan: trust vs. LLC for privacy
- E-2 visa jumbo loans in California
- Foreign income jumbo loans in San Diego
- How to use RSU income for a San Jose jumbo loan
- How stock volatility affects a San Jose jumbo loan
- Is your San Francisco condo blocking your jumbo mortgage?
Videos
- Jumbo loans and trusts: why your mortgage terms stay fixed
- Why lenders are denying your jumbo trust loan
- All iQRATE videos
iQRATE California city pages
- California mortgage broker
- Irvine mortgage broker
- Southern California: Anaheim, Long Beach, Los Angeles, Beverly Hills, Pasadena, Riverside, Temecula, Coachella Valley
- San Diego County: San Diego, Carlsbad, Oceanside
- Bay Area: San Jose, San Francisco, Oakland, Fremont
- Sacramento and the Central Valley: Sacramento, Roseville, Stockton, Modesto, Fresno, Bakersfield
Tools and company

 Shopping for an Irvine home where the loan will be above $1,249,125? Call or text David Ghazaryan (NMLS 1486726) at (702) 766-3744, apply now or schedule a free consultation. We compare full-doc, bank-statement and asset-depletion jumbo options across many lenders. We build your numbers with the real Mello-Roos and HOA figures before you write an offer.
Follow iQRATE: Facebook ·
 YouTube ·
 Instagram ·
 LinkedIn: iQRATE Mortgages
Sources
- FHFA: conforming loan limit data, 2026 conforming loan limit announcement and full 2026 county list.
- FFIEC HMDA Data Browser, Orange County loan-level data, 2023 to 2025, analyzed by iQRATE for the 48 census tracts whose center sits inside Irvine city limits (U.S. Census Bureau TIGERweb). CFPB, about HMDA data. Checked November 4, 2026. Method and all-loan tables: Irvine mortgage broker guide.
- City of Irvine, Great Park CFD No. 2013-3 special tax information, as summarized in our Irvine guide.
- U.S. Department of Veterans Affairs, VA home loan limits.
- Federal rules: Regulation Z, 12 CFR 1026.19 (Loan Estimate and Closing Disclosure timing) and 12 CFR 1026.35 (higher-priced mortgage loans). Regulation B, 12 CFR 1002.14 (appraisal copies).
- Las Vegas metro jumbo figures: iQRATE analysis of public HMDA data, published in our Las Vegas jumbo loan guide.
Figures on this page are public records and simple arithmetic. They are not a quote, an offer of credit or a prediction. This page does not show loan pricing or payment amounts. Pricing depends on your full application and the day you lock, and it appears on your Loan Estimate. Credit, reserve and documentation requirements vary by lender and change often. Not all borrowers will qualify. iQRATE Mortgages is a mortgage broker, not a lender, and does not make credit decisions. Local tax facts are general information, not legal or tax advice.
Written by David Ghazaryan, Mortgage Broker, NMLS 1486726. iQRATE Mortgages LLC, NMLS 1862492, 6360 S Rainbow Blvd Ste 101, Las Vegas, NV 89118. (702) 766-3744. Licensed in Nevada, California, Texas and Florida. Updated November 9, 2026. This page is general information. It is not a loan offer, and this is not a commitment to lend. All loans are subject to credit, property and underwriting approval. Investor loans are for business purposes only. Verify licensing on NMLS Consumer Access. Equal Housing Opportunity.
Privacy Policy · Terms & Conditions · Transparency and Affiliated Business Arrangement Notice


