By David Ghazaryan, NMLS 1486726, iQRATE Mortgages (NMLS 1862492). Updated November 5, 2026.
Short answer: Carson City is its own county-equivalent. Its 2026 one-unit conforming limit is $832,750 (FHFA), the same as Washoe and Douglas counties. A loan above that is a jumbo. FHA tops out at $575,000 here (HUD).
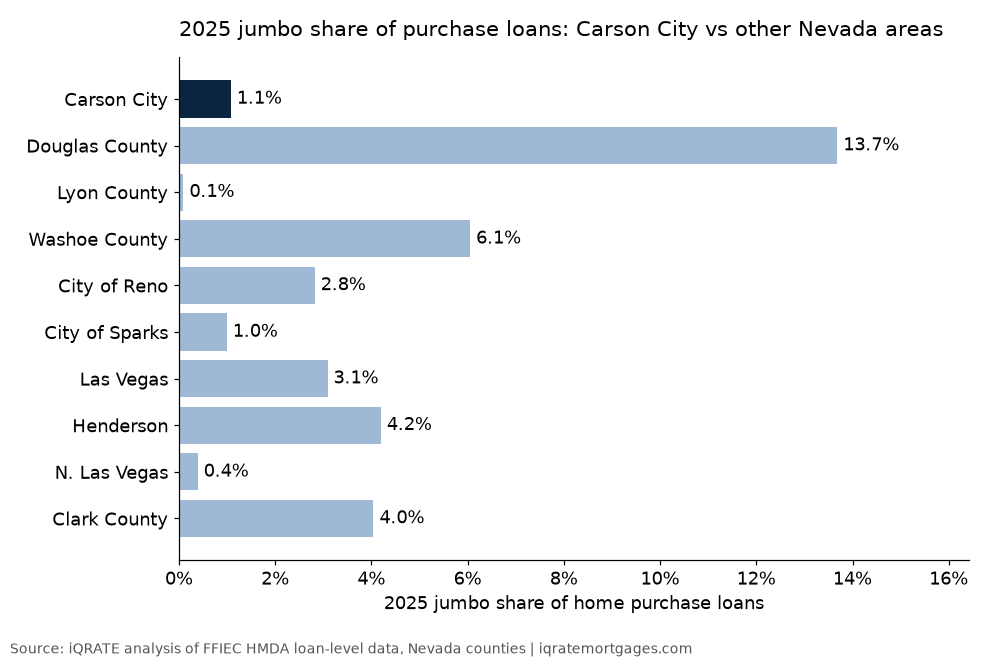
Jumbo loans are rare in Carson City: just 6 of 556 home purchase loans in 2025, about 1 in 93.
Most buyers near the line can stay conforming with a bigger down payment. The tables below show exactly how much.
Want your own numbers checked before you write an offer? Call or text (702) 766-3744 or apply now.
Key facts: Carson City jumbo loans (2026)
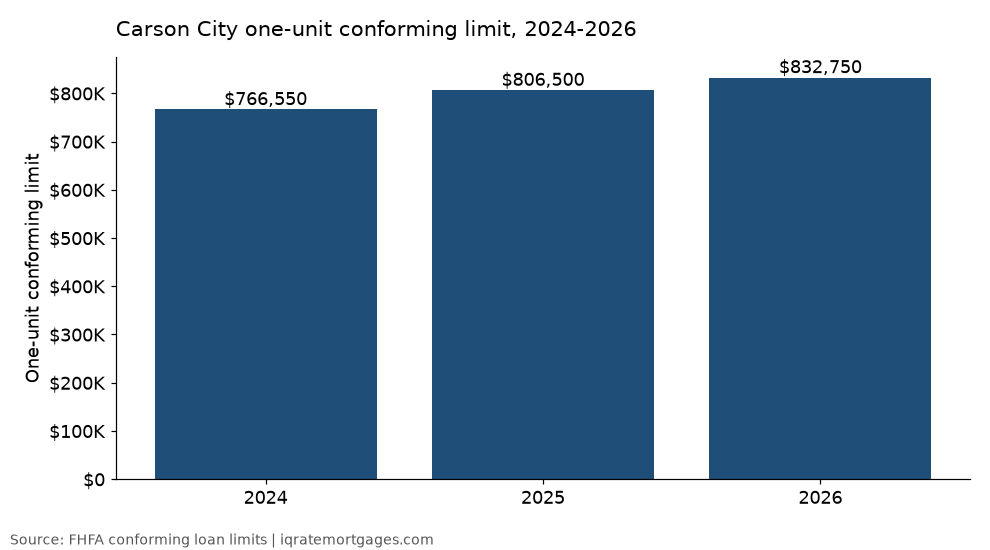
- Jumbo line, 1 unit: a loan above $832,750 (FHFA 2026). It was $806,500 in 2025 and $766,550 in 2024.
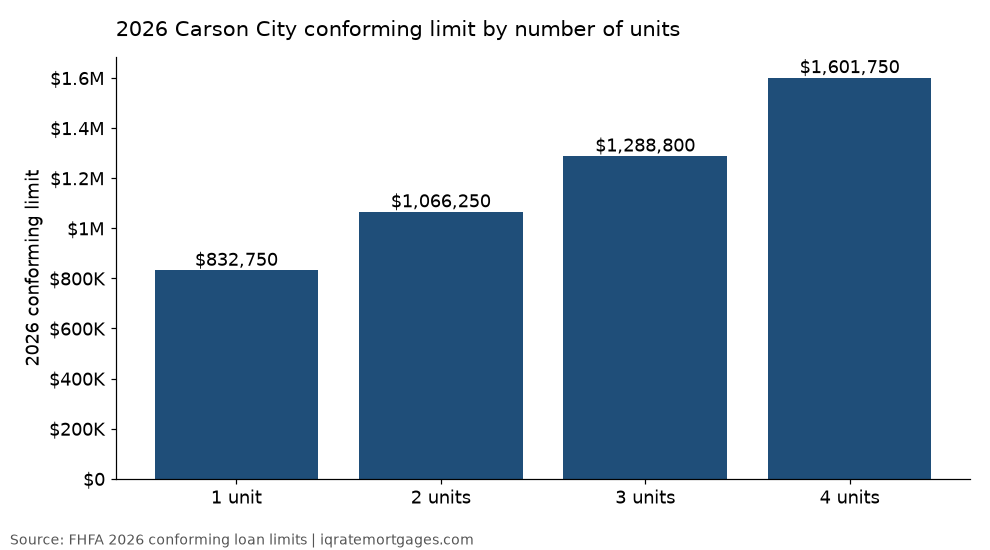
- Limits for 2-4 units: $1,066,250, $1,288,800 and $1,601,750.
- FHA limit, 1 unit: $575,000 (HUD). That is $257,750 below the conforming limit.
- High-balance tier: none. No Nevada county is a high-cost area.
- How common jumbo loans are: 6 of 556 purchase loans in 2025 (1.1%) and 10 of 629 in 2024 (1.6%). Source: iQRATE analysis of public HMDA data.
- Douglas County next door: 91 jumbo purchase loans in 2025, about 15 times as many.
- Typical 2025 Carson City jumbo: a median loan of $895,000 on a $1,020,000 home.
- Where they closed: 89703 (Northwest Carson, foothills) had 9 of the 16 jumbo loans over two years.
- Transfer tax: $1.95 per $500, the lowest in Nevada. That is $3,900 on a $1,000,000 home.
- Who we are: iQRATE Mortgages LLC, NMLS 1862492, a Las Vegas-based Nevada brokerage. We serve Carson City remotely and close through local escrow.
Is Carson City its own county for loan limits?
Yes. Carson City is a consolidated city-county. The Census treats it as a county-equivalent (county FIPS 32510). It is its own metro area, Carson City, NV (CBSA 16180).
It is not part of Washoe County, Reno or Sparks. It is not part of Douglas County either.
That matters for two reasons:
- Conforming limits match. Carson City, Washoe, Douglas, Lyon and Clark all use $832,750 for one unit in 2026.
- FHA limits do not match. Carson City's is $575,000. Douglas County's is $736,000. Washoe and Lyon are at $638,250.
Check the county on your address. ZIP 89705 (south foothills, Clear Creek) is mostly in Douglas County, even with a Carson City mailing address. That doesn't change the jumbo line. The FHA limit can differ ($736,000 in Douglas County vs $575,000 in Carson City), and you should confirm the tax rate with the county assessor.
Ask your title company or the assessor which county the parcel is in.
What are the 2026 loan limits in Carson City?
| Units | Conforming limit (FHFA) | Jumbo if the loan is above | FHA limit (HUD) |
|---|---|---|---|
| 1 unit | $832,750 | $832,750 | $575,000 |
| 2 units | $1,066,250 | $1,066,250 | $736,100 |
| 3 units | $1,288,800 | $1,288,800 | $889,800 |
| 4 units | $1,601,750 | $1,601,750 | $1,105,800 |
Sources: FHFA 2026 conforming loan limits; HUD FHA limits, Carson City, NV MSA 16180.
The one-unit limit rose $26,250 from 2025 (3.3%) and $66,200 from 2024. A lender quoting $806,500 or $766,550 as the 2026 jumbo line is using an old number.
Does the jumbo limit apply to the price or the loan?
To the loan. A $1,000,000 home is not jumbo by itself.
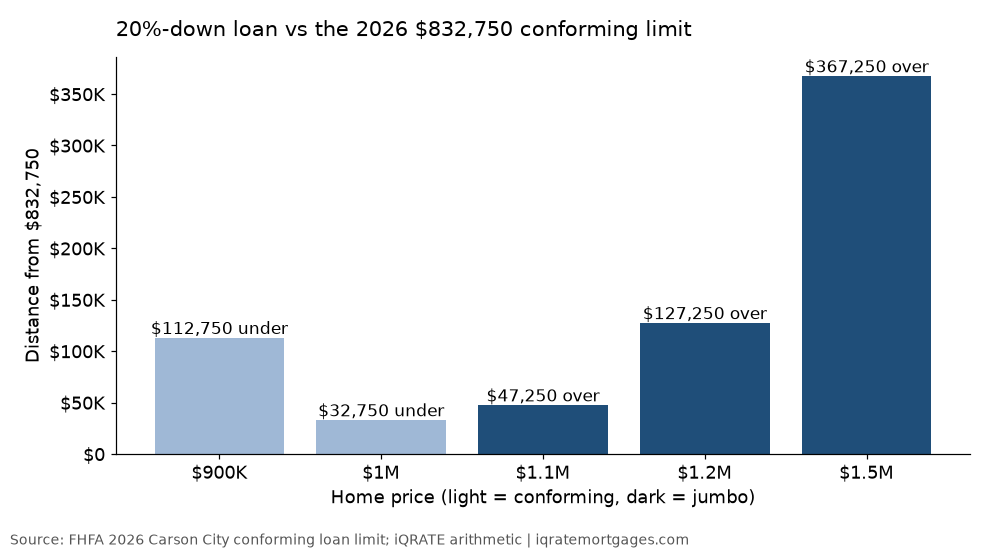
- With 20% down, the loan is $800,000. That is $32,750 under the limit, so it is conforming.
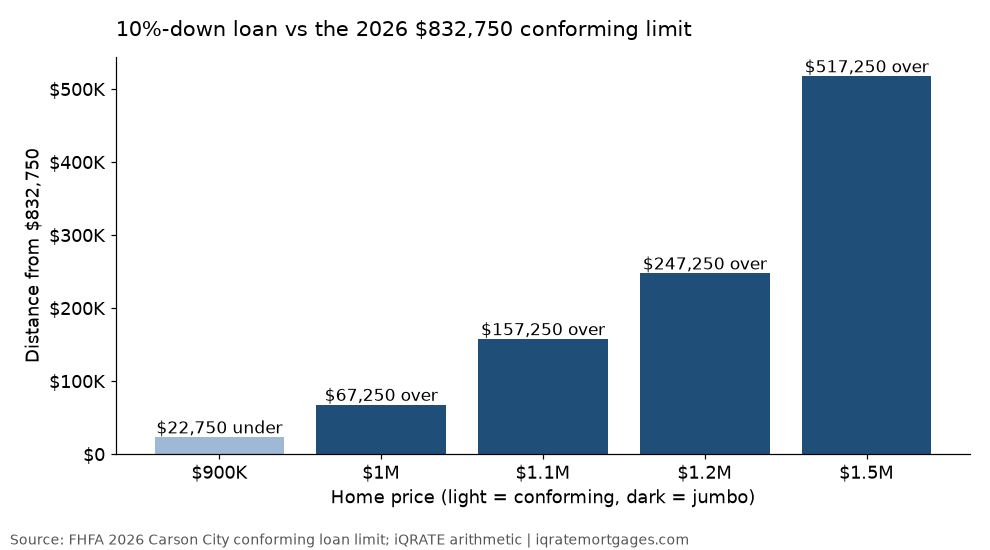
- With 10% down, the loan is $900,000. That is $67,250 over, so it is jumbo.
Conforming or jumbo? Carson City prices near the line (2026, one unit)
| Price | 5% down | 10% down | 20% down | 25% down |
|---|---|---|---|---|
| $850,000 | Loan $807,500: $25,250 under | Loan $765,000: $67,750 under | Loan $680,000: $152,750 under | Loan $637,500: $195,250 under |
| $900,000 | Loan $855,000: $22,250 over (jumbo) | Loan $810,000: $22,750 under | Loan $720,000: $112,750 under | Loan $675,000: $157,750 under |
| $1,000,000 | Loan $950,000: $117,250 over | Loan $900,000: $67,250 over | Loan $800,000: $32,750 under | Loan $750,000: $82,750 under |
| $1,100,000 | Loan $1,045,000: $212,250 over | Loan $990,000: $157,250 over | Loan $880,000: $47,250 over | Loan $825,000: $7,750 under |
| $1,200,000 | Loan $1,140,000: $307,250 over | Loan $1,080,000: $247,250 over | Loan $960,000: $127,250 over | Loan $900,000: $67,250 over |
| $1,500,000 | Loan $1,425,000: $592,250 over | Loan $1,350,000: $517,250 over | Loan $1,200,000: $367,250 over | Loan $1,125,000: $292,250 over |
"Under" means the loan is conforming. "Over" means it is jumbo.
The highest price that stays conforming
| Down payment | Loan-to-value | Highest conforming price |
|---|---|---|
| 3% | 97% | $858,505 |
| 5% | 95% | $876,579 |
| 10% | 90% | $925,278 |
| 15% | 85% | $979,706 |
| 20% | 80% | $1,040,938 |
| 25% | 75% | $1,110,333 |
| 30% | 70% | $1,189,643 |
The math is $832,750 ÷ (1 − down payment). The 3% down option is for eligible buyers only.
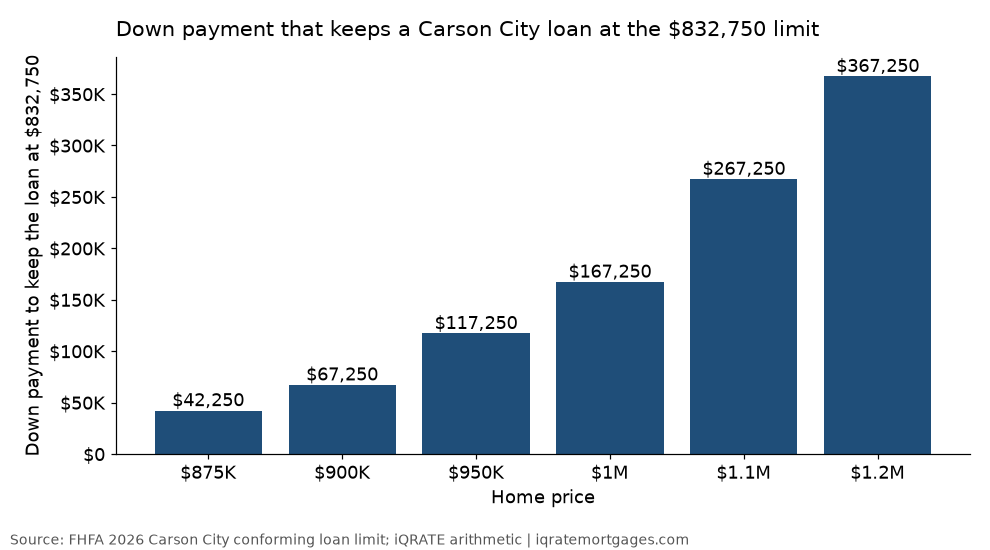
Down payment that keeps your loan at $832,750
| Price | Down payment to stay conforming | Share of price |
|---|---|---|
| $875,000 | $42,250 | 4.8% |
| $900,000 | $67,250 | 7.5% |
| $950,000 | $117,250 | 12.3% |
| $1,000,000 | $167,250 | 16.7% |
| $1,100,000 | $267,250 | 24.3% |
| $1,200,000 | $367,250 | 30.6% |
Staying conforming is not always cheaper. A jumbo, or a conforming first loan with a second lien, can sometimes fit better. It depends on your credit, reserves, how long you keep the loan and that day's pricing.
We lay out the cash to close and the fees for each route side by side. You can also run the "Is my loan FHA, conforming or jumbo?" tool on our Carson City mortgage broker page or see all mortgage calculators.


How many Carson City buyers actually use jumbo loans?
Very few.
How we got these numbers: - Source and years: we downloaded public HMDA loan records for Carson City (county FIPS 32510) from the FFIEC HMDA Data Browser for 2024 and 2025. - Area: Carson City is a consolidated city-county, so the county data is the city data. It covers all 14 populated census tracts. No tract-matching estimate was needed. - What counts as a purchase loan: originated, first-lien, closed-end home purchase loans. - What counts as jumbo: HMDA's flag for loans above that year's limit ($766,550 in 2024, $806,500 in 2025). - Bands: HMDA reports amounts and values in $10,000 bands, and we show the midpoints. - ZIP assignment: we placed each tract in a ZIP using Census TIGERweb.
Two limits on this data: - The counts are small (6 and 10 jumbo loans). Don't over-read a percentage built on so few loans. - HMDA counts loans, not cash buyers. A home bought with cash is not in this data.
Jumbo share of home purchase loans: Carson City and its neighbors
| Area | 2024 purchase loans | 2024 jumbo | 2024 share | 2025 purchase loans | 2025 jumbo | 2025 share |
|---|---|---|---|---|---|---|
| Carson City | 629 | 10 | 1.6% | 556 | 6 | 1.1% |
| Douglas County | 567 | 80 | 14.1% | 665 | 91 | 13.7% |
| Lyon County | 1,093 | 1 | 0.1% | 1,092 | 1 | 0.1% |
Source: iQRATE analysis of public HMDA data. Douglas County includes Minden, Gardnerville, Genoa and the Nevada side of Lake Tahoe, including Stateline and Zephyr Cove. Lyon County includes Dayton, Fernley and Yerington.
Washoe County, for comparison: its 2025 jumbo share was 6.1%. The City of Reno's was 2.8%, and the City of Sparks's was 1.0%. See Reno jumbo loans and Sparks jumbo loans for those markets.
Carson City is a conforming, FHA and VA market. Douglas County had about 13 times the jumbo share in 2025.
Where Carson City jumbo loans closed, by ZIP
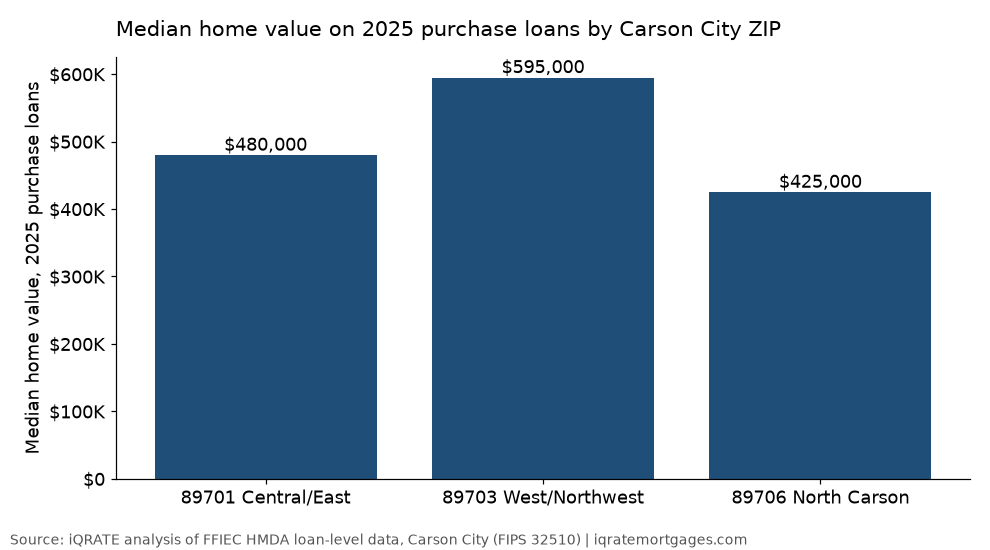
| ZIP | Area | 2024 purchase loans | 2024 jumbo | 2025 purchase loans | 2025 jumbo | 2025 median home value (all purchase loans) |
|---|---|---|---|---|---|---|
| 89701 | Central, West Side, Eagle Valley | 299 | 4 | 276 | 0 | $480,000 |
| 89703 | Northwest Carson, foothills | 184 | 5 | 158 | 4 | $595,000 |
| 89706 | North Carson | 146 | 1 | 122 | 2 | $425,000 |
89703 had 9 of the 16 jumbo purchase loans over the two years. It also had the highest median home value of the three ZIPs. 89701 had no jumbo purchase loans in 2025.
What a Carson City jumbo loan looks like (vs. Douglas County)
| Measure | Carson City 2024 | Carson City 2025 | Douglas 2024 | Douglas 2025 |
|---|---|---|---|---|
| Jumbo purchase loans | 10 | 6 | 80 | 91 |
| Median jumbo loan | $915,000 | $895,000 | $1,150,000 | $1,225,000 |
| Median home value (jumbo loans) | $1,120,000 | $1,020,000 | $1,525,000 | $1,715,000 |
| Median loan-to-value | 80% | 87.4% | 75.7% | 80% |
| Median reported income | $378,000 | $403,500 | $444,000 | $473,000 |
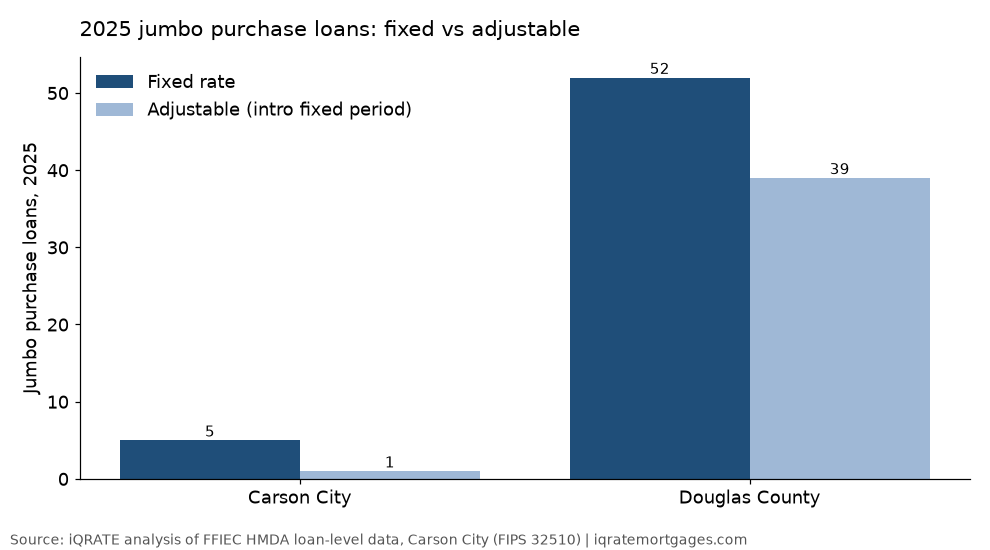
| Adjustable-rate | 1 of 10 | 1 of 6 | 29 of 80 | 39 of 91 |
| Interest-only | 0 | 0 | 12 | 16 |
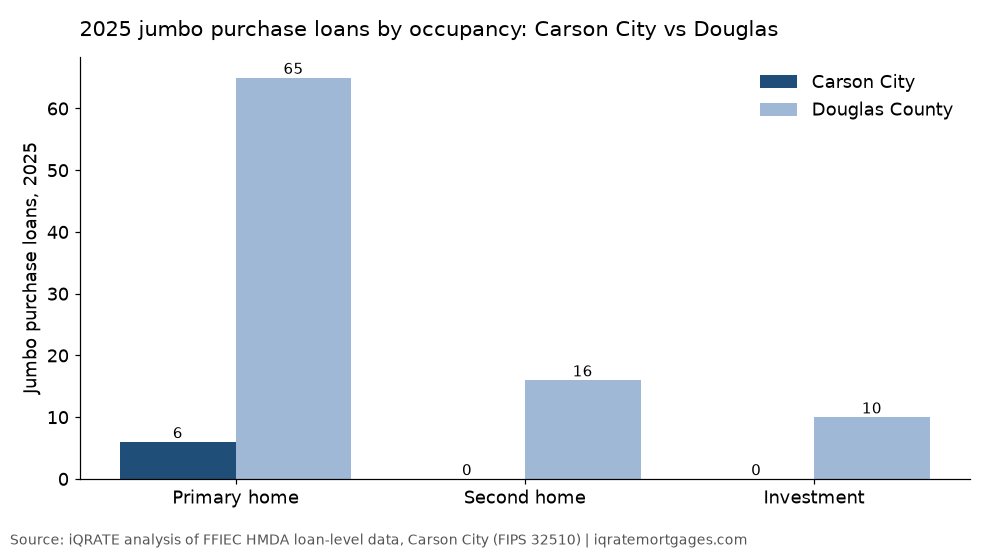
| Primary residence | 10 of 10 | 6 of 6 | 58 of 80 | 65 of 91 |
| Second home | 0 | 0 | 20 | 16 |
| Investment property | 0 | 0 | 2 | 10 |
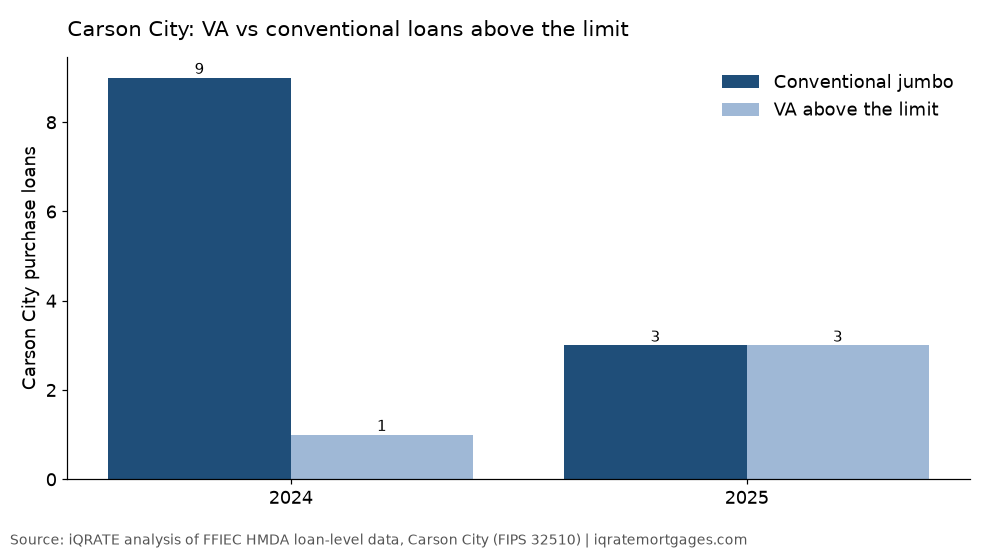
| VA loans above the limit | 1 of 10 | 3 of 6 | 12 of 80 | 7 of 91 |
| Conventional jumbo | 9 of 10 | 3 of 6 | 68 of 80 | 84 of 91 |
| Different lenders | 9 | 5 | 37 | 44 |
What this tells a Carson City buyer: - Every Carson City jumbo purchase loan in both years was a one-unit, 30-year loan on a primary home. - Nearly all were fixed-rate. - None was interest-only, a second home or a rental. - The 2025 median jumbo loan was $895,000. That is only $62,250 above the 2026 limit.
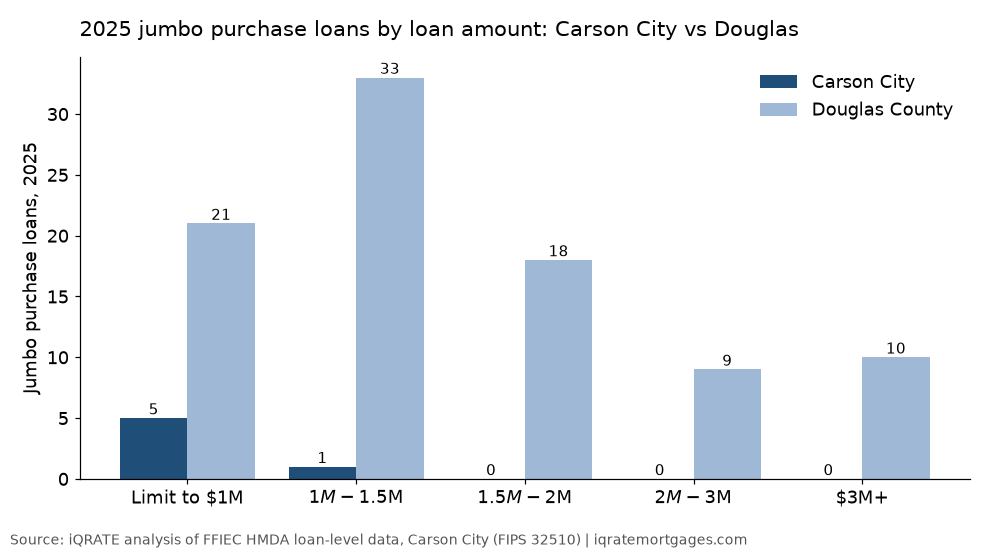
Jumbo loan sizes
| Loan amount | Carson City 2024 | Carson City 2025 | Douglas 2024 | Douglas 2025 |
|---|---|---|---|---|
| Above the limit to under $1,000,000 | 7 | 5 | 25 | 21 |
| $1,000,000 to under $1,500,000 | 3 | 1 | 34 | 33 |
| $1,500,000 to under $2,000,000 | 0 | 0 | 8 | 18 |
| $2,000,000 to under $3,000,000 | 0 | 0 | 7 | 9 |
| $3,000,000 or more | 0 | 0 | 6 | 10 |
The largest Carson City jumbo purchase loan in either year was $1,365,000 (2025). The 2025 loans fell in these bands: $855,000, $855,000, $865,000, $925,000, $925,000 and $1,365,000.
Jumbo loans by loan-to-value
| Loan-to-value | Carson City 2024 | Carson City 2025 | Douglas 2024 | Douglas 2025 |
|---|---|---|---|---|
| 50% or less | 0 | 0 | 8 | 8 |
| Over 50% to 70% | 1 | 0 | 21 | 22 |
| Over 70% to 80% | 5 | 3 | 32 | 50 |
| Over 80% to 90% | 2 | 0 | 11 | 4 |
| Over 90% | 2 | 3 | 5 | 5 |
The three 2025 Carson City loans above 90% LTV were VA loans. Veterans are a big part of this small jumbo market.
How close Carson City buyers get to the line
| Loan amount (all purchase loans) | 2024 | 2025 |
|---|---|---|
| Under $300,000 | 150 | 132 |
| $300,000 to under $400,000 | 157 | 134 |
| $400,000 to under $500,000 | 173 | 153 |
| $500,000 to under $600,000 | 100 | 73 |
| $600,000 to under $700,000 | 27 | 33 |
| $700,000 and up, within the limit | 12 | 25 |
| Above the limit (jumbo) | 10 | 6 |
| Value of the home bought (all purchase loans) | 2024 | 2025 |
|---|---|---|
| Under $400,000 | 135 | 127 |
| $400,000 to under $500,000 | 157 | 154 |
| $500,000 to under $600,000 | 168 | 115 |
| $600,000 to under $800,000 | 131 | 107 |
| $800,000 to under $1,000,000 | 20 | 36 |
| $1,000,000 to under $1,500,000 | 12 | 12 |
| $1,500,000 or more | 0 | 4 |
This is the most useful finding on the page. In 2025, 52 Carson City purchase loans were on homes worth $800,000 or more. Only 6 of those buyers used a jumbo. The other 46 (88.5%) kept the loan at or under the limit.
Conforming loans of $700,000 and up outnumbered jumbo loans about 4 to 1 (25 vs. 6).
The median home on all 2025 purchase loans was $495,000. The median jumbo home was about twice that.
Next step: Shopping between $850,000 and $1,100,000? Send us your price and cash. We will show you the conforming and jumbo routes side by side. Call or text (702) 766-3744.


What do Carson City homes cost in 2026?
Most Carson City homes sell far below the jumbo line.
- The median asking price was $609,000 on October 31, 2026. Homes took a median of 50 days to sell.
- The median sold price was about $499,000 in August 2026.
- Data source: Northern Nevada Regional MLS via Nevada Real Estate Group, as shown on our Carson City mortgage broker page.
| ZIP | Area | Median list price |
|---|---|---|
| 89701 | Central, West Side, Eagle Valley | $430,000 |
| 89703 | Northwest Carson, foothills | $490,000 |
| 89705 | South foothills, Clear Creek (mostly Douglas County) | $820,000 |
| 89706 | North Carson | $450,000 |
Only 89705 sits near the $832,750 line. On a conventional loan, a home at the $820,000 median list price stays conforming at any down payment. Above about $876,579, 5% down is no longer enough (see the table above). 89705 is mostly in Douglas County, so the Carson City HMDA tables above cover only 89701, 89703 and 89706. Inside Carson City, 89703 had 9 of the 16 jumbo purchase loans.
Should I buy in Carson City or Douglas County / Lake Tahoe with a jumbo?
Both use the same $832,750 jumbo line. The markets behave very differently, though.
| Carson City (2025) | Douglas County (2025) | |
|---|---|---|
| Jumbo purchase loans | 6 | 91 |
| Jumbo share of purchase loans | 1.1% | 13.7% |
| Median jumbo loan / home | $895,000 / $1,020,000 | $1,225,000 / $1,715,000 |
| Second homes | 0 | 16 |
| Interest-only | 0 | 16 |
| Adjustable-rate | 1 of 6 | 39 of 91 (42.9%) |
| Loans of $3,000,000+ | 0 | 10 |
| Lenders making these loans | 5 | 44 |
| FHA limit, 1 unit | $575,000 | $736,000 |
What that means in practice: - If you want a Lake Tahoe second home or a $3 million-plus estate, the HMDA record points to Douglas County, not Carson City. - If you want a primary home just over the line in the Carson foothills, a fixed-rate 30-year loan is what local buyers chose. - Second homes usually need more down than primary homes (varies by lender). - Looking at the Washoe County side of Lake Tahoe? Incline Village homes often need jumbo loans. See Reno jumbo loans for Washoe data.
What is an interest-only jumbo? Some lenders allow interest-only payments for an initial period, often 10 years. After that, payments rise to cover principal over the remaining term. Interest-only can help buyers with uneven income or large liquid assets manage cash flow. But you don't build equity through payments during that period. Lenders usually ask for more down and more reserves. We'll show you the payment before and after the interest-only period side by side before you choose.
Buying in Clark County instead? See Las Vegas, Henderson and North Las Vegas jumbo loans, or our full jumbo loan guide.


Carson City jumbo requirements at a glance
| Requirement | Typical range across lenders we compare | Carson City data point |
|---|---|---|
| Jumbo line, 1 unit | Loan above $832,750 (FHFA 2026) | Median 2025 jumbo loan was $62,250 above it |
| Down payment | Often 10-20%; more above $2-3 million | Median LTV 80% (2024), 87.4% (2025, pulled up by VA) |
| Credit score | Many lenders start around 700 | Not reported in HMDA |
| Debt-to-income | Commonly up to about 43%; some higher with strong reserves | 5 of 16 jumbo loans were in the 43% to under 50% band |
| Reserves after closing | Commonly 6-12 months of payments; more on larger loans | Not reported in HMDA |
| Appraisal | Full appraisal; a second appraisal is common on larger loans | 1 of 5 jumbo denials was collateral |
| Income documents | Tax returns and W-2s, or bank statements, or asset depletion | — |
| Occupancy | Primary, second home or investment (rules differ) | All 16 were primary homes |
| Loan type | Fixed, ARM (5, 7 or 10-year), interest-only | 14 of 16 fixed; 0 interest-only |
Every lender sets its own rules. These are typical ranges, not a commitment to lend.
Carson City jumbo loans by debt-to-income (2024-2025, 16 loans)
| DTI reported | Loans |
|---|---|
| Under 20% | 2 |
| 20% to under 30% | 3 |
| 30% to under 36% | 4 |
| 36% to under 43% | 1 |
| 43% to under 50% | 5 |
| 50% to 60% | 1 |
A higher ratio can close with the right lender and enough reserves. That is one reason shopping matters.

Can I use a VA loan above $832,750 in Carson City?
Often, yes. In 2025, 3 of Carson City's 6 jumbo purchase loans were VA loans. In 2024 it was 1 of 10.
How VA works above the limit: - Veterans with full VA entitlement have no VA loan limit. - There is no monthly mortgage insurance. - Individual lenders may still cap the loan amount. Compare VA lenders, not just VA vs. conventional. - VA funding fee: 2.15% of the loan on first use with no down payment, and 3.3% on later use. With 5% down on first use, it drops to 1.5%. - Veterans with a service-connected disability rating pay no funding fee.
At jumbo loan sizes, that fee is a large dollar figure. A small down payment can lower it. Ask us to compare both.
Video: Don't Make This $9,000 VA Funding Fee Mistake. David Ghazaryan explains how the funding fee works, who is exempt and how a small down payment can lower it.
See VA loans and the VA loan limits page.
My loan is over $575,000 but under $832,750. Is that a jumbo?
No. That loan is conforming. It is over the Carson City FHA limit, though. This gap is $257,750 wide, and many local buyers land in it.
With 3.5% down, FHA covers a price up to about $595,854. Above that, you have three options:
- Put more down on FHA, so the FHA loan stays at or under $575,000.
- Use a conventional loan with 3% to 5% down. With 3% down, a conforming loan covers a price up to about $858,505 (eligible buyers).
- Check the county. If the address is in Douglas County, the FHA limit is $736,000. That is $161,000 higher.
Down payment help near the line: Nevada Rural Housing's Rural Rocks $20K serves Carson City. Its price limit is $832,750, the same as the conforming limit. You may not own another home at closing, and income limits and residency rules apply. Funding is limited and can close without notice.
Video: Stop Paying FHA Mortgage Insurance For 30 Years. David Ghazaryan compares FHA and conventional loans and covers ways to remove mortgage insurance.
See FHA loans and the Carson City mortgage broker page for down payment help.

What about a duplex, triplex or fourplex in Carson City?
The jumbo line rises with the number of units: - 2 units: $1,066,250, which is $233,500 above the one-unit limit. - 3 units: $1,288,800. - 4 units: $1,601,750.
None of Carson City's jumbo purchase loans in 2024 or 2025 was on a 2-4 unit property. Every one was one unit.
A two-unit loan up to $1,066,250 is still conforming. If you live in one unit, owner-occupied rules apply. If you don't, investor rules apply.
I'm moving from California. What changes?
The limit changes. In 2026, Los Angeles, Orange, San Francisco, Santa Clara and Alameda counties allow conforming loans up to $1,249,125. San Diego allows $1,104,000, and Ventura allows $1,035,000.
In Carson City, jumbo starts at $832,750. A loan that was conforming in a coastal county can be a jumbo here. Sacramento, Riverside and San Bernardino use the same $832,750 as Nevada.
Three ways to buy before you sell: - a bridge loan, - a HELOC on the California home, - qualifying with both payments.
Which fits depends on your equity, income and reserves (varies by lender). Nevada has no state personal income tax. Ask your tax pro how the move affects you.
David's answer about Californians relocating to Las Vegas applies here too: "We evaluate proceeds from their previous home, reserves, employment continuation, and how best to structure the financing for the Nevada purchase."
iQRATE is licensed in Nevada and California, so one team can work both sides. See our California mortgage broker and Sacramento mortgage broker pages.
Retired, self-employed or paid in bonuses and stock?
Many Carson City buyers are state workers, retirees or commuters to Reno, Minden or the Tahoe Reno Industrial Center. Lenders handle state pensions, retirement income and public pay well. Non-taxable pension income can often be grossed up for qualifying.
Jumbo programs we compare: * Full-documentation jumbo: tax returns and W-2s. The most common route. * 12- or 24-month bank-statement jumbo: income comes from deposits. Business accounts get an expense factor, and a CPA letter or P&L is common. See bank-statement loans. * Asset-depletion or asset-utilization jumbo: eligible savings, brokerage and vested retirement balances become qualifying income. See asset depletion loans in Nevada. * 1099 and P&L-only options (varies by lender). * Bonus, commission and RSU income: lenders want a history showing it is likely to continue. See how Nevada lenders calculate bonus income.
These programs often carry larger down payments, larger reserves and their own credit minimums.
From David, in his own words (excerpts from his answers; some sentences omitted):
I don't treat jumbo financing as one product with one credit-score requirement. There are published wholesale jumbo programs extending to $5 million, and separate bank-statement and asset-utilization products for borrowers who don't fit full-documentation underwriting. The right structure depends on more than loan amount. Occupancy, credit score, leverage, assets, documentation type, and how long the buyer intends to keep the property all matter.
Some people have millions of dollars invested but relatively little conventional employment income. Asset-depletion and asset-utilization programs can sometimes solve that mismatch.
One of the most unusual clients I've worked with was a YouTube gamer buying a home in Henderson for approximately $3 million. I've also worked with a music producer and an Instagram influencer. A bank's standard tax-return calculation may not always provide the best available qualification method. That doesn't mean we can count every dollar that enters the account. It means we need to understand which receipts represent eligible income and identify a lender whose documentation requirements fit the borrower. I started in the mortgage industry in 2005 and have also worked in tax preparation since 2008.
That Henderson purchase was in Southern Nevada, not Carson City.
How do I compare jumbo lenders and brokers in Carson City?
A lender directory gives you names and addresses. It can't tell you who will approve your file.
In 2025, 5 different lenders made Carson City's 6 jumbo purchase loans. In 2024, 9 lenders made 10. In Douglas County, 44 lenders made 91.
No lender dominates this market. Each one writes its own jumbo rules. One may say no while another says yes.
Some lender pages state the $832,750 limit but say they don't offer jumbo loans right now. Ask before you apply.
| What to check | Why it matters here | Question to ask |
|---|---|---|
| Nevada license | Only Nevada-licensed firms and loan officers can originate | What are your company and personal NMLS numbers? |
| Do they offer jumbo now? | Some local lenders don't | Can you close a jumbo loan this month? |
| Number of jumbo lenders | Rules differ by lender | How many jumbo lenders will see my file? |
| Program range | Retirees and business owners often need a different income method | Full-doc, bank-statement, asset-depletion, VA above the limit? |
| Correct 2026 limit | Some pages still quote $806,500 or $766,550 | What is the 2026 Carson City one-unit limit? |
| Conforming check | 46 of 52 buyers of $800,000+ homes stayed conforming in 2025 | How much down keeps me under $832,750, and is that better for me? |
| Reserves in dollars | Reserves are a common reason jumbo files get restructured | How many months, which accounts count, and at what discount? |
| Appraisal plan | Older, acreage and rural-edge homes can have few close comparable sales | Will this loan need a second appraisal? |
| County check | 89705 is mostly Douglas County | Which county is this parcel in? |
| Written comparison | Verbal quotes are not binding | Will I get official Loan Estimates within 3 business days of applying? |
| Compensation | Broker pay must be disclosed | How are you paid on this loan? |
The CFPB recommends comparing official Loan Estimates. We suggest going line by line. See the CFPB Loan Estimate explainer. Check any loan officer on NMLS Consumer Access.
Red flags: * A 2026 quote that uses $806,500 or $766,550 as the jumbo line. * A rate quoted before anyone reviews your credit, income, assets and the property. * No mention of reserves or appraisal risk. * Pressure to sign an intent to proceed before you compare Loan Estimates. * "Only one program works for you" from a lender with only one program.
How iQRATE handles these points: * License: Company NMLS 1862492; David Ghazaryan NMLS 1486726, both searchable on NMLS Consumer Access. * Lenders: we shop the file across our wholesale lender network and show the options in writing. * Programs: full-doc, bank-statement, asset-depletion and interest-only jumbo, plus 5-, 7- and 10-year ARMs; terms vary by lender. * Reserves: we calculate reserves in dollars before you write an offer. * Appraisal: we flag second-appraisal thresholds and timeline up front. * Loan Estimates: official Loan Estimates within 3 business days of application. * Pay: compensation is disclosed on the Loan Estimate and Closing Disclosure.
iQRATE Mortgages (NMLS 1862492) is a broker, not a lender. We shop your file across our wholesale lender network, and we put the options in writing. A bank can only offer its own jumbo product.

How do appraisals work on older, acreage and custom Carson City homes?
Many Carson City homes are older, and some rural-edge homes sit on acreage with wells and septic. Unusual homes can be hard to compare with recent sales. Almost half of Carson City homes (48.6%) were built before 1980. Statewide, the share is 22.0%.
What that means for a jumbo appraisal: * Older homes: West Side homes from the 1800s and early 1900s can raise appraisal and insurance questions, such as wiring and foundations. An appraiser may flag old wiring, a worn roof or a failing foundation. * Rural-edge homes: some have wells or septic systems. Lenders may ask about them. * Few comparable sales: if the value comes in below the price, you can bring more down, renegotiate, or try a different lender. * Larger loans: some lenders want a second appraisal or a review appraisal. * Your rights: you get a copy of the appraisal promptly on completion, or 3 business days before closing, whichever is earlier (12 CFR 1002.14).
A low appraisal raises your loan-to-value at the same loan amount. If that goes above the lender's maximum, you may need a larger down payment, a price renegotiation or a different lender. Ask about the roof, heating and electrical before the appraisal is ordered.
More: Systematizing appraisal success in Reno and Carson City.
What does it cost to close near the jumbo line in Carson City?
Transfer tax at jumbo prices
Carson City charges $1.95 per $500 of value (about 0.39%), rounded up. It is the lowest of Nevada's three rates.
| Price | Carson City ($1.95) | Washoe ($2.05) | Clark ($2.55) |
|---|---|---|---|
| $832,750 | $3,249 | $3,415 | $4,248 |
| $900,000 | $3,510 | $3,690 | $4,590 |
| $1,000,000 | $3,900 | $4,100 | $5,100 |
| $1,200,000 | $4,680 | $4,920 | $6,120 |
| $1,500,000 | $5,850 | $6,150 | $7,650 |
The contract decides who pays.
Property tax
Carson City's combined rate is about $3.57 per $100 of assessed value. Assessed value is 35% of taxable value. That is about $1,249.50 a year per $100,000 of taxable value, before the cap.
In Nevada, taxable value is often well below the sale price. Ask for the last tax bill on the home. After closing, file the Assessor's claim so your primary home gets the 3% yearly cap (NRS 361.4723).
Other closing costs and cash to close
For iQRATE clients, Nevada closing costs typically run about $6,000 to $8,000 on full-documentation loans. Some non-QM loans run about $15,000. All of it is itemized on your Loan Estimate.
Cash to close also includes your down payment and prepaids. See closing costs by state.
Reserves, in dollars
Jumbo lenders count reserves in months of your full housing payment (principal, interest, taxes, insurance and HOA dues). On a $10,000 monthly payment:
| Months | Reserves needed |
|---|---|
| 6 | $60,000 |
| 12 | $120,000 |
| 18 | $180,000 |
| 24 | $240,000 |
What usually counts: - checking, savings and brokerage accounts, - vested retirement accounts, often at a discount.
What usually doesn't count: gift funds and borrowed money.
Lenders like to see about two months of statements. Large deposits need a paper trail.

Why do Carson City jumbo applications get denied?
The counts are too small for a real rate. Over 2024 and 2025, 25 jumbo applications got a decision, and 5 were denied.
| Year | Decided jumbo applications | Denied | Decided conforming applications | Denied | Conforming denial rate |
|---|---|---|---|---|---|
| 2024 | 13 | 2 | 945 | 128 | 13.5% |
| 2025 | 12 | 3 | 974 | 143 | 14.7% |
Main reasons for the 5 jumbo denials: - Other: 2 - Credit application incomplete: 2 - Collateral (appraisal or property): 1
Two of the three 2025 denials were incomplete applications. That is a process problem, not a credit problem. Collect every document before you write an offer.
From David:
I don't begin by assuming the first lender made a mistake. I begin by finding out exactly why that lender couldn't approve the transaction. Was it income calculation? Insufficient reserves? Restricted stock? A debt-to-income limit? A property that didn't satisfy the lender's appraisal requirements? Those are very different problems. The next step is to identify whether the issue is something that can be corrected through documentation or whether the borrower genuinely needs a different loan program.
Video: Bank Denied Your Loan? Do This Instead. David Ghazaryan explains what to do after a bank says no, and why a broker can shop other lenders.
Next step: Turned down? Get a free second look at the file. Call or text (702) 766-3744.

Can I refinance a Carson City jumbo loan?
Yes, but it is a small market. In 2025, 3 of 240 Carson City refinances were jumbo (1 was cash-out). In 2024, it was 1 of 139.
Four points to know: 1. The line is based on the new loan. If your balance is now at or under $832,750, the new loan can be conforming. Three of the 10 jumbo purchase loans from 2024 had band midpoints at or under today's limit. (This is approximate, because HMDA bands are $10,000 wide.) 2. Cash-out costs more equity. Lenders usually allow a lower loan-to-value on cash-out than on rate-and-term refinances. 3. Your tax cap stays. A refinance without an ownership change does not affect your 3% property tax cap. 4. ARMs need a plan. If you have an ARM, compare a new ARM, a fixed jumbo, and a conforming loan with a paydown before the first adjustment.
See refinance options.
Carson City jumbo document checklist by borrower type
| Document | W-2 or state employee | Self-employed, full doc | Bank-statement jumbo | Retiree / asset depletion | California mover | VA buyer |
|---|---|---|---|---|---|---|
| Government ID | Yes | Yes | Yes | Yes | Yes | Yes |
| Pay stubs and 2 years of W-2s | Yes | If any W-2 income | No | No | If employed | If employed |
| Personal tax returns | Often 2 years | Usually 2 years | Usually not | Usually not | If full doc | If full doc |
| Business tax returns | No | Usually 2 years | No | No | If self-employed | If self-employed |
| 12 or 24 months of bank statements | No | No | Yes | For qualifying assets | If using bank-statement income | No |
| Brokerage and retirement statements | For reserves | For reserves | For reserves | Yes, to figure income | Yes | For reserves |
| Pension or Social Security award letters | If any | If any | If any | Yes | If any | If any |
| Bonus or RSU history | If used | — | — | — | If used | If used |
| CPA letter or business license | No | Sometimes | Often | No | If self-employed | If self-employed |
| Departing-home mortgage statement or sale contract | If you own | If you own | If you own | If you own | Yes | If you own |
| VA Certificate of Eligibility | — | — | — | — | — | Yes |
| Gift letter and donor statements | If gifted | If gifted | If gifted | If gifted | If gifted | If gifted |
Requirements vary by lender and program.
How does a Carson City jumbo loan work, step by step?
- Call first. Tell us the price, the address or ZIP, and how you earn income. We check whether more down keeps you conforming.
- Confirm the county. That matters most for 89705 addresses, which are mostly Douglas County.
- Send documents. Use the checklist above. A complete file avoids one of the two most common jumbo denial reasons here.
- Compare lenders. We price full-doc, bank-statement, asset-depletion and VA options, and conforming where it fits.
- Get pre-approved in writing. Your agent sends the letter with your offer.
- Get your Loan Estimate. It comes within 3 business days of application (12 CFR 1026.19). Compare them line by line.
- Order the appraisal. This happens once you are in contract. We flag older-home and comparable-sales risk early.
- Clear underwriting conditions. Reserves, large deposits and business income are the usual items.
- Review the Closing Disclosure. You get it at least 3 business days before signing.
- Sign with local escrow and fund. Then file the Assessor's claim for your 3% tax cap.
Has iQRATE closed jumbo loans like mine?
Here is the honest answer. We have not published a closed jumbo file in Carson City or Northern Nevada. Our published closed jumbo files are in Southern Nevada and California.
Those files include: - a Las Vegas content creator's move-up to a home near $2.7 million, with a jumbo near $2 million, - a self-employed promoter's 15-year jumbo, - a refinance that still funded after a $350,000-low appraisal.
Read them on our jumbo loan guide. Results depend on each file.
What do clients say about iQRATE Mortgages?
These are real 5-star reviews, quoted word for word. They describe our team overall. None is confirmed to be a jumbo loan or a Carson City loan.
"David was very professional and went above and beyond to make sure I understand the loan procedure. In addition, he went with me to my closing because I expressed that I would be more comfortable with him there to explain the documents to me. He was there and ensured a smooth transaction. Everything completed as expected. I would definitely recommend him to my friends and family."
— Jasmin (Las Vegas, NV), 5-star review on Zillow.
"David's experience in the greater Las Vegas area has been a tremendous help in every aspect of buying my home. His work is quick, efficient, and reliable."
— eddieyervinyan (Las Vegas, NV), 5-star review on Zillow.
"Well I've known David for many years. His office prepares my taxes. I had been putting off buying a home since I am a 1099 sales person. I thought mortgages were for wage earners. Never really thought I would qualify. They I mentioned to him in a conversation that I couldn't get a home, because of the type of income I have and all these reasons. In less than 10 minutes he had me qualified. Had to pay a couple of credit cards off, that was it, I own a home now. The only regret I have is not asking him sooner. This guy knows his numbers, taxes, rules and whatever else goes into that paperwork nightmare. Needless to say, I highly recommend him."
— garik 82 (Las Vegas, NV), 5-star review on Zillow.
"Very efficient and transparent service. They go above and beyond to deliver the loan closure on time even in a very tight time line. Also very resourceful and knowledgeable staff. I'll go to them again next time I need a loan."
— Rita S. (Los Angeles, CA), 5-star review on Yelp.
"I highly reccomend David. He treated my loan process in the same manner as he would of had if it's his own. David walked me through the process from the beginning to the end. He was always available when i called, even on weekends and holidays, especially when he had a family tragedy he still made my loan a priority and finished it on time as promised."
— Yelena M. (Henderson, NV), 5-star review on Zillow.
Our ratings: - Google 5.0 from 77 reviews. - Yelp 5.0 from 51 reviews. - Zillow 5.00 from 9 reviews. - 5.0 stars from 87 reviews on Experience.com (October 2026).
Read our Google reviews · Yelp · Zillow · Experience.com · All reviews
Frequently asked questions
What is the jumbo loan limit in Carson City for 2026?
A loan above $832,750 on a one-unit home is jumbo (FHFA). The jumbo lines for 2-4 units are $1,066,250, $1,288,800 and $1,601,750.
Is Carson City part of Washoe or Douglas County?
No. Carson City is an independent consolidated city-county, a county-equivalent with its own metro area. Its conforming limit matches Washoe and Douglas. Its FHA limit, $575,000, does not.
Does the limit apply to the home price or the loan?
To the loan amount. On a $1,000,000 home, 20% down gives an $800,000 conforming loan. 10% down gives a $900,000 jumbo.
How much do I need to put down to avoid a jumbo in Carson City?
Price minus $832,750. That is $67,250 on a $900,000 home, $167,250 on $1,000,000, and $267,250 on $1,100,000.
What home price turns into a jumbo with 20% down?
About $1,040,938. With 10% down it is about $925,278. With 25% down it is about $1,110,333.
How common are jumbo loans in Carson City?
Rare. In 2025, 6 of 556 purchase loans were jumbo, about 1 in 93. In 2024, it was 10 of 629. HMDA counts loans, not cash purchases.
Where in Carson City are jumbo loans most common?
In 89703, Northwest Carson and the foothills. It had 9 of the 16 jumbo purchase loans in 2024-2025. 89701 had none in 2025.
How does Carson City compare with Douglas County for jumbo loans?
Douglas County had 91 jumbo purchase loans in 2025, about 15 times Carson City's 6. Its median jumbo loan was $1,225,000, vs. $895,000 in Carson City. Douglas also had 16 second homes and 16 interest-only loans. Carson City had none.
What credit score do I need for a Carson City jumbo loan?
Many jumbo lenders start around 700. Some want more for larger loans or smaller down payments (varies by lender).
How much down payment does a jumbo loan need?
Often 10-20%, and more above $2-3 million. The median Carson City jumbo loan-to-value was 80% in 2024. It was 87.4% in 2025, because VA loans pulled it up.
How many months of reserves do jumbo lenders want?
Commonly 6-12 months of the full housing payment, and more on larger loans or with several properties. On a $10,000 payment, 12 months is $120,000.
What debt-to-income ratio is allowed?
Commonly up to about 43%, and higher at some lenders with strong reserves. Among 16 Carson City jumbo loans, 5 were in the 43% to under 50% band.
Do jumbo loans have PMI?
Most jumbo loans don't use standard private mortgage insurance. Lenders usually want a larger down payment instead. VA loans have no monthly mortgage insurance.
Can I use a VA loan above $832,750 in Carson City?
Often, yes. Veterans with full entitlement have no VA loan limit, but lenders may set their own caps. In 2025, 3 of Carson City's 6 jumbo purchase loans were VA.
My loan is between $575,000 and $832,750. Is it a jumbo?
No. It is conforming, but over the Carson City FHA limit. Use conventional, put more down on FHA, or check whether the address is in Douglas County, where FHA allows $736,000.
Is there a high-balance conforming loan in Carson City?
No. No Nevada county is an FHFA high-cost area in 2026. Any one-unit loan above $832,750 is jumbo.
Can I get a jumbo loan without tax returns?
Yes, through non-QM programs. Options include 12- or 24-month bank-statement loans and asset-depletion loans. They carry their own credit, down payment and reserve rules.
Should I choose a jumbo ARM or a 30-year fixed?
An ARM can fit if you expect to sell or refinance within the fixed period. A fixed loan keeps the payment steady. In Carson City, 14 of 16 jumbo purchase loans were fixed.
Will a Carson City jumbo need two appraisals?
Sometimes, on larger loans (varies by lender). Older homes, acreage and unique homes may have few close comparable sales. Plan for appraisal time early.
How much is the transfer tax on a $1,000,000 Carson City home?
$3,900, at $1.95 per $500. It would be $4,100 in Washoe County and $5,100 in Clark County.
Why are Carson City jumbo applications denied?
The counts are small: 5 denied out of 25 decided over two years. Two were incomplete applications, one was collateral and two were "other." The 2025 conforming denial rate was 14.7%.
How do I compare Carson City jumbo lenders?
Get official Loan Estimates from more than one source and compare them line by line, as the CFPB recommends. Ask for reserves in dollars, the second-appraisal rule and the 2026 limit. Verify every license on NMLS Consumer Access.
Related iQRATE pages
- Jumbo loans: full Nevada guide
- Carson City mortgage broker: FHA, VA, down payment help, taxes
- Reno jumbo loans · Sparks jumbo loans
- Las Vegas jumbo loans · Henderson jumbo loans · North Las Vegas jumbo loans
- VA loans · FHA loans · Refinance
- Bank statement loans · Asset depletion loans in Nevada · Non-QM loans · Self-employed loans
- Jumbo vs. high-balance loans in Nevada
- Piggyback vs. jumbo loan in Reno: a cost guide
- Use your portfolio for a Nevada jumbo loan in 2026
- Get a Reno and Incline Village loan with California income
- Mortgage calculators · Closing costs by state
Where can I read more about Carson City, Northern Nevada and Nevada jumbo loans?
These are our own guides. Each link opens a page on this site.
Which Nevada city pages should I compare?
- Carson City mortgage broker (Carson City FHA limit, taxes, ZIP market data, local loan data).
- Sparks jumbo loans (City of Sparks and Spanish Springs loan data).
- Reno jumbo loans (City of Reno and Reno ZIP loan data).
- Sparks mortgage broker (Sparks loan limits, taxes, ZIP market data).
- Reno mortgage broker (Washoe loan limits, taxes, market data).
- Las Vegas jumbo loans (city loan data).
- Henderson jumbo loans (city loan data).
- North Las Vegas jumbo loans (city loan data).
- Nevada mortgage broker.
- Las Vegas mortgage broker.
- Henderson mortgage broker.
- Summerlin mortgage broker.
Which iQRATE loan program pages fit a buyer near the jumbo line?
- Jumbo loans in Nevada.
- Bank statement loans.
- Non-QM loans.
- Asset depletion loans in Nevada.
- DSCR loans.
- Investor loans.
- VA loans.
- Mortgage calculators.
- Client reviews.
- Apply now.
- Contact us.
- Rates and how we quote.
- Our written guarantees.
Which Carson City and Northern Nevada guides should I read?
- A guide to Las Vegas & Reno rental portfolio blanket loans.
- Best loan to buy a Reno BRRRR property in Nevada.
- Bypass mortgage seasoning rules in Las Vegas & Reno.
- Co signed loan blocking your Reno mortgage heres the fix.
- Combining gig income for a Reno & Sparks mortgage.
- Consolidate Reno rentals with a DSCR portfolio loan.
- DSCR loan approval for older Reno & Sparks rental homes.
- DSCR loan calculation for Las Vegas & Reno investors.
- DSCR loans for vacant rentals in Reno & Las Vegas.
- FHA appraisal repairs in Reno what to do next.
- FHA loan for a Reno home with unpermitted additions.
- FHA repair checklist for Reno & Carson City Nevada homes.
- FHA repairs for older homes in Reno Nevada.
- FHA vs conventional loan in Reno build equity faster.
- Financing a Reno mobile home park with a DSCR loan.
- Financing your 11th rental in Reno and Sparks Nevada.
- First Reno investment property a strategic mortgage guide.
- Get a mortgage in Henderson & Reno with a thin credit file.
- Get a Reno & Incline Village loan with California income.
- How lenders average 1099 income in Las Vegas & Reno.
- How lenders combine 1099 incomes in Las Vegas & Reno.
- How Reno underwriters view your medical debt for a mortgage.
- How student loans affect a mortgage in Reno Nevada.
- Is FHA mortgage insurance in Reno Nevada a waste of money.
- Loan options after 10 properties in Las Vegas & Reno Nevada.
- Low credit score how to buy a home in Reno & Las Vegas.
- My Reno home failed the FHA appraisal what now.
- Navigating jumbo loan appraisal gaps in Reno Nevada.
- Nevada DSCR loans for Reno & Las Vegas gig workers.
- Nevada foreign investor portfolio loan Reno & Las Vegas.
- Piggyback vs jumbo loan in Reno Nevada a cost guide.
- Portfolio loan risks in Reno and Carson City Nevada.
- Prep your Las Vegas & Reno business for a mortgage.
- Reno & Sparks DSCR loan guide for fixer uppers.
- Reno & Sparks FHA mip vs conventional pmi explained.
- Reno down payment assistance a good deal or a costly trap.
- Reno mortgage guide with less than 2 years self employed.
- S corp salary too low for a mortgage in Reno Nevada.
- Simplify Reno & Las Vegas rentals with one portfolio loan.
- Systematizing appraisal success in Reno and Carson City.
- Unpermitted adu rent for a Reno DSCR loan does it count.
- Use Reno rental equity to buy another Nevada property.
- Using gift funds for closing costs in Reno Nevada.
- Using home equity to buy a second home in Reno Nevada.
- Using part time income for a VA loan in Reno Nevada.
- Vet buyer financing in Reno and Carson City like a pro.
- What is payment shock and how to beat it in Reno Nevada.
- What is the true cash needed to close in Reno Nevada.
- Why is my Reno cash to close higher than estimated.
Which Nevada jumbo, self-employed and high-income guides help?
- A guide to California jumbo Renovation loans.
- A Nevada S-Corp guide to mortgage qualification.
- Bank statements vs tax returns for a Las Vegas mortgage.
- California investors buying Las Vegas rentals with a DSCR loan.
- California to Las Vegas jumbo loan before selling your home.
- Foreign national jumbo loans in Nevada a guide.
- Henderson jumbo loans macdonald highlands ascaya lake Las Vegas.
- How Nevada lenders calculate overtime & bonus income.
- Jumbo loans for a home in a trust in Las Vegas Nevada.
- Jumbo vs high balance loans in Nevada which is best.
- Jumbo vs piggyback loan in Las Vegas & Henderson Nevada.
- Las Vegas high rise condo jumbo loans and warrantability.
- Las Vegas jumbo loan down payment and reserves 2026.
- Las Vegas jumbo loans for new construction and custom homes.
- Nevada mortgage after business change a self employed guide.
- Prep S-Corp taxes for Las Vegas jumbo loan approval.
- Qualify for a Las Vegas jumbo loan with no W-2s.
- Qualify for a Las Vegas mortgage as an S-Corp owner.
- S corp mortgage guide for business owners in Nevada.
- S corp mortgage in Nevada get approved after a business change.
- S corp switch & your Nevada mortgage how to get approved.
- Use your portfolio for a Nevada jumbo loan in 2026.
- Using S-Corp income for a mortgage in Nevada.
- When to apply for a self employed mortgage in Nevada.
Which Nevada guides cover reserves, appraisals, credit, gifts and refinancing?
- Avoid closing costs on a Nevada home 2026 guide.
- Buying a home from a trust in Las Vegas a guide.
- Can a non relative gift my down payment in Nevada.
- Cash from a Nevada rental with a DSCR refinance.
- Clark county property tax and transfer tax on a Las Vegas DSCR rental.
- DSCR cash out refinance to scale a Las Vegas rental portfolio.
- DSCR loan reserve rules in Las Vegas Nevada explained.
- DSCR loan reserves in Las Vegas Nevada a guide for investors.
- Get a Las Vegas mortgage with no credit score in Nevada.
- Get a mortgage on a home in a trust in Nevada.
- How to refinance in Nevada to buy out your spouse.
- How to speed up your Las Vegas DSCR loan refinance.
- How to use a gift of equity in Nevada for a mortgage.
- Mortgage recast vs refinance in Nevada which saves more.
- Nevada 1099 mortgage guide for gig worker income.
- Nevada HELOC vs cash out refinance fund your next home.
- Nevada non recurring closing costs explained for homebuyers.
- Protect your credit score during escrow in Las Vegas Nevada.
- Summerlin jumbo loans for guard gated and golf course homes.
- Systematize appraisals for success in Las Vegas Nevada.
- Tap Nevada rental equity without a cash out refinance.
- VA cash out refinance vs HELOC in Nevada a 2024 guide.
- What is a rate and term refinance in Las Vegas Nevada.
- What to do after a failed VA appraisal in Nevada.
Which other Nevada home loan guides might help?
- 2025 guide Nevada DSCR investor loans.
- A DSCR loan for a Las Vegas non warrantable condo guide.
- A foreign buyers guide to Nevada rental property loans.
- A guide to buying a Las Vegas home anonymously.
- A guide to de risking new construction loans in Nevada.
- A letter of explanation can save your Las Vegas mortgage.
- Are mortgage points a waste of money in Nevada.
- Authorized user accounts & your Nevada mortgage approval.
- Best loan for a multi gen home in Las Vegas Nevada.
- Best property type for a DSCR loan in Nevada.
- Beyond 10 mortgages in Nevada a guide for investors.
- Buy a Las Vegas home before you sell your current one.
- Buy a Las Vegas rental after foreclosure sooner than you think.
- Buying a Las Vegas rental with an itin investor loan.
- Can a lender revoke a mortgage commitment in Nevada.
- Can DSCR loans use casita rent in Las Vegas Nevada.
- Credit dispute halting your Las Vegas Nevada mortgage.
- Credit mistakes that kill a mortgage in Las Vegas Nevada.
- Deed in lieu and your next mortgage in Nevada.
- Dpa vs seller credits for a Las Vegas Nevada home loan.
- DSCR loan for a Las Vegas house hack a smart guide.
- DSCR loan guide for fixer upper rentals in Nevada.
- DSCR loan guide for mid term rentals in Nevada.
- DSCR loan in Las Vegas & Henderson with no lease.
- DSCR loans and high hoas in Las Vegas and Henderson.
- DSCR loans and hoa rules in Nevada a lenders guide.
- DSCR loans finance a Las Vegas condo hotel unit.
- DSCR loans for Las Vegas condo hotels your guide.
- DSCR loans for Las Vegas short term rentals explained.
- DSCR loans for new construction rentals in Las Vegas.
- DSCR Renovation loans for fixer uppers in Reno Nevada.
- DSCR vs blanket loans a guide for Nevada investors.
- Finance 5 Nevada rentals with one blanket mortgage loan.
- Financing 5 unit rentals in Las Vegas Nevada a guide.
- Financing a 5 unit property in Las Vegas Nevada.
- Financing a Las Vegas condo hotel with a DSCR loan.
- Financing a Nevada fix and flip a complete guide.
- Financing past 10 mortgages in Las Vegas Nevada.
- First time homebuyer in Las Vegas.
- Fix a credit error during your Las Vegas mortgage escrow.
- Fix a credit report error during escrow in Las Vegas.
- Fix credit report errors during a Las Vegas escrow.
- Get a DSCR loan in Nevada with no rent roll.
- Get a Las Vegas mortgage after a bad business year.
- Get a mortgage in Las Vegas Nevada with no fico score.
- Get a Nevada mortgage with a business loss.
- Getting a mortgage in Nevada with cannabis income.
- Good credit but denied a Las Vegas Nevada mortgage why.
- Good credit denied mortgage in Las Vegas heres why.
- Guide to DSCR Renovation loans in Las Vegas Nevada.
- Guide to foreign national loans in Nevada.
- Henderson and north Las Vegas DSCR loans for single family rentals.
- How appraisers calculate rent for a Las Vegas DSCR loan.
- How co borrower debt can block your Henderson home loan.
- How hoa rules block DSCR loans in Las Vegas Nevada.
- How lenders calculate gig worker income in Nevada.
- How lenders project rent for Las Vegas DSCR loans.
- How lenders verify tip income for a mortgage in Nevada.
- How much cash do you need to close on a Nevada home.
- How payment shock can derail your Nevada mortgage loan.
- How to buy a Nevada home with limited credit history.
- How to buy more rentals in Nevada with a portfolio loan.
- How to get a Las Vegas mortgage after quitting your w 2 job.
- How to get a mortgage on a tax extension in Nevada.
- How to prove your Henderson financed offer is a sure thing.
- How to read Nevada hoa docs for a condo loan.
- How to rescue a failing escrow in Las Vegas Nevada.
- How to stress test a DSCR loan in Nevada.
- How to use airdna for a DSCR loan in Nevada in 2025.
- How your mortgage escrow account works in Nevada.
- Investor loan in Las Vegas Nevada after bankruptcy a guide.
- Las Vegas dpa a good deal or a costly trap for buyers.
- Las Vegas duplex triplex and fourplex DSCR loans.
- Las Vegas lender credits vs seller credits which is better.
- Las Vegas mortgage for new businesses how soon can you buy.
- Las Vegas short term rental DSCR loans city rules 2026.
- Loan denied after clear to close in Nevada heres why.
- Making your financed offer win in Las Vegas Nevada.
- Medical debt and your 2026 Nevada mortgage approval.
- Mortgage points vs rate buydown in Las Vegas Nevada.
- Mortgage shopping in Las Vegas will it hurt your credit.
- Nevada BRRRR bypass seasoning with a DSCR loan.
- Nevada business taxes and your home mortgage qualification.
- Nevada condo hotel financing a guide to DSCR loans.
- Nevada dpa grant vs forgivable loan for homebuyers.
- Nevada DSCR vs conventional loan which is better.
- Nevada foreign national loan documents you need.
- Nevada itin vs foreign national loan a direct comparison.
- Nevada mortgage guide for thin credit files.
- Nevada portfolio loans for foreign investors guide.
- Nevada portfolio loans for your rental properties.
- Nevada rentals blanket loan vs multiple investor loans.
- Nevada sid and lid fees explained for homebuyers.
- New collection in escrow in Nevada how to save your loan.
- Old vs new debt what hurts a Las Vegas mortgage most.
- One time close construction loans in Nevada explained.
- Parents credit wrecked my Las Vegas mortgage heres a fix.
- Portfolio loans for Las Vegas BRRRR real estate investing.
- Portfolio loans for Nevada rentals a Las Vegas guide.
- Portfolio vs DSCR loans in Nevada for rental growth.
- Qualify for a DSCR loan with casita rent in Las Vegas.
- Qualifying for a Nevada mortgage with a spousal salary.
- Rapid rescore guide for mortgages in Nevada.
- Rate buydown or more down in Nevada which saves more.
- Real risks of a co signed mortgage in Nevada.
- Renovation loans.
- Restore VA loan entitlement after divorce in Las Vegas.
- Secure top offers de risk your Las Vegas home sale.
- Should you recast your mortgage in Nevada a guide.
- Tax extension for a Nevada mortgage a strategic guide.
- Thin credit mortgage in Las Vegas & Henderson Nevada guide.
- Unmarried homebuyers guide for Nevada.
- Use home equity to buy a rental property in Nevada.
- Use rental history for a Las Vegas mortgage in Nevada.
- Using a 401k loan for a down payment in Nevada.
- Using a construction loan to build a home in Nevada.
- Using a DSCR loan for a seasonal Las Vegas rental.
- Using a power of attorney for a Nevada mortgage closing.
- Using a VA loan to buy a Las Vegas condo in Nevada.
- Using an energy efficient mortgage in Nevada explained.
- Using casita income for a Nevada DSCR loan approval.
- Using foreign funds for a Nevada mortgage a guide.
- Using lender credits on a Nevada mortgage.
- Using seller credits in Las Vegas to win your offer.
- VA condo approval in Las Vegas and Henderson Nevada.
- VA loan with low credit in Las Vegas its possible.
- Waive a loan contingency in Nevada a cash offer guide.
- What is a cross collateral loan in Nevada for rentals.
- What is a seller bridge solution in Las Vegas Nevada.
- What is the buyer power index in Las Vegas Nevada.
- When to lock a mortgage rate in Las Vegas Nevada.
- Why a DSCR loan protects your next loan in Las Vegas.
- Why did my Nevada mortgage payment go up escrow explained.
- Why Las Vegas Nevada homeowners insurance is so high.
- Why your good credit gets denied for a Las Vegas mortgage.
- Why your Las Vegas mortgage payment increased.
- Why your mortgage score in Nevada is lower than you think.
- Will my unique Las Vegas property get a DSCR loan in Nevada.
- Will paying collections hurt my Las Vegas mortgage score.
- Your cpa mortgage guide for Las Vegas & Henderson homebuyers.
- Your first DSCR loan guide for Las Vegas Nevada.
- Zoning risk the hidden DSCR loan killer in Las Vegas Nevada.
Sources
- FHFA, 2026 conforming loan limits (county file)
- HUD, FHA loan limits, Carson City, NV MSA 16180 (CY2026) and the HUD FHA limits lookup
- FFIEC HMDA Data Browser (2024 and 2025 loan-level data) and CFPB, about HMDA data
- CFPB, Loan Estimate explainer and Closing Disclosure explainer
- CFPB, Regulation Z timing rule, 12 CFR 1026.19 and Regulation B appraisal copies, 12 CFR 1002.14
- Census Bureau TIGERweb (tract and ZIP geography)
- Nevada Department of Taxation, real property transfer tax and Local Government Finance (tax rates)
- Carson City Assessor
- NRS 361.4723, 3% primary-residence tax cap
- VA, loan limits and funding fee
- Nevada Rural Housing, down payment assistance
- NMLS Consumer Access
Data checked November 5, 2026. The HMDA figures are iQRATE's own analysis of public data.
Talk to David about a Carson City jumbo loan
Tell us three things: the price, the address or ZIP, and how you earn income. We will show you whether you are jumbo, how much down keeps you conforming, and which lenders fit. Then you get it in writing.
- Call or text (702) 766-3744
- Apply now
- Schedule a free consultation
iQRATE Mortgages LLC, NMLS 1862492, 6360 S Rainbow Blvd Ste 101, Las Vegas, NV 89118. We are a Las Vegas-based Nevada brokerage serving Carson City remotely, and closings go through local escrow. David Ghazaryan, Mortgage Broker, NMLS 1486726. Verify licensing on NMLS Consumer Access.
By David Ghazaryan, NMLS 1486726, iQRATE Mortgages (NMLS 1862492). Updated November 5, 2026.
iQRATE Mortgages is a mortgage broker, not a lender, and does not make credit decisions. Broker compensation is disclosed on your Loan Estimate and Closing Disclosure. This page is general information. It is not a loan offer and not a commitment to lend. All loans are subject to credit, property and underwriting approval. Programs, terms, down payment, reserve and credit requirements vary by lender and change often, and not all borrowers will qualify. Dollar figures are simple arithmetic from public rules and public data, not a quote; no interest rate or APR is shown. HMDA figures are iQRATE's analysis of public data and are based on small counts. Reviews describe our company overall and are not a promise about your loan. Investor loans are for business purposes only. Tax facts are not legal or tax advice. Equal Housing Opportunity.