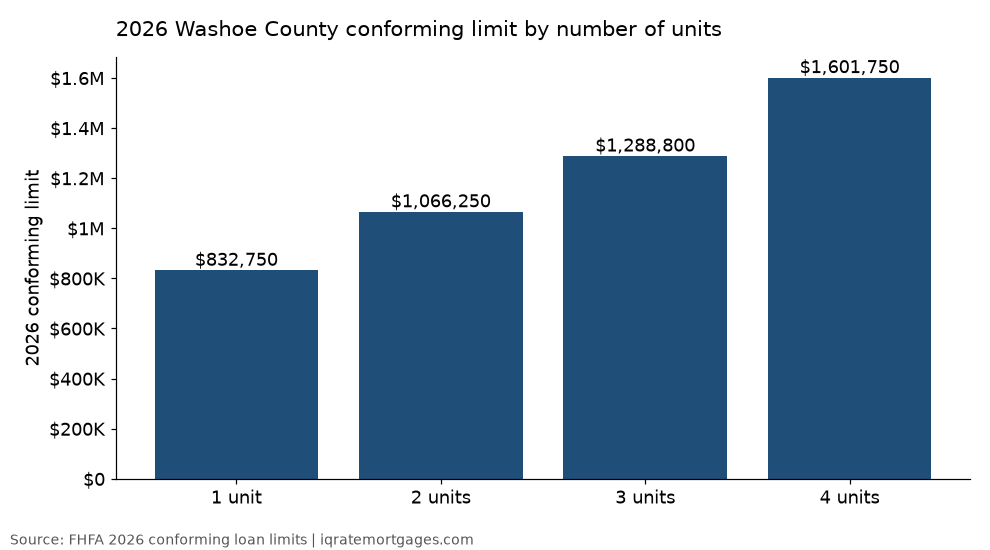
Short answer: In Washoe County, the 2026 conforming limit for a one-unit home is $832,750 (FHFA). Any loan above that is a jumbo loan. In Reno, jumbo loans cluster in south and southwest Reno, not in the city as a whole.
By David Ghazaryan, NMLS 1486726, iQRATE Mortgages (NMLS 1862492). Updated November 5, 2026.
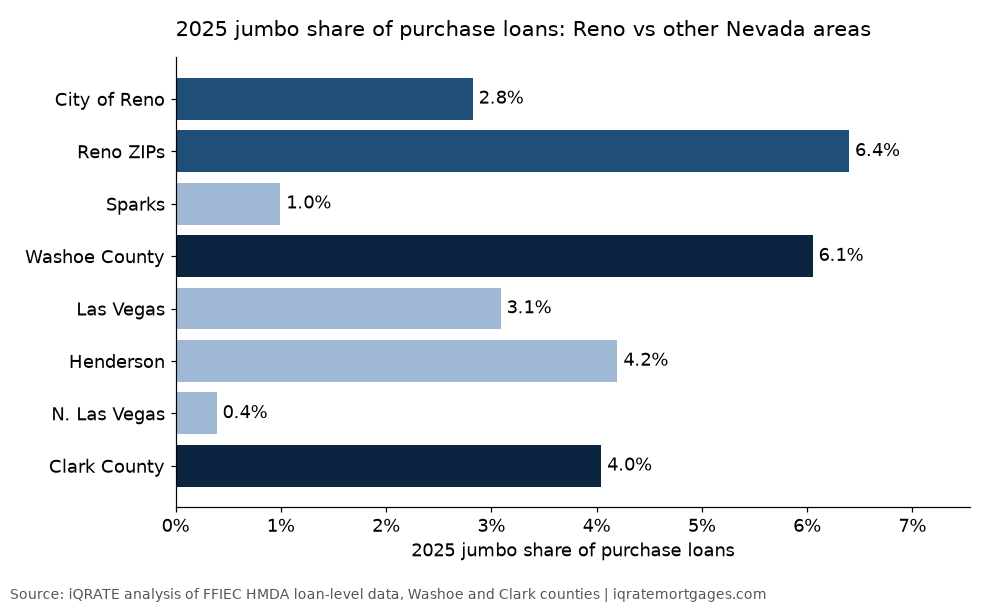
Inside City of Reno census tracts, only 2.8% of 2025 home purchase loans were jumbo (61 of 2,161). Across all Reno-address ZIP codes, the share was 6.4% (193 of 3,017). In 89511 (South Reno, Galena, ArrowCreek), it was about 1 in 3 (96 of 283). These figures come from our own analysis of public HMDA loan records. The method is explained below.
Key facts (updated November 5, 2026) - 2026 Washoe County limit, one unit: $832,750. Above that is jumbo (FHFA). - The limit rose $26,250 from 2025. Pages that still use $806,500 (2025) or $766,550 (2024) are out of date. - Median 2025 jumbo purchase loan: $955,000 in City of Reno tracts and $1,135,000 in the Reno-address ZIP area. - Median loan-to-value on those loans: 80%, in both areas. - About a third of 2025 jumbo buyers chose an adjustable rate. In City of Reno tracts, 15 of the 21 jumbo ARMs had a 7-year fixed start. - Typical lender asks (vary by lender): 10-20% down, a credit score around 700 or higher, and 6-12 months of reserves. - iQRATE is a Nevada brokerage based in Las Vegas. We serve Reno remotely and close through Washoe County title and escrow.
Call or text (702) 766-3744 or apply now. Ratings: Google 5.0 from 77 reviews, Yelp 5.0 from 51, Zillow 5.00 from 9.
What is the 2026 jumbo loan limit in Washoe County?
A loan is jumbo when the loan amount is above the conforming limit. The price of the home doesn't decide it. Every Nevada county uses the same 2026 limits, so there is no "high-balance" tier in Washoe.
| Units | 2026 limit | Jumbo if the loan is above |
|---|---|---|
| 1 unit | $832,750 | $832,750 |
| 2 units | $1,066,250 | $1,066,250 |
| 3 units | $1,288,800 | $1,288,800 |
| 4 units | $1,601,750 | $1,601,750 |
Past one-unit limits: $806,500 in 2025 and $766,550 in 2024. The 2026 limit is $66,200 higher than the 2024 one.
Source: FHFA conforming loan limits.

Where do Reno jumbo loans actually happen?
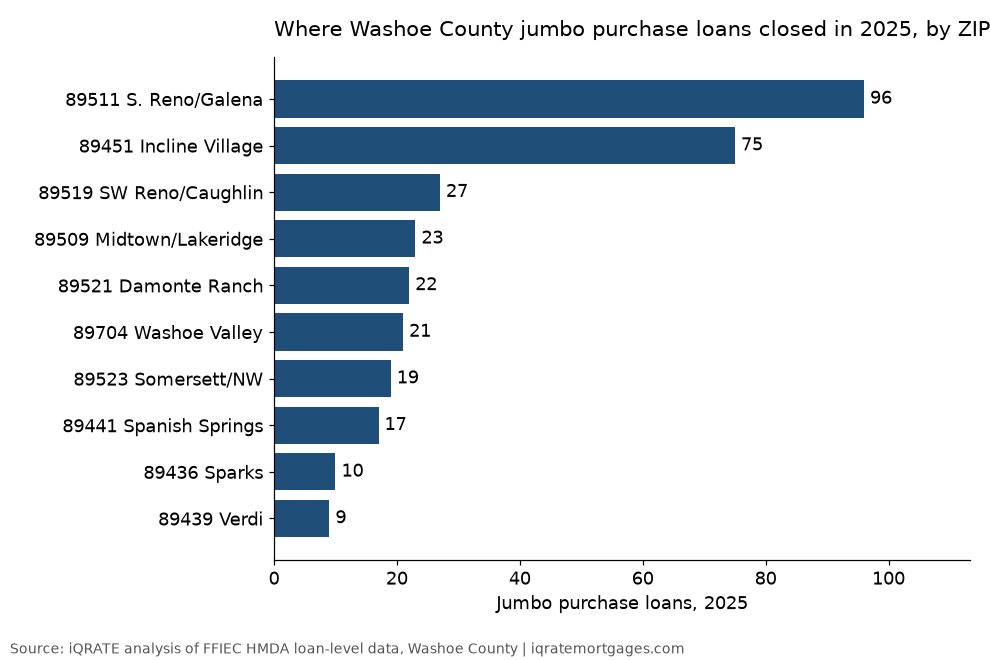
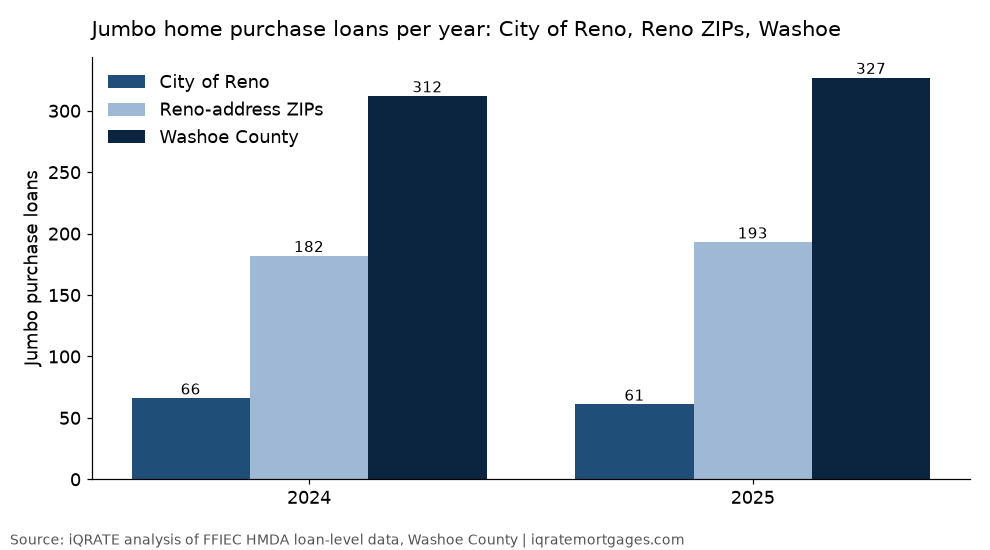
Short answer: mostly outside city limits. Only 61 of Washoe County's 327 jumbo purchase loans in 2025 (18.7%) were in City of Reno tracts. Two ZIPs, 89511 and Incline Village (89451), held 52.3% of them.
| Area | 2024 loans | 2024 jumbo | 2024 share | 2025 loans | 2025 jumbo | 2025 share |
|---|---|---|---|---|---|---|
| City of Reno (73 in-city tracts) | 2,010 | 66 | 3.3% | 2,161 | 61 | 2.8% |
| Reno-address ZIP area (87 tracts) | 2,744 | 182 | 6.6% | 3,017 | 193 | 6.4% |
| Washoe, outside Reno and Sparks cities | 2,077 | 243 | 11.7% | 2,338 | 257 | 11.0% |
| Sparks city | 797 | 3 | 0.4% | 905 | 9 | 1.0% |
| Washoe County | 4,884 | 312 | 6.4% | 5,404 | 327 | 6.1% |
| Las Vegas city | 6,867 | 207 | 3.0% | 6,154 | 190 | 3.1% |
| Henderson city | 5,626 | 255 | 4.5% | 5,195 | 218 | 4.2% |
| North Las Vegas city | 3,967 | 3 | 0.1% | 3,598 | 14 | 0.4% |
The Washoe jumbo share is about 2.1 times the City of Reno share (6.1% vs 2.8%). Inside city limits, Reno looks a lot like Las Vegas. The jumbo market is mostly outside city limits: south and southwest Reno, plus Lake Tahoe's north shore.
How we got these numbers - Source: public loan-level HMDA files for Washoe County, 2024 and 2025, from the FFIEC HMDA Data Browser. - What we counted: originated, first-lien, closed-end home purchase loans. HELOCs and reverse mortgages are not included. - What "jumbo" means here: HMDA's own flag for loans above that year's limit. That limit was $766,550 in 2024 and $806,500 in 2025. - City of Reno: the 73 census tracts whose Census Bureau internal point falls inside city limits (Census TIGERweb, 2020). The 73 tracts' combined population equals 93.3% of the city's population; edge tracts can include land outside the city. - Reno-address ZIP area: 87 Washoe tracts in Reno mailing ZIPs. It adds unincorporated south and southwest Reno. Incline Village and Sparks are not in either Reno figure. - Limits of the data: - HMDA reports amounts in $10,000 bands. - HMDA counts loans, not cash buyers, so all-cash luxury sales don't appear. - City of Reno counts are small, so treat its shares with care. - Why our Reno mortgage broker page shows a different Washoe count: that page counts loans above $832,750 (306 of 5,134). This page uses HMDA's 2025 jumbo flag ($806,500), so its count is a little higher.
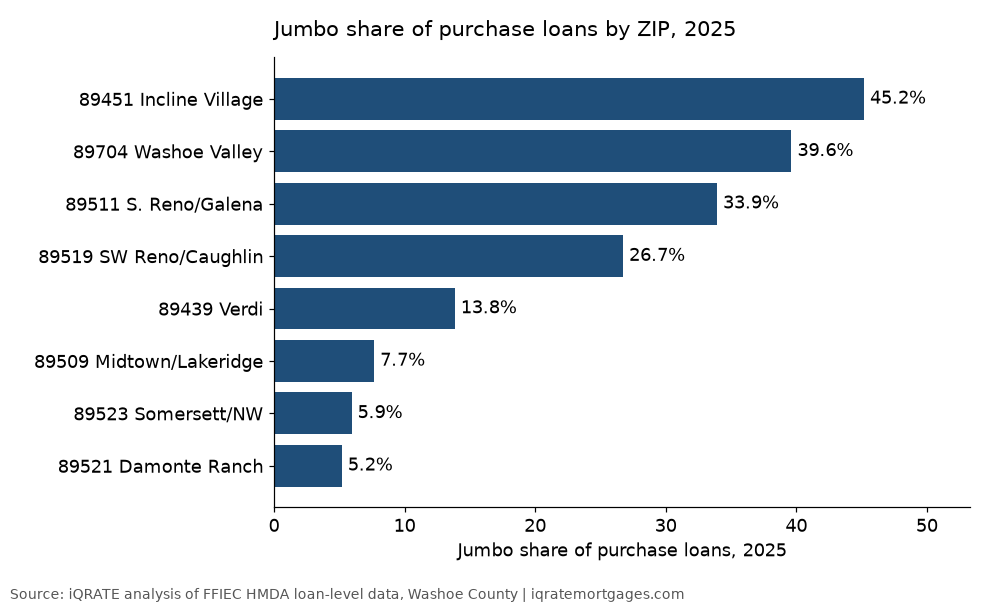
Which Reno-area ZIP codes have the most jumbo loans?
| ZIP | Area | 2024 jumbo share | 2025 jumbo loans | 2025 jumbo share |
|---|---|---|---|---|
| 89451 | Incline Village (Lake Tahoe north shore) | 56.6% | 75 of 166 | 45.2% |
| 89704 | Washoe Valley | 23.1% | 21 of 53 | 39.6% |
| 89511 | South Reno, Galena, ArrowCreek | 32.7% | 96 of 283 | 33.9% |
| 89519 | Old Southwest, Caughlin Ranch | 25.3% | 27 of 101 | 26.7% |
| 89439 | Verdi | 10.5% | 9 of 65 | 13.8% |
| 89509 | Midtown, Central, Lakeridge | 12.6% | 23 of 300 | 7.7% |
| 89523 | Somersett, Northwest Reno | 6.2% | 19 of 320 | 5.9% |
| 89521 | Damonte Ranch, South Meadows | 5.6% | 22 of 424 | 5.2% |
| 89441 | Spanish Springs | 6.9% | 17 of 373 | 4.6% |
| 89436 | Sparks | 0.5% | 10 of 928 | 1.1% |
A key detail: the 89511 tracts whose internal point is inside Reno city limits had zero jumbo purchase loans in 2025. All 96 were in tracts whose internal point is outside city limits. Those homes still carry a Reno address. For context, the June 2026 median list price was $745,000 in 89511 and $725,000 in 89519 (NNRMLS via Nevada Real Estate Group).

What does a typical Reno jumbo loan look like?
| Measure | City of Reno 2024 | City of Reno 2025 | Reno ZIPs 2024 | Reno ZIPs 2025 |
|---|---|---|---|---|
| Jumbo purchase loans | 66 | 61 | 182 | 193 |
| Median jumbo loan | $945,000 | $955,000 | $1,015,000 | $1,135,000 |
| Median home value | $1,190,000 | $1,255,000 | $1,355,000 | $1,515,000 |
| Median loan-to-value | 80% | 80% | 80% | 80% |
| Median borrower income | $347,000 | $369,500 | $412,000 | $427,500 |
| Adjustable rate | 19 (28.8%) | 21 (34.4%) | 56 (30.8%) | 66 (34.2%) |
| Interest-only | 2 | 3 | 16 | 14 |
| Primary residence | 64 of 66 | 60 of 61 | 167 of 182 | 185 of 193 |
| VA loans above the limit | 9 | 10 | 22 | 32 |
| Different lenders | 40 | 33 | 68 | 65 |
What this tells you: - In the ZIP area, the median jumbo loan rose $120,000 in one year. - The City of Reno median of $955,000 is $122,250 above the 2026 limit. - Nearly every Reno jumbo buyer was buying a primary home. - 65 different lenders made these loans in the ZIP area, and each one sets its own rules. That is why shopping matters.
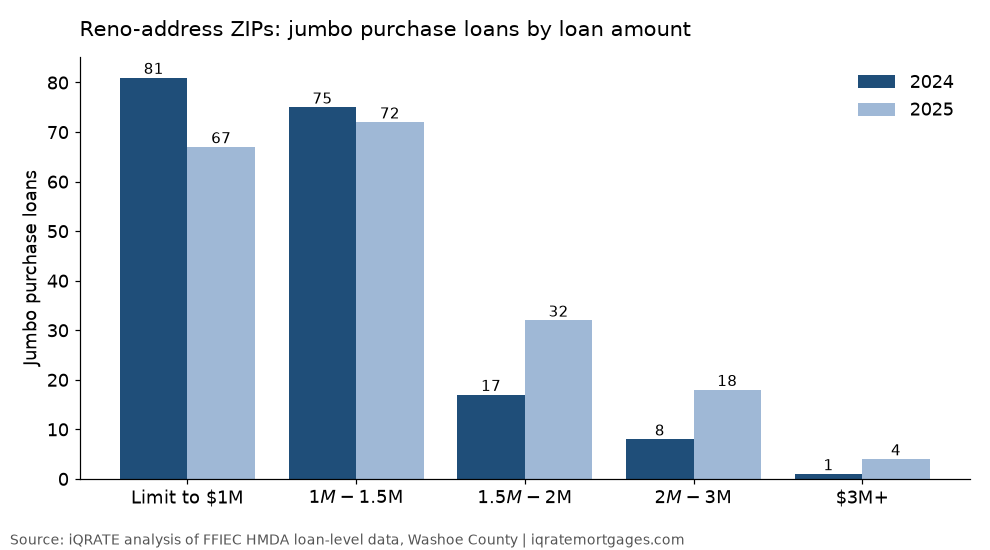
| Loan amount | City 2024 | City 2025 | Reno ZIPs 2024 | Reno ZIPs 2025 |
|---|---|---|---|---|
| Above the limit to under $1M | 38 | 37 | 81 | 67 |
| $1M to under $1.5M | 25 | 23 | 75 | 72 |
| $1.5M to under $2M | 3 | 1 | 17 | 32 |
| $2M to under $3M | 0 | 0 | 8 | 18 |
| $3M or more | 0 | 0 | 1 | 4 |
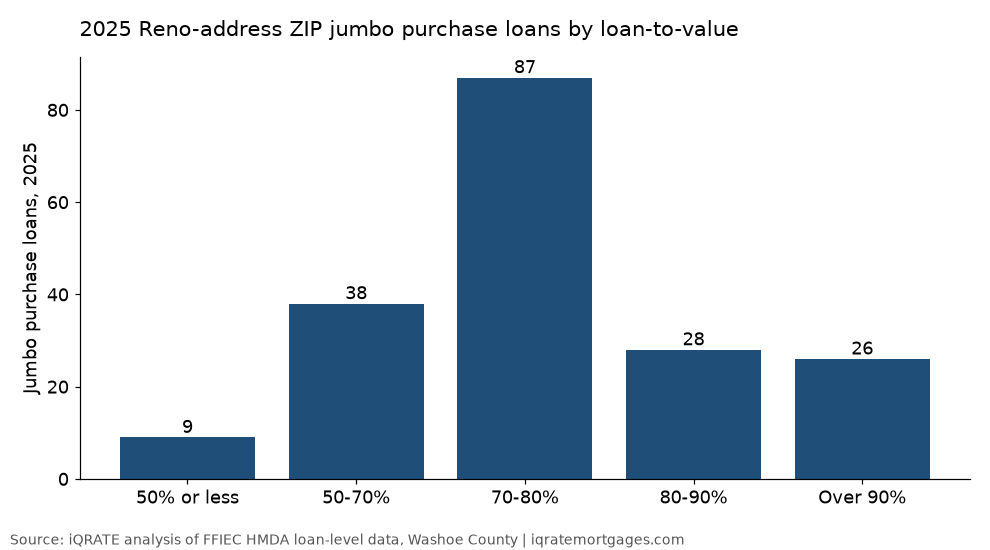
| Loan-to-value | City 2024 | City 2025 | Reno ZIPs 2024 | Reno ZIPs 2025 |
|---|---|---|---|---|
| 50% or less | 0 | 3 | 9 | 9 |
| Over 50% to 70% | 10 | 9 | 40 | 38 |
| Over 70% to 80% | 32 | 31 | 87 | 87 |
| Over 80% to 90% | 11 | 8 | 22 | 28 |
| Over 90% | 12 | 9 | 21 | 26 |
In City of Reno tracts, 43 of the 60 jumbo loans with a reported LTV (71.7%) were at 80% or less. So most buyers put at least 20% down. Some did close with less.




Is my Reno loan conforming or jumbo?
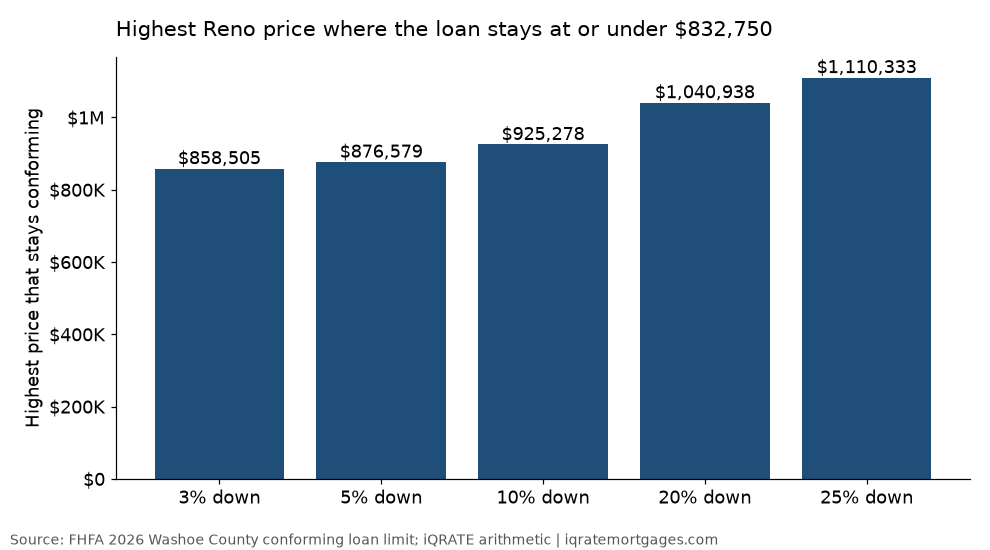
Short answer: it depends on your down payment. With 20% down, a one-unit loan stays conforming up to a price of $1,040,938. Above that, it turns jumbo.
For scale, Reno's single-family median was about $682,000 in September 2026 (Northern Nevada Regional MLS data). Even with 3% down, the jumbo line starts at a price of $858,505. So a typical Reno home sits well below it. Jumbo buyers shop at the top of the market.
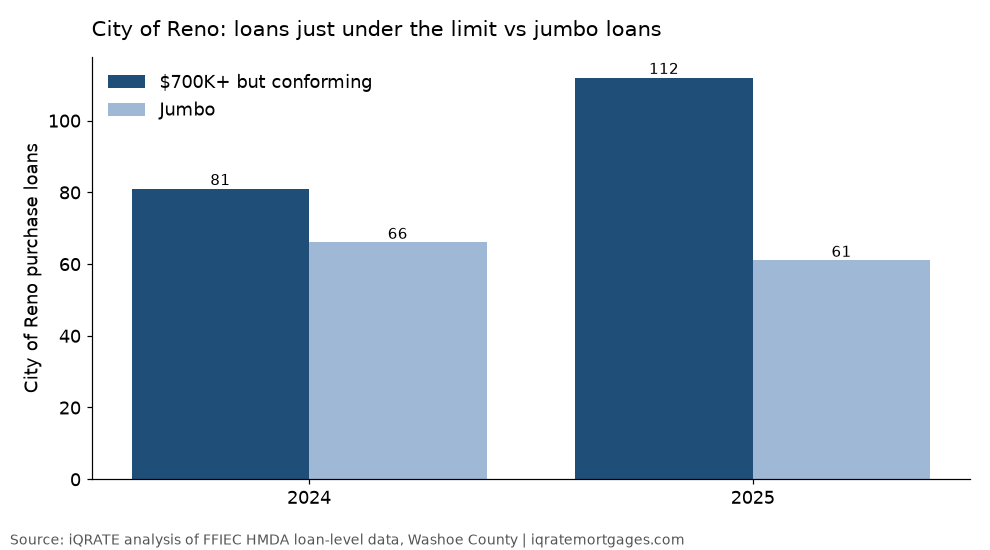
This matters near the line. In 2025, City of Reno tracts had 112 conforming purchase loans of $700,000 or more, against 61 jumbo loans. That is almost twice as many buyers who stayed just under the line. About 6 of the 61 jumbo loans from 2025 were sized at or under $832,750. A loan that size would be conforming in 2026.
| Down payment | Loan-to-value | Highest conforming price |
|---|---|---|
| 3% | 97% | $858,505 |
| 5% | 95% | $876,579 |
| 10% | 90% | $925,278 |
| 15% | 85% | $979,706 |
| 20% | 80% | $1,040,938 |
| 25% | 75% | $1,110,333 |
| 30% | 70% | $1,189,643 |
| Price | 10% down | 20% down | 25% down | 30% down |
|---|---|---|---|---|
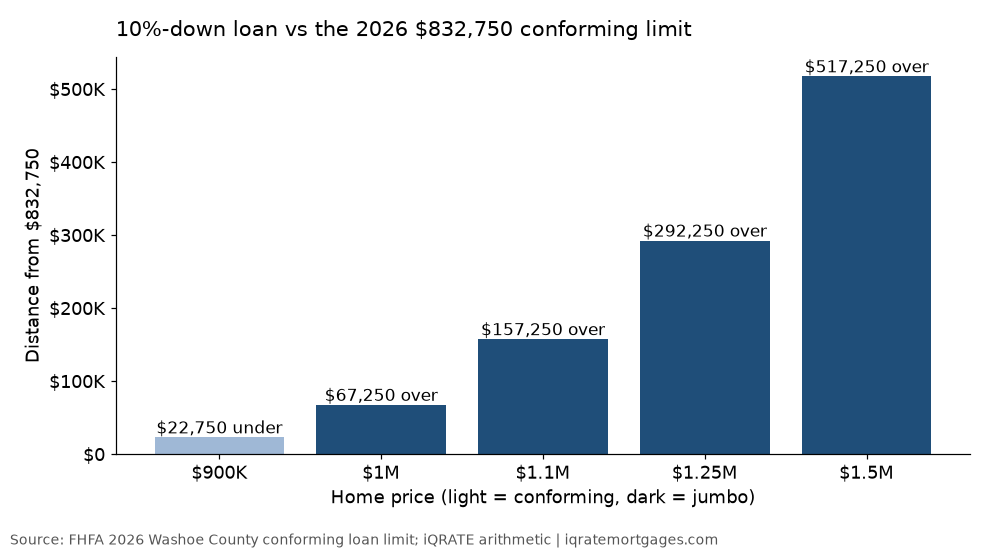
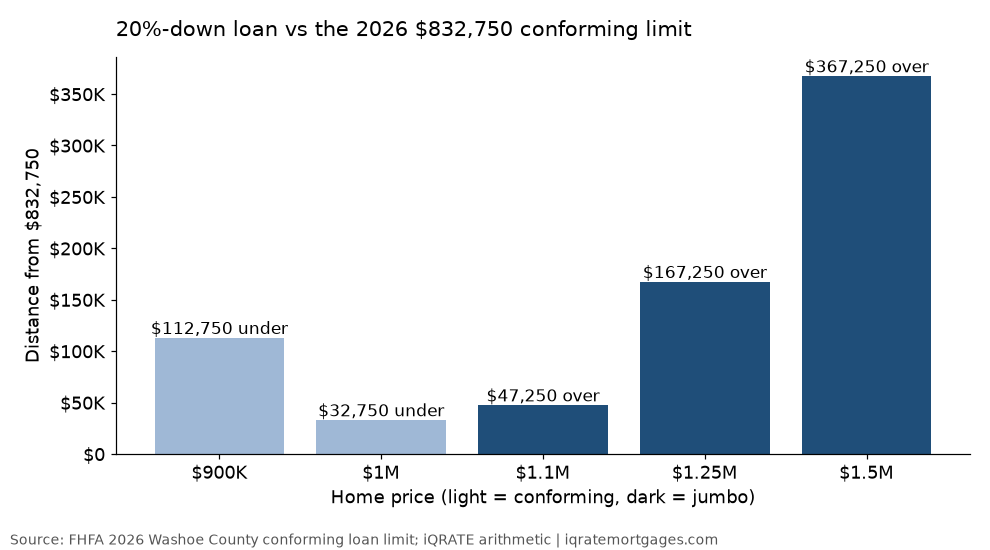
| $900,000 | $810,000: conforming, $22,750 under | $720,000: conforming, $112,750 under | $675,000: conforming, $157,750 under | $630,000: conforming, $202,750 under |
| $1,000,000 | $900,000: jumbo, $67,250 over | $800,000: conforming, $32,750 under | $750,000: conforming, $82,750 under | $700,000: conforming, $132,750 under |
| $1,100,000 | $990,000: jumbo, $157,250 over | $880,000: jumbo, $47,250 over | $825,000: conforming, $7,750 under | $770,000: conforming, $62,750 under |
| $1,250,000 | $1,125,000: jumbo, $292,250 over | $1,000,000: jumbo, $167,250 over | $937,500: jumbo, $104,750 over | $875,000: jumbo, $42,250 over |
| $1,500,000 | $1,350,000: jumbo, $517,250 over | $1,200,000: jumbo, $367,250 over | $1,125,000: jumbo, $292,250 over | $1,050,000: jumbo, $217,250 over |
| $2,000,000 | $1,800,000: jumbo, $967,250 over | $1,600,000: jumbo, $767,250 over | $1,500,000: jumbo, $667,250 over | $1,400,000: jumbo, $567,250 over |
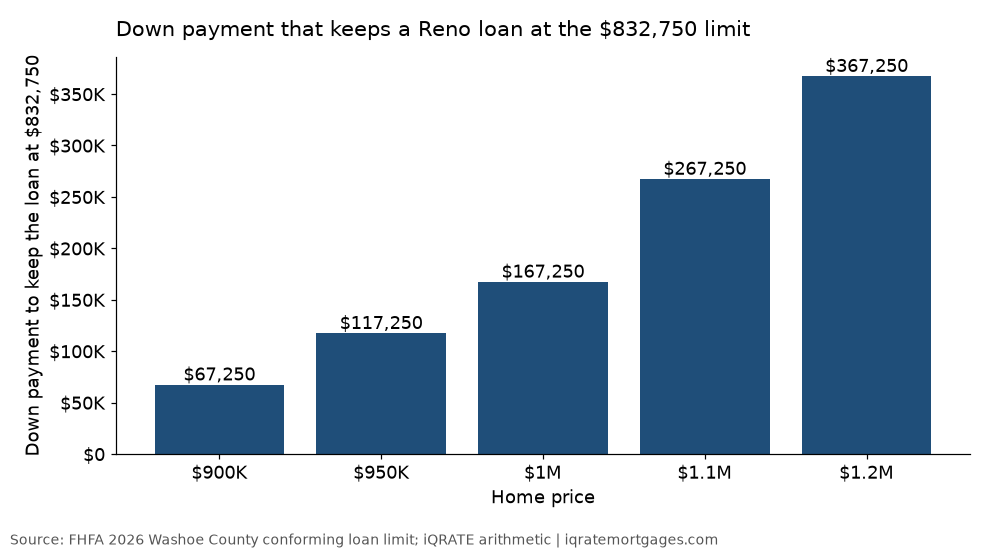
| Price | Down payment to stay conforming | Share of price |
|---|---|---|
| $900,000 | $67,250 | 7.5% |
| $950,000 | $117,250 | 12.3% |
| $1,000,000 | $167,250 | 16.7% |
| $1,100,000 | $267,250 | 24.3% |
| $1,200,000 | $367,250 | 30.6% |
For example, on a $1,100,000 home, 20% down ($220,000) leaves a jumbo loan of $880,000. Putting 25% down ($275,000) brings the loan to $825,000, which is $7,750 under the limit.
Staying conforming isn't always the cheaper route. Some buyers pair a conforming first loan with a second lien instead. See piggyback vs jumbo in Reno. We lay out the total cash to close and the fees for each option side by side.
Near the line? Call or text (702) 766-3744. We run both versions before you write an offer.


Reno jumbo requirements at a glance
| Requirement | Typical range across lenders | What 2025 Reno HMDA data shows |
|---|---|---|
| Jumbo threshold, one unit | Loan above $832,750 (FHFA 2026) | Median jumbo loan $955,000 (city), $1,135,000 (ZIPs) |
| Down payment | Often 10-20% | Median LTV 80% in both areas |
| Credit score | Many lenders start around 700 | Not in public HMDA data |
| Debt-to-income | Commonly up to about 43%; some go higher with strong reserves | Most City of Reno jumbo loans reported a DTI under 43% |
| Reserves after closing | Commonly 6-12 months of payments, more on larger loans | Not in public HMDA data |
| Appraisal | Full appraisal; a second one is common on larger loans | Collateral was the main reason in 6 of 46 ZIP-area jumbo denials |
| Income documents | Tax returns and W-2s, or bank statements, or asset depletion | 65 lenders in the ZIP area, each with its own rules |
| Property types | Single-family, foothill and acreage (extra review), condos (project review), second homes | Every City of Reno jumbo was a one-unit home |
Every lender sets its own guidelines. These are typical ranges, not a commitment to lend.
| DTI | Loans |
|---|---|
| Under 20% | 5 |
| 20% to under 30% | 8 |
| 30% to under 36% | 11 |
| 36% to under 43% | 19 |
| 43% to under 50% | 12 |
| 50% to 60% | 4 |
| Over 60% | 2 |
What counts as jumbo reserves?
Reserves are liquid funds left after your down payment and closing costs. Lenders count them in months of the full housing payment. That means principal, interest, taxes, insurance and HOA dues.
- What usually counts: checking, savings, money market and brokerage accounts. Vested retirement accounts count too, often at a discounted value (varies by lender).
- What usually doesn't count: gift funds, a HELOC or other borrowed money. In many cases business assets don't count either, unless the lender accepts a CPA letter.
- What raises the requirement: a larger loan, second-home or investment use, non-QM documents, and each extra financed property you own.
Lenders want reserves seasoned in your accounts, commonly about two months of statements. Large recent deposits need a paper trail. Tell us before you move money.
Should a Reno jumbo buyer pick an ARM or a fixed rate?
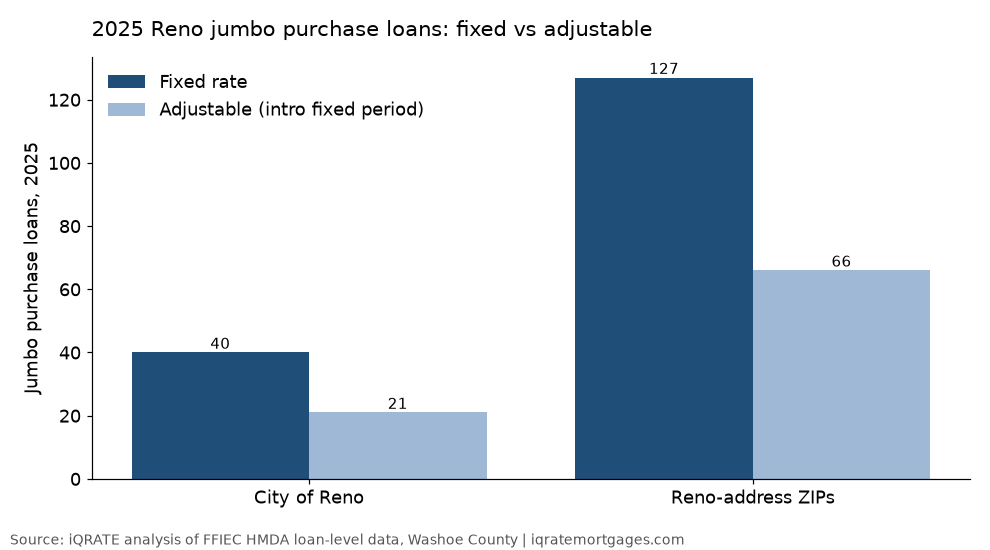
Here is what Reno buyers actually chose: - City of Reno, 2025: 21 of 61 jumbo loans (34.4%) had an adjustable rate. Of those, 15 had a 7-year (84-month) fixed start. - Reno ZIP area, 2025: 66 of 193 (34.2%) were ARMs. - Interest-only payments: 3 loans in the city and 14 in the ZIP area.
How the two types work: - Fixed rate: the rate and the principal-and-interest payment stay the same for the whole term, usually 30 years. - ARM: the rate is fixed for a set period, then adjusts within caps. It can suit buyers who expect to sell or refinance before the fixed period ends. The risk is a higher payment later.
Ask any lender two questions: what are the caps, and what is the worst-case payment? We don't quote rates on this page. Pricing changes daily and by lender.
Why do Reno jumbo applications get denied?
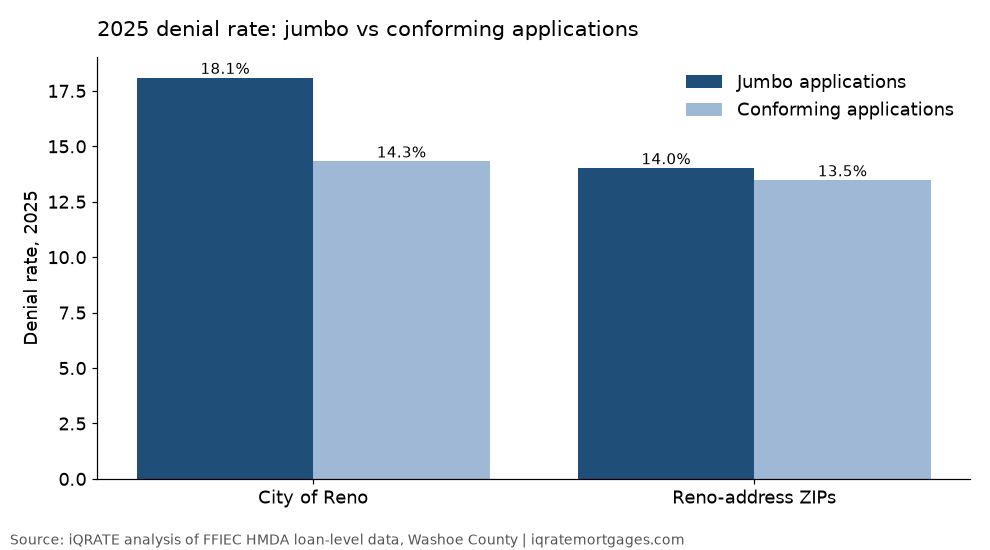
Short answer: debt-to-income is the top reason. It was the main reason in 21 of 46 denied jumbo applications in the Reno ZIP area in 2025 (45.7%).
| Area, year | Jumbo decided | Jumbo denied | Jumbo rate | Conforming rate |
|---|---|---|---|---|
| City of Reno, 2024 | 83 | 7 | 8.4% | 14.2% |
| City of Reno, 2025 | 105 | 19 | 18.1% | 14.3% |
| Reno ZIPs, 2024 | 271 | 37 | 13.7% | 13.1% |
| Reno ZIPs, 2025 | 328 | 46 | 14.0% | 13.5% |
| Reason | City of Reno (19) | Reno ZIPs (46) |
|---|---|---|
| Debt-to-income ratio | 9 | 21 |
| Other | 3 | 9 |
| Collateral (appraisal or property) | 3 | 6 |
| Credit history | 2 | 3 |
| Incomplete application | 1 | 3 |
| Insufficient cash | 1 | 3 |
| Unverifiable information | 0 | 1 |
Read these numbers with care. City of Reno counts are small. One year was 18.1% and the year before was 8.4%. The steadier signal is the ZIP area, where jumbo and conforming denial rates are close.
Several of these reasons can be addressed by how the file is documented. Income may be counted the wrong way, reserves may come up short, or a deposit may have no paper trail. Here is how David approaches a file another lender turned down:
"I don't begin by assuming the first lender made a mistake. I begin by finding out exactly why that lender couldn't approve the transaction. Was it income calculation? Insufficient reserves? Restricted stock? A debt-to-income limit? A property that didn't satisfy the lender's appraisal requirements? Those are very different problems." (David Ghazaryan)
Video: Bank Denied Your Loan? Do This Instead. David Ghazaryan explains what to do after a bank says no, and why a broker can shop other lenders.
Turned down by a bank? Call or text (702) 766-3744 for a free file review.


What can go wrong with a Reno jumbo appraisal?
Comparable sales in Reno may need careful adjustment for location, site, view, quality, condition, amenities and market timing. Foothill and acreage homes add more questions: access, well and septic, wildfire exposure, outbuildings and land use.
- Many lenders want two appraisals at larger loan amounts, often around $1.5 million. They then use the lower value.
- A low value means more cash down, a price change or a different lender.
- Foothill and Mount Rose-area homes can cost more to insure. That raises your monthly escrow payment.
Read more: jumbo appraisal gaps in Reno and appraisal planning in Reno and Carson City.
What if I'm buying a Reno condo with a jumbo loan?
Reno housing includes downtown condominiums. For a condo, lenders review the project as well as you.
A project can be called non-warrantable when, for example: - a large share of units are investor-owned - a single entity owns too many units - the HOA is in litigation - the project has short-term rental or hotel-style operations - commercial space exceeds a set share
Non-warrantable doesn't mean unfinanceable. Portfolio and non-QM jumbo lenders can lend on many of these projects. Expect a larger down payment, more reserves and a full condo questionnaire from the HOA. Order the HOA questionnaire and budget early. A slow management company is a common reason a closing slips. See how to read Nevada HOA docs for a condo loan.
I'm moving from the Bay Area or elsewhere in California. What changes?
The limit drops. A loan that was conforming in California can be jumbo in Reno.
| County | 2026 one-unit limit |
|---|---|
| San Francisco, Santa Clara, Alameda, Los Angeles, Orange, CA | $1,249,125 |
| San Diego, CA | $1,104,000 |
| Ventura, CA | $1,035,000 |
| Sacramento, Riverside, San Bernardino, CA | $832,750 |
| Washoe County, NV (Reno) | $832,750 |
Buying before you sell. Common paths are a bridge loan, a HELOC on the California home, or qualifying with both payments. Which one fits depends on your equity, income and reserves, and it varies by lender.
Remote work. If your income changes with the move, document it clearly. A new remote-work setup is one example.
David's general approach with Californians moving to Nevada, in his words: "We evaluate proceeds from their previous home, reserves, employment continuation, and how best to structure the financing for the Nevada purchase."
iQRATE is licensed in Nevada and California, so one team can work both sides of the move. See a Reno or Incline Village loan with California income.
Can self-employed, retired or stock-paid buyers get a Reno jumbo?
Yes, if the income is documented the right way. David has worked in mortgages since 2005 and in tax preparation since 2008.
"A person can have extraordinary earning power without ever receiving a traditional paycheck. The challenge is making sure the lender understands the real financial picture rather than judging somebody's ability to repay based on their job title." (David Ghazaryan)
One example from his desk: "One of the most unusual clients I've worked with was a YouTube gamer buying a home in Henderson for approximately $3 million." That file was in Henderson, not Reno. David has also worked with a music producer and an Instagram influencer.
| Borrower | What lenders look at | Program options (vary by lender) |
|---|---|---|
| Business owners and creators | Ownership, cash flow, 1099s, personal and business bank statements | Full-doc, 12- or 24-month bank statements, 1099 or P&L |
| Retirees and high-net-worth buyers | Brokerage and vested retirement balances | Asset depletion, asset utilization |
| RSU and bonus earners | Which pay counts, and a history showing it is likely to continue | Full-doc jumbo; see use your portfolio for a Nevada jumbo |
| Uneven income with large assets | Reserves and liquidity | Interest-only jumbo, often with more down and more reserves |
As David puts it: "That doesn't mean we can count every dollar that enters the account. It means we need to understand which receipts represent eligible income and identify a lender whose documentation requirements fit the borrower." Non-QM programs usually need more down and more reserves. See non-QM loans, 1099 income averaging and S-corp salary too low in Reno.
Can I use a VA loan above $832,750 in Reno?
Often, yes. Veterans with full VA entitlement have no VA loan limit. Individual lenders may still cap the loan amount.
Reno veterans do use it. In 2025, 32 of 193 jumbo-size purchase loans in the Reno ZIP area were VA loans. In City of Reno tracts, it was 10 of 61.
VA funding fee basics (VA): - First use with $0 down: 2.15% of the loan. - Later use with $0 down: 3.3%. - First use with 5% down: 1.5%. - Veterans with a service-connected disability rating pay no funding fee.
Video: Don't Make This $9,000 VA Funding Fee Mistake. David Ghazaryan explains how the fee works, who is exempt, and how a small down payment can lower it.
Compare a VA option with a conventional jumbo before you choose. See VA loans and the VA loan limits page.
What about a duplex, triplex or fourplex in Reno?
The limit is higher for more units. The 2026 two-unit limit is $1,066,250. So a duplex loan up to that amount is conforming, not jumbo. That is $233,500 more than the one-unit limit. Three units go to $1,288,800 and four units to $1,601,750.
Two more facts: - Every City of Reno jumbo purchase loan in 2024 and 2025 was on a one-unit home. - About 8.6% of Reno homes are in 2-4 unit buildings (Census, 2024 survey).
Can I buy a Lake Tahoe or Incline Village second home with a jumbo loan?
Yes, but plan for more down. Incline Village (89451) is in Washoe County, but it is not in our Reno figures. There, 75 of 166 purchase loans in 2025 (45.2%) were jumbo.
- Second homes and investment property usually need more down than a primary home (varies by lender).
- Short-term rentals in unincorporated Washoe County need a county permit.
- Investment loans are for business purposes only.
See using home equity to buy a second home in Reno.
What do Washoe County taxes and fees cost near the jumbo line?
Transfer tax. Washoe County charges $2.05 per $500 of value. Who pays it is negotiated in the contract.
| Price | Washoe transfer tax | Same price in Clark County |
|---|---|---|
| $832,750 | $3,415 | $4,248 |
| $1,000,000 | $4,100 | $5,100 |
| $1,250,000 | $5,125 | $6,375 |
| $1,500,000 | $6,150 | $7,650 |
| $2,000,000 | $8,200 | $10,200 |
Recording fees. Washoe charges about $43 per document. Confirm the amount with the Washoe County Recorder.
Property tax. - The City of Reno district rate is about $3.66 per $100 of assessed value for FY 2026-27. Assessed value is 35% of taxable value. - That works out to about $1,281 a year per $100,000 of taxable value, before the cap. - Taxable value is often well below the sale price, so ask for the home's last tax bill. - After closing, file the Washoe County Assessor's claim. Your primary home then gets the 3% yearly cap. - Check the rate for your address with the Washoe County Treasurer.
Other costs. These lines appear on your Loan Estimate: - appraisal, or a second appraisal on larger loans - title insurance - escrow fee - discount points or lender credits - prepaid items - HOA transfer fees - broker compensation
See what is the true cash needed to close in Reno.

Can I refinance a Reno jumbo loan?
Yes. The same tiered lender rules apply. Four points matter most:
- The new loan amount decides. If you paid your balance down, or bring cash to the refinance, a new loan at or under $832,750 is conforming. That's true even if your first loan was a jumbo.
- Cash-out is stricter. Lenders usually allow a lower maximum LTV on a cash-out refinance than on a rate-and-term refinance.
- Your tax cap stays. A refinance that records no new ownership document does not affect your 3% property tax cap.
- ARM owners should plan early. About a third of 2025 Reno jumbo buyers chose ARMs. In City of Reno tracts, 15 of 21 jumbo ARMs had 7-year starts. Before the first adjustment, compare a new ARM, a fixed jumbo, and a conforming loan with a paydown.
See refinance options or call (702) 766-3744.
What documents do I need for a Reno jumbo loan?
| Document | W-2, RSU or bonus earner | Self-employed, full doc | Bank-statement jumbo | Asset-depletion or retiree | Relocating from California |
|---|---|---|---|---|---|
| Government ID | Yes | Yes | Yes | Yes | Yes |
| Pay stubs and two years of W-2s | Yes | If any W-2 income | No | No | Yes, if employed |
| RSU or bonus history showing it will likely continue | Yes, if used | If any | No | No | If used |
| Personal tax returns | Often 2 years | Usually 2 years | Usually not | Usually not | Yes, if full doc |
| Business tax returns | No | Usually 2 years | No | No | If self-employed |
| 12 or 24 months of bank statements | No | No | Yes | Statements for the qualifying assets | If using bank-statement income |
| Brokerage and retirement statements | For reserves | For reserves | For reserves | Yes, to calculate income | Yes |
| CPA letter or business license | No | Sometimes | Often | No | If self-employed |
| Current-home mortgage statement, sale contract or listing | If you own | If you own | If you own | If you own | Yes |
| Gift letter and donor statements | If gifted | If gifted | If gifted | If gifted | If gifted |
Requirements vary by lender. Explain large deposits before you apply. Reserves usually need about two months of statements. For a condo, add the HOA questionnaire and budget.
How does a Reno jumbo loan work, step by step?
- Call or text (702) 766-3744. The first call takes about 15 minutes. Tell us the price, the ZIP and how you earn. We check whether more down keeps you conforming.
- Send your documents. Use the checklist above. Gathering them before you shop is the best way to shorten the timeline.
- We compare lenders. We look at full-doc, bank-statement, asset-depletion and interest-only options, fixed or ARM. On complex files we shop more than 100 lenders.
- Get a written pre-approval. We review your documents first, so the letter holds up with sellers.
- Make your offer and apply. You get a Loan Estimate within 3 business days of applying.
- Order the appraisal right away. Larger loans may need two. Foothill and acreage homes get extra review. You get a copy promptly on completion or 3 business days before closing, whichever is earlier.
- Clear the conditions. The underwriter checks your reserves, deposits, income and title. For condos, the lender also reviews the project.
- Get clear to close. Your Closing Disclosure arrives at least 3 business days before you sign.
- Sign with Washoe County title and escrow. E-signing is available where the lender allows it. The transfer tax is collected when the deed is recorded.
- File your Assessor claim. This gets your primary home the 3% tax cap.
Who is iQRATE, and have you closed jumbo loans in Reno?
To be clear: iQRATE Mortgages is a Nevada brokerage based in Las Vegas, at 6360 S Rainbow Blvd Ste 101. We have no Reno office. We serve Reno remotely.
We have not closed a Reno or Washoe County jumbo file we can share. Our published jumbo case files are on our jumbo guide. Two of them: - a jumbo loan near $2 million on a Las Vegas home near $2.7 million, with 25% down, closed in about a month - a 15-year jumbo near $2.4 million on a Las Vegas home; its refinance a year later took about 12 days from submission to clear to close
Read them on our jumbo loan guide. Past results do not guarantee future outcomes.
Company NMLS 1862492. David Ghazaryan, NMLS 1486726. We are licensed in Nevada, California, Texas and Florida. Verify us on NMLS Consumer Access. Read more about David.
What do clients say about iQRATE Mortgages?
These are real 5-star reviews, quoted word for word. They describe our service overall. None is confirmed to be a jumbo loan or a Reno loan.

"Very efficient and transparent service. They go above and beyond to deliver the loan closure on time even in a very tight time line. Also very resourceful and knowledgeable staff. I'll go to them again next time I need a loan."
— Rita S. (Los Angeles, CA), 5-star review on Yelp.

"Well I've known David for many years. His office prepares my taxes. I had been putting off buying a home since I am a 1099 sales person. I thought mortgages were for wage earners. Never really thought I would qualify. They I mentioned to him in a conversation that I couldn't get a home, because of the type of income I have and all these reasons. In less than 10 minutes he had me qualified. Had to pay a couple of credit cards off, that was it, I own a home now. The only regret I have is not asking him sooner. This guy knows his numbers, taxes, rules and whatever else goes into that paperwork nightmare. Needless to say, I highly recommend him."
— garik 82 (Las Vegas, NV), 5-star review on Zillow.

"David was very professional and went above and beyond to make sure I understand the loan procedure. In addition, he went with me to my closing because I expressed that I would be more comfortable with him there to explain the documents to me. He was there and ensured a smooth transaction. Everything completed as expected. I would definitely recommend him to my friends and family."
— Jasmin (Las Vegas, NV), 5-star review on Zillow.

"David's experience in the greater Las Vegas area has been a tremendous help in every aspect of buying my home. His work is quick, efficient, and reliable."
— eddieyervinyan (Las Vegas, NV), 5-star review on Zillow.
Our ratings: Google 5.0 from 77 reviews, Yelp 5.0 from 51, Zillow 5.00 from 9, and David's Experience.com profile 5.0 from 87 (October 2026). Read all reviews.
Frequently asked questions
What is the jumbo loan limit in Reno for 2026?
It is $832,750 for a one-unit home in Washoe County, per FHFA. A loan above that is jumbo. The limits for 2, 3 and 4 units are $1,066,250, $1,288,800 and $1,601,750.
What home price makes a Reno loan jumbo?
It depends on your down payment. With 20% down, the line is $1,040,938. With 10% down it is $925,278, and with 25% down it is $1,110,333.
How much down payment do I need for a Reno jumbo loan?
Lenders often ask for 10-20%, and more on larger loans. In 2025, the median Reno jumbo loan was at 80% LTV, which means 20% down. Some buyers closed with less.
What credit score do I need for a jumbo loan in Reno?
Many jumbo lenders start around 700. Some set higher minimums for larger loans or smaller down payments. Rules vary by lender.
How much cash reserve do jumbo lenders want?
Commonly 6 to 12 months of the full housing payment, left over after closing. Larger loans, second homes and non-QM programs often need more. Gift funds and borrowed money usually don't count.
What debt-to-income ratio do jumbo lenders allow?
Commonly up to about 43%. Some lenders allow more with strong credit and reserves. In 2025, debt-to-income was the top reason Reno-area jumbo applications were denied.
Are jumbo rates higher than conforming rates?
It depends: each lender prices jumbo loans its own way and pricing changes daily. We don't post rates here. Compare official Loan Estimates line by line.
Do jumbo loans have PMI?
Most don't use standard private mortgage insurance. Lenders usually ask for more down instead. Some low-down-payment programs price the risk in other ways.
Can I get a jumbo loan in Reno if I'm self-employed?
Yes. Full-doc lenders use tax returns. Bank-statement, 1099, P&L and asset-depletion programs qualify you in other ways. Those programs usually need more down and more reserves.
Do I need two appraisals for a Reno jumbo loan?
Sometimes. Many lenders want two appraisals at larger loan amounts, often around $1.5 million. Foothill and acreage homes can raise extra appraisal questions.
How long does a Reno jumbo loan take to close?
It depends on the appraisal, the lender and how ready your documents are. Federal rules set two dates: the Loan Estimate within 3 business days of applying, and the Closing Disclosure at least 3 business days before you sign. Our published Las Vegas jumbo files ranged from about 12 days from submission to clear to close (a refinance) to about ten weeks from application (a large purchase). Past results do not guarantee future outcomes.
Can I use a VA loan above $832,750 in Reno?
Often, yes. Veterans with full entitlement have no VA loan limit, though some lenders set their own caps. In 2025, 32 of 193 jumbo-size purchase loans in the Reno ZIP area were VA loans.
Why are so few jumbo loans inside Reno city limits?
Most Reno-area jumbo loans are made just outside city limits. Only 61 of Washoe's 327 jumbo purchase loans in 2025 were in City of Reno tracts. In 89511, the tracts whose internal point is inside the city had none.
Can I refinance my jumbo into a conforming loan?
Often, if the new loan is $832,750 or less on a one-unit home, subject to qualifying. Paying down the balance, or bringing cash to closing, can get you there.
Can I use a jumbo loan for a Lake Tahoe second home or a rental?
Yes, with more down. Second homes and investment property usually need more equity than a primary home. Short-term rentals in unincorporated Washoe County need a county permit.
Is there a high-balance conforming loan in Reno?
No. No Nevada county is a high-cost area in 2026. In Washoe, any one-unit loan above $832,750 is a jumbo.
How common are jumbo loans in 89511?
Very common. In 2025, 96 of 283 purchase loans in 89511 (South Reno, Galena, ArrowCreek) were jumbo. That is 33.9%, or about 1 in 3. In 2024 it was 84 of 257.
How many jumbo loans are made in Incline Village?
In 2025, 75 of 166 purchase loans in Incline Village (89451) were jumbo, or 45.2%. Incline Village is in Washoe County, but it is not in our Reno figures.
What is the median jumbo loan in Reno?
In 2025 it was $955,000 in City of Reno tracts. Across Reno-address ZIPs it was $1,135,000, up $120,000 from 2024. The median home value in the ZIP area was $1,515,000.
How many lenders make jumbo loans in Reno?
In 2025, 65 different lenders made jumbo purchase loans in the Reno ZIP area. In City of Reno tracts it was 33. Each one sets its own rules, so shopping your file matters.
What is the transfer tax on a $1,000,000 Reno home?
It is $4,100. Washoe County charges $2.05 per $500 of value. The same sale in Clark County would cost $5,100. The contract decides who pays.
What is the 2026 duplex limit in Reno?
It is $1,066,250 for a two-unit home. That is $233,500 above the one-unit limit. A duplex loan up to that amount is conforming.
How much do I need down to stay conforming on a $1,000,000 home?
You need $167,250 down, or 16.7% of the price. That keeps the loan at $832,750. With 10% down, the loan is $900,000, which is jumbo.
Why do Reno jumbo applications get denied?
Debt-to-income is the top reason. It was the main reason in 21 of 46 denied jumbo applications in the Reno ZIP area in 2025. Next came "other" (9) and collateral, meaning the appraisal or property (6).
Do Reno jumbo buyers choose ARMs or fixed rates?
Most choose fixed. About a third chose an ARM in 2025: 34.4% in City of Reno tracts and 34.2% in the ZIP area. In the city, 15 of the 21 ARMs had a 7-year fixed start.
Can I get an interest-only jumbo loan in Reno?
Some lenders offer it. In 2025, 3 City of Reno jumbo loans and 14 in the Reno ZIP area had interest-only payments. Lenders usually ask for more down and more reserves.
Which other iQRATE pages help Reno jumbo buyers?
- Jumbo loan guide: full program details and our closed files.
- Reno mortgage broker: Washoe denials, FHA, down payment help and property tax.
- Las Vegas jumbo loans, Henderson jumbo loans and North Las Vegas jumbo loans.
- Sparks mortgage broker.
- Bank statement loans, asset depletion loans and non-QM loans.
- Reno mortgage guide for under 2 years self-employed.
- Mortgage calculators.
Where can I read more about Reno and Nevada jumbo loans?
These are our own guides. Each link opens a page on this site.
Which Nevada city pages should I compare?
- Reno mortgage broker (Washoe loan limits, taxes, market data).
- Sparks mortgage broker.
- Carson city mortgage broker.
- Las Vegas jumbo loans (city loan data).
- Henderson jumbo loans (city loan data).
- North Las Vegas jumbo loans (city loan data).
- Nevada mortgage broker.
- Las Vegas mortgage broker.
- Henderson mortgage broker.
- Summerlin mortgage broker.
Which iQRATE loan program pages fit a buyer near the jumbo line?
- Jumbo loans in Nevada.
- Bank statement loans.
- Non-QM loans.
- Asset depletion loans in Nevada.
- DSCR loans.
- Investor loans.
- VA loans.
- Mortgage calculators.
- Client reviews.
- Apply now.
- Contact us.
- Rates and how we quote.
- Our written guarantees.
Which Reno and Northern Nevada guides should I read?
- A guide to Las Vegas & Reno rental portfolio blanket loans.
- Best loan to buy a Reno BRRRR property in Nevada.
- Bypass mortgage seasoning rules in Las Vegas & Reno.
- Co signed loan blocking your Reno mortgage heres the fix.
- Combining gig income for a Reno & Sparks mortgage.
- Consolidate Reno rentals with a DSCR portfolio loan.
- DSCR loan approval for older Reno & Sparks rental homes.
- DSCR loan calculation for Las Vegas & Reno investors.
- DSCR loans for vacant rentals in Reno & Las Vegas.
- FHA appraisal repairs in Reno what to do next.
- FHA loan for a Reno home with unpermitted additions.
- FHA repair checklist for Reno & Carson City Nevada homes.
- FHA repairs for older homes in Reno Nevada.
- FHA vs conventional loan in Reno build equity faster.
- Financing a Reno mobile home park with a DSCR loan.
- Financing your 11th rental in Reno and Sparks Nevada.
- First Reno investment property a strategic mortgage guide.
- Get a mortgage in Henderson & Reno with a thin credit file.
- Get a Reno & Incline Village loan with California income.
- How lenders average 1099 income in Las Vegas & Reno.
- How lenders combine 1099 incomes in Las Vegas & Reno.
- How Reno underwriters view your medical debt for a mortgage.
- How student loans affect a mortgage in Reno Nevada.
- Is FHA mortgage insurance in Reno Nevada a waste of money.
- Loan options after 10 properties in Las Vegas & Reno Nevada.
- Low credit score how to buy a home in Reno & Las Vegas.
- My Reno home failed the FHA appraisal what now.
- Navigating jumbo loan appraisal gaps in Reno Nevada.
- Nevada DSCR loans for Reno & Las Vegas gig workers.
- Nevada foreign investor portfolio loan Reno & Las Vegas.
- Piggyback vs jumbo loan in Reno Nevada a cost guide.
- Portfolio loan risks in Reno and Carson City Nevada.
- Prep your Las Vegas & Reno business for a mortgage.
- Reno & Sparks DSCR loan guide for fixer uppers.
- Reno & Sparks FHA mip vs conventional pmi explained.
- Reno down payment assistance a good deal or a costly trap.
- Reno mortgage guide with less than 2 years self employed.
- S corp salary too low for a mortgage in Reno Nevada.
- Simplify Reno & Las Vegas rentals with one portfolio loan.
- Systematizing appraisal success in Reno and Carson City.
- Unpermitted adu rent for a Reno DSCR loan does it count.
- Use Reno rental equity to buy another Nevada property.
- Using gift funds for closing costs in Reno Nevada.
- Using home equity to buy a second home in Reno Nevada.
- Using part time income for a VA loan in Reno Nevada.
- Vet buyer financing in Reno and Carson City like a pro.
- What is payment shock and how to beat it in Reno Nevada.
- What is the true cash needed to close in Reno Nevada.
- Why is my Reno cash to close higher than estimated.
Which Nevada jumbo, self-employed and high-income guides help?
- A guide to California jumbo Renovation loans.
- A Nevada S-Corp guide to mortgage qualification.
- Bank statements vs tax returns for a Las Vegas mortgage.
- California investors buying Las Vegas rentals with a DSCR loan.
- California to Las Vegas jumbo loan before selling your home.
- Foreign national jumbo loans in Nevada a guide.
- Henderson jumbo loans macdonald highlands ascaya lake Las Vegas.
- How Nevada lenders calculate overtime & bonus income.
- Jumbo loans for a home in a trust in Las Vegas Nevada.
- Jumbo vs high balance loans in Nevada which is best.
- Jumbo vs piggyback loan in Las Vegas & Henderson Nevada.
- Las Vegas high rise condo jumbo loans and warrantability.
- Las Vegas jumbo loan down payment and reserves 2026.
- Las Vegas jumbo loans for new construction and custom homes.
- Nevada mortgage after business change a self employed guide.
- Prep S-Corp taxes for Las Vegas jumbo loan approval.
- Qualify for a Las Vegas jumbo loan with no W-2s.
- Qualify for a Las Vegas mortgage as an S-Corp owner.
- S corp mortgage guide for business owners in Nevada.
- S corp mortgage in Nevada get approved after a business change.
- S corp switch & your Nevada mortgage how to get approved.
- Use your portfolio for a Nevada jumbo loan in 2026.
- Using S-Corp income for a mortgage in Nevada.
- When to apply for a self employed mortgage in Nevada.
Which Nevada guides cover reserves, appraisals, credit, gifts and refinancing?
- Avoid closing costs on a Nevada home 2026 guide.
- Buying a home from a trust in Las Vegas a guide.
- Can a non relative gift my down payment in Nevada.
- Cash from a Nevada rental with a DSCR refinance.
- Clark county property tax and transfer tax on a Las Vegas DSCR rental.
- DSCR cash out refinance to scale a Las Vegas rental portfolio.
- DSCR loan reserve rules in Las Vegas Nevada explained.
- DSCR loan reserves in Las Vegas Nevada a guide for investors.
- Get a Las Vegas mortgage with no credit score in Nevada.
- Get a mortgage on a home in a trust in Nevada.
- How to refinance in Nevada to buy out your spouse.
- How to speed up your Las Vegas DSCR loan refinance.
- How to use a gift of equity in Nevada for a mortgage.
- Mortgage recast vs refinance in Nevada which saves more.
- Nevada 1099 mortgage guide for gig worker income.
- Nevada HELOC vs cash out refinance fund your next home.
- Nevada non recurring closing costs explained for homebuyers.
- Protect your credit score during escrow in Las Vegas Nevada.
- Summerlin jumbo loans for guard gated and golf course homes.
- Systematize appraisals for success in Las Vegas Nevada.
- Tap Nevada rental equity without a cash out refinance.
- VA cash out refinance vs HELOC in Nevada a 2024 guide.
- What is a rate and term refinance in Las Vegas Nevada.
- What to do after a failed VA appraisal in Nevada.
Which other Nevada home loan guides might help?
- 2025 guide Nevada DSCR investor loans.
- A DSCR loan for a Las Vegas non warrantable condo guide.
- A foreign buyers guide to Nevada rental property loans.
- A guide to buying a Las Vegas home anonymously.
- A guide to de risking new construction loans in Nevada.
- A letter of explanation can save your Las Vegas mortgage.
- Are mortgage points a waste of money in Nevada.
- Authorized user accounts & your Nevada mortgage approval.
- Best loan for a multi gen home in Las Vegas Nevada.
- Best property type for a DSCR loan in Nevada.
- Beyond 10 mortgages in Nevada a guide for investors.
- Buy a Las Vegas home before you sell your current one.
- Buy a Las Vegas rental after foreclosure sooner than you think.
- Buying a Las Vegas rental with an itin investor loan.
- Can a lender revoke a mortgage commitment in Nevada.
- Can DSCR loans use casita rent in Las Vegas Nevada.
- Credit dispute halting your Las Vegas Nevada mortgage.
- Credit mistakes that kill a mortgage in Las Vegas Nevada.
- Deed in lieu and your next mortgage in Nevada.
- Dpa vs seller credits for a Las Vegas Nevada home loan.
- DSCR loan for a Las Vegas house hack a smart guide.
- DSCR loan guide for fixer upper rentals in Nevada.
- DSCR loan guide for mid term rentals in Nevada.
- DSCR loan in Las Vegas & Henderson with no lease.
- DSCR loans and high hoas in Las Vegas and Henderson.
- DSCR loans and hoa rules in Nevada a lenders guide.
- DSCR loans finance a Las Vegas condo hotel unit.
- DSCR loans for Las Vegas condo hotels your guide.
- DSCR loans for Las Vegas short term rentals explained.
- DSCR loans for new construction rentals in Las Vegas.
- DSCR Renovation loans for fixer uppers in Reno Nevada.
- DSCR vs blanket loans a guide for Nevada investors.
- Finance 5 Nevada rentals with one blanket mortgage loan.
- Financing 5 unit rentals in Las Vegas Nevada a guide.
- Financing a 5 unit property in Las Vegas Nevada.
- Financing a Las Vegas condo hotel with a DSCR loan.
- Financing a Nevada fix and flip a complete guide.
- Financing past 10 mortgages in Las Vegas Nevada.
- First time homebuyer in Las Vegas.
- Fix a credit error during your Las Vegas mortgage escrow.
- Fix a credit report error during escrow in Las Vegas.
- Fix credit report errors during a Las Vegas escrow.
- Get a DSCR loan in Nevada with no rent roll.
- Get a Las Vegas mortgage after a bad business year.
- Get a mortgage in Las Vegas Nevada with no fico score.
- Get a Nevada mortgage with a business loss.
- Getting a mortgage in Nevada with cannabis income.
- Good credit but denied a Las Vegas Nevada mortgage why.
- Good credit denied mortgage in Las Vegas heres why.
- Guide to DSCR Renovation loans in Las Vegas Nevada.
- Guide to foreign national loans in Nevada.
- Henderson and north Las Vegas DSCR loans for single family rentals.
- How appraisers calculate rent for a Las Vegas DSCR loan.
- How co borrower debt can block your Henderson home loan.
- How hoa rules block DSCR loans in Las Vegas Nevada.
- How lenders calculate gig worker income in Nevada.
- How lenders project rent for Las Vegas DSCR loans.
- How lenders verify tip income for a mortgage in Nevada.
- How much cash do you need to close on a Nevada home.
- How payment shock can derail your Nevada mortgage loan.
- How to buy a Nevada home with limited credit history.
- How to buy more rentals in Nevada with a portfolio loan.
- How to get a Las Vegas mortgage after quitting your w 2 job.
- How to get a mortgage on a tax extension in Nevada.
- How to prove your Henderson financed offer is a sure thing.
- How to read Nevada hoa docs for a condo loan.
- How to rescue a failing escrow in Las Vegas Nevada.
- How to stress test a DSCR loan in Nevada.
- How to use airdna for a DSCR loan in Nevada in 2025.
- How your mortgage escrow account works in Nevada.
- Investor loan in Las Vegas Nevada after bankruptcy a guide.
- Las Vegas dpa a good deal or a costly trap for buyers.
- Las Vegas duplex triplex and fourplex DSCR loans.
- Las Vegas lender credits vs seller credits which is better.
- Las Vegas mortgage for new businesses how soon can you buy.
- Las Vegas short term rental DSCR loans city rules 2026.
- Loan denied after clear to close in Nevada heres why.
- Making your financed offer win in Las Vegas Nevada.
- Medical debt and your 2026 Nevada mortgage approval.
- Mortgage points vs rate buydown in Las Vegas Nevada.
- Mortgage shopping in Las Vegas will it hurt your credit.
- Nevada BRRRR bypass seasoning with a DSCR loan.
- Nevada business taxes and your home mortgage qualification.
- Nevada condo hotel financing a guide to DSCR loans.
- Nevada dpa grant vs forgivable loan for homebuyers.
- Nevada DSCR vs conventional loan which is better.
- Nevada foreign national loan documents you need.
- Nevada itin vs foreign national loan a direct comparison.
- Nevada mortgage guide for thin credit files.
- Nevada portfolio loans for foreign investors guide.
- Nevada portfolio loans for your rental properties.
- Nevada rentals blanket loan vs multiple investor loans.
- Nevada sid and lid fees explained for homebuyers.
- New collection in escrow in Nevada how to save your loan.
- Old vs new debt what hurts a Las Vegas mortgage most.
- One time close construction loans in Nevada explained.
- Parents credit wrecked my Las Vegas mortgage heres a fix.
- Portfolio loans for Las Vegas BRRRR real estate investing.
- Portfolio loans for Nevada rentals a Las Vegas guide.
- Portfolio vs DSCR loans in Nevada for rental growth.
- Qualify for a DSCR loan with casita rent in Las Vegas.
- Qualifying for a Nevada mortgage with a spousal salary.
- Rapid rescore guide for mortgages in Nevada.
- Rate buydown or more down in Nevada which saves more.
- Real risks of a co signed mortgage in Nevada.
- Renovation loans.
- Restore VA loan entitlement after divorce in Las Vegas.
- Secure top offers de risk your Las Vegas home sale.
- Should you recast your mortgage in Nevada a guide.
- Tax extension for a Nevada mortgage a strategic guide.
- Thin credit mortgage in Las Vegas & Henderson Nevada guide.
- Unmarried homebuyers guide for Nevada.
- Use home equity to buy a rental property in Nevada.
- Use rental history for a Las Vegas mortgage in Nevada.
- Using a 401k loan for a down payment in Nevada.
- Using a construction loan to build a home in Nevada.
- Using a DSCR loan for a seasonal Las Vegas rental.
- Using a power of attorney for a Nevada mortgage closing.
- Using a VA loan to buy a Las Vegas condo in Nevada.
- Using an energy efficient mortgage in Nevada explained.
- Using casita income for a Nevada DSCR loan approval.
- Using foreign funds for a Nevada mortgage a guide.
- Using lender credits on a Nevada mortgage.
- Using seller credits in Las Vegas to win your offer.
- VA condo approval in Las Vegas and Henderson Nevada.
- VA loan with low credit in Las Vegas its possible.
- Waive a loan contingency in Nevada a cash offer guide.
- What is a cross collateral loan in Nevada for rentals.
- What is a seller bridge solution in Las Vegas Nevada.
- What is the buyer power index in Las Vegas Nevada.
- When to lock a mortgage rate in Las Vegas Nevada.
- Why a DSCR loan protects your next loan in Las Vegas.
- Why did my Nevada mortgage payment go up escrow explained.
- Why Las Vegas Nevada homeowners insurance is so high.
- Why your good credit gets denied for a Las Vegas mortgage.
- Why your Las Vegas mortgage payment increased.
- Why your mortgage score in Nevada is lower than you think.
- Will my unique Las Vegas property get a DSCR loan in Nevada.
- Will paying collections hurt my Las Vegas mortgage score.
- Your cpa mortgage guide for Las Vegas & Henderson homebuyers.
- Your first DSCR loan guide for Las Vegas Nevada.
- Zoning risk the hidden DSCR loan killer in Las Vegas Nevada.
Sources
- FHFA, conforming loan limits for 2026 and the full county file.
- FFIEC HMDA Data Browser: Washoe County loan-level data for 2024 and 2025. Analysis by iQRATE on November 5, 2026.
- CFPB, about HMDA data.
- CFPB, Loan Estimate and Closing Disclosure timing (12 CFR 1026.19) and appraisal copies (12 CFR 1002.14).
- Census TIGERweb: 2020 incorporated places and census tracts.
- Census Bureau, American Community Survey.
- Nevada Department of Taxation, real property transfer tax.
- Washoe County: Recorder, Assessor and Treasurer tax rates.
- NRS 361.4723, the 3% property tax cap.
- VA loan limits and VA funding fee.
- Nevada Real Estate Group, NNRMLS Reno data.
Talk to David about your Reno jumbo loan
Call or text (702) 766-3744. Tell David the price, the ZIP and how you earn. He will tell you whether you can stay conforming, and which documents to gather. When you're ready, apply now or contact us.
By David Ghazaryan, NMLS 1486726, iQRATE Mortgages (NMLS 1862492). Updated November 5, 2026.
iQRATE Mortgages LLC (NMLS 1862492), 6360 S Rainbow Blvd Ste 101, Las Vegas, NV 89118. David Ghazaryan, Mortgage Broker, NMLS 1486726.
iQRATE is a mortgage broker, not a lender, and does not make credit decisions. Broker compensation is disclosed on your Loan Estimate and Closing Disclosure.
This page is general information. It is not a loan offer, and it isnot a commitment to lend. All loans are subject to credit, property and underwriting approval. Rates, terms, down payment, reserve and credit requirements vary by lender and change daily. Not all borrowers will qualify. No rate or APR is shown.
Dollar figures are simple arithmetic from public limits and tax rates. HMDA figures are iQRATE's analysis of public data and describe past loans, not your loan. Investor loans are for business purposes only. Tax information is not tax advice.
Equal Housing Opportunity. Verify licensing at nmlsconsumeraccess.org.