By David Ghazaryan, NMLS 1486726, iQRATE Mortgages (NMLS 1862492) Updated November 5, 2026.
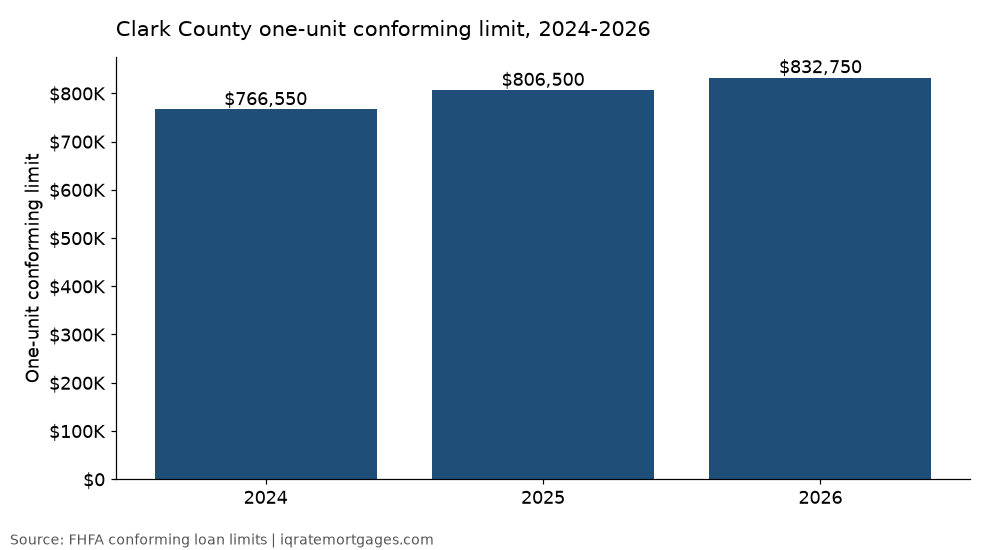
Short answer: North Las Vegas is in Clark County. The 2026 one-unit conforming limit there is $832,750 (FHFA). A loan above that amount is a jumbo loan. Very few buyers here cross the line: in 2025, just 14 of 3,598 city home purchase loans were above that year's $806,500 limit.
If your price is near the line, you have more options than you may think. A bit more down can keep you conforming. A VA loan can go above $832,750. A duplex has a higher limit. Call or text (702) 766-3744 and we'll run the numbers with you.
Key facts: North Las Vegas jumbo loans (2026)
- Jumbo line, one unit: a loan above $832,750 (FHFA 2026, Clark County).
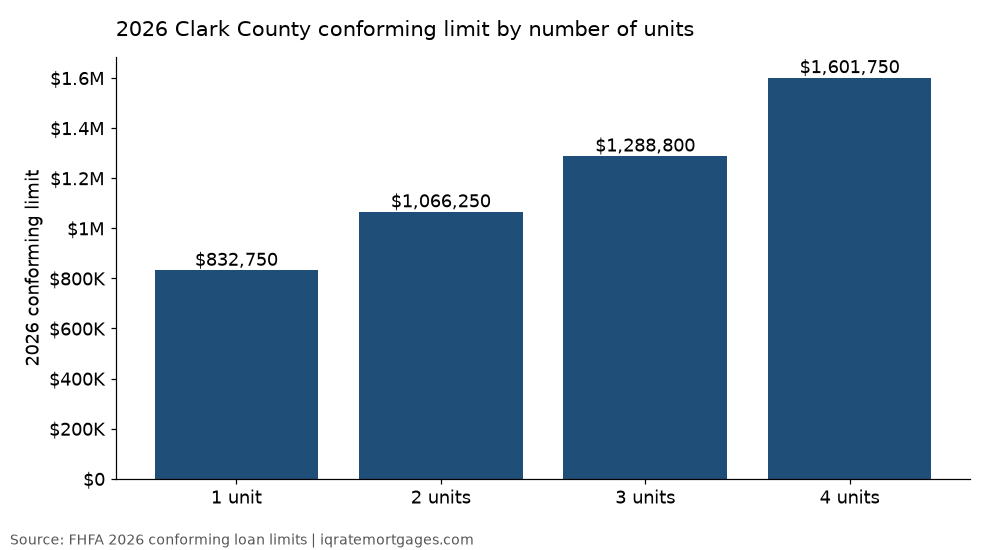
- Jumbo line, two units: a loan above $1,066,250.
- How rare jumbo is here: 0.4% of city purchase loans in 2025, vs 4.0% across Clark County (iQRATE HMDA analysis).
- Who used them: 11 of the 14 jumbo loans in 2025 were VA loans. All 14 were for primary homes.
- Where: all 17 jumbo purchase loans in 2024-2025 were in ZIPs 89084 and 89031.
- How big: every one was under $1,000,000.
- Denials: 8 of 24 decided jumbo applications were denied in 2025 (33.3%). The conforming denial rate was 15.4%.
- No high-balance tier: Clark County is not a high-cost area, so any one-unit loan above $832,750 is jumbo.
- iQRATE Mortgages is a broker, not a lender. Company NMLS 1862492; David Ghazaryan NMLS 1486726.
What are the 2026 loan limits in North Las Vegas?
The limit applies to the loan amount, not the price. The jumbo line rises with the number of units.
| Property | Conforming limit (jumbo above this) | FHA limit |
|---|---|---|
| 1 unit | $832,750 | $541,287 |
| 2 units | $1,066,250 | $693,050 |
| 3 units | $1,288,800 | $837,700 |
| 4 units | $1,601,750 | $1,041,125 |
Sources: FHFA 2026 conforming loan limits; HUD Mortgagee Letter 2025-23.
For context, the city's median sold price was about $415,000 in mid-2026 (Nevada Real Estate Group, GLVAR MLS data). Zillow's typical value in the highest-priced city ZIP, 89085, was $500,633 in September 2026. A jumbo-size home here is far from typical.
How many North Las Vegas buyers actually use jumbo loans?
Almost none. We pulled public loan records to show it.
How we counted. * Source: we used public HMDA loan-level files for Clark County from the FFIEC HMDA Data Browser, for 2024 and 2025. * Area: we kept the 59 census tracts whose center point sits inside North Las Vegas city limits. Those tracts hold 97.3% of the city's 2020 residents. * What counts as jumbo: a loan flagged above the limit in force that year. That was $766,550 in 2024 and $806,500 in 2025. * Which loans: originated, first-lien home purchase loans. * Excluded: unincorporated areas with a North Las Vegas mailing address. * Limits of the data: HMDA counts loans, not cash sales. It reports amounts in $10,000 bands. The counts are small, so read them as counts, not trends.
| Area | 2024 purchase loans | 2024 jumbo | 2024 share | 2025 purchase loans | 2025 jumbo | 2025 share |
|---|---|---|---|---|---|---|
| North Las Vegas city | 3,967 | 3 | 0.1% | 3,598 | 14 | 0.4% |
| Las Vegas city | 6,867 | 207 | 3.0% | 6,154 | 190 | 3.1% |
| Henderson city | 5,626 | 255 | 4.5% | 5,195 | 218 | 4.2% |
| Clark County | 29,562 | 1,009 | 3.4% | 26,769 | 1,082 | 4.0% |
Clark County's jumbo share was about 10 times the city's in 2025. The city's 14 jumbo loans were 1.3% of all 1,082 in the county. For neighbor detail, see Las Vegas jumbo loans: city data and Henderson jumbo loans: city data.


Who got jumbo loans in North Las Vegas in 2024 and 2025?
The typical local jumbo borrower was a VA borrower buying a home to live in, with no money down. That is very different from the valley-wide picture.
| Measure | 2024 | 2025 |
|---|---|---|
| Jumbo purchase loans | 3 | 14 |
| Median jumbo loan amount | $775,000 | $860,000 |
| Median value of the home bought | $775,000 | $900,000 |
| Smallest to largest jumbo loan (band midpoints) | $775,000 to $795,000 | $805,000 to $935,000 |
| Highest home value on a jumbo loan | $795,000 | $1,055,000 |
| Median loan-to-value | 100% | 100% |
| Loans at 100% LTV (where LTV was reported) | 2 of 2 | 8 of 11 |
| Median reported borrower income | $179,000 | $214,500 |
| Total jumbo purchase volume | $2,345,000 | $12,100,000 |
| VA loans | 3 of 3 | 11 of 14 |
| Conventional jumbo loans | 0 of 3 | 3 of 14 |
| Primary residence | 3 of 3 | 14 of 14 |
| Adjustable-rate | 0 | 1 |
| Interest-only | 0 | 1 |
| 30-year term | 3 | 13 |
| Different lenders making these loans | 3 | 7 |
What this tells you: * VA leads. 14 of the 17 jumbo loans over two years were VA (82.4%). * The loans sit close to the line. The median 2025 jumbo loan, $860,000, was just $27,250 over the 2026 limit. * The limit went up. 5 of the 14 jumbo loans in 2025 had band midpoints at or under $832,750, so a loan that size would be conforming in 2026. HMDA bands are $10,000 wide, so this is approximate. * 2024's loans would likely not be jumbo now. All three (approximately $775,000 to $795,000, HMDA band midpoints) are below today's limit.
Where did North Las Vegas jumbo loans close?
| ZIP | Purchase loans 2024-2025 | Jumbo loans 2024-2025 | Jumbo 2024 | Jumbo 2025 |
|---|---|---|---|---|
| 89084 | 3,041 | 10 | 3 | 7 |
| 89031 | 1,649 | 7 | 0 | 7 |
| 89081 | 1,087 | 0 | 0 | 0 |
| 89032 | 793 | 0 | 0 | 0 |
| 89030 | 520 | 0 | 0 | 0 |
| 89086 | 397 | 0 | 0 | 0 |
| 89115 | 78 | 0 | 0 | 0 |
All 17 were in two ZIPs. The busiest single census tract, in 89084, had 8 of its 1,346 purchase loans above the limit. Our North Las Vegas mortgage broker guide lists 89084 as Aliante and the northwest, and 89031 as central North Las Vegas and Eldorado.
We do not steer buyers to or away from any area. Where you buy is your choice. Every loan is underwritten on the same rules wherever the home is.


Are more North Las Vegas buyers getting close to the limit?
Yes, though the counts are small. Jumbo loans are still rare. The clearest sign is home value: purchase loans on homes valued at $800,000 or more rose from 8 to 44.
| Loan amount | 2024 | 2025 |
|---|---|---|
| Under $300,000 | 707 | 598 |
| $300,000 to under $400,000 | 1,661 | 1,483 |
| $400,000 to under $500,000 | 1,238 | 1,085 |
| $500,000 to under $600,000 | 272 | 298 |
| $600,000 to under $700,000 | 70 | 72 |
| $700,000 and up, within the conforming limit | 16 | 48 |
| Above the conforming limit (jumbo) | 3 | 14 |
| Home value | 2024 | 2025 |
|---|---|---|
| Under $400,000 | 1,657 | 1,486 |
| $400,000 to under $500,000 | 1,637 | 1,422 |
| $500,000 to under $600,000 | 416 | 414 |
| $600,000 to under $800,000 | 226 | 209 |
| $800,000 to under $1,000,000 | 7 | 40 |
| $1,000,000 or more | 1 | 4 |
What the tables show: * Purchase loans on homes valued at $800,000 or more rose from 8 to 44. * Loans of $700,000 or more that stayed conforming rose from 16 to 48. Part of that jump is the line moving: the limit was $766,550 in 2024 and $806,500 in 2025, so that band was wider in 2025. * The median loan on all city purchases stayed at $385,000 both years.
So the near-limit buyer is a small but real group. That group gets the most from planning.


Why do North Las Vegas jumbo applications get denied?
Jumbo applications here were denied at 33.3% vs 15.4% for conforming ones in 2025. The counts are small, so treat this as a warning sign, not a rule.
| Year | Decided jumbo | Denied | Jumbo denial rate | Decided conforming | Denied | Conforming denial rate |
|---|---|---|---|---|---|---|
| 2024 | 5 | 1 | 20.0% | 6,296 | 955 | 15.2% |
| 2025 | 24 | 8 | 33.3% | 6,359 | 977 | 15.4% |
| Reason | Denials |
|---|---|
| Collateral (appraisal or property) | 3 |
| Debt-to-income ratio | 3 |
| Other | 1 |
| Unverifiable information | 1 |
Why collateral matters here: an appraiser needs nearby sales of similar homes. Financed sales at this price were rare (44 in 2025), and comparable sales may be limited. We check the property before you write an offer.
Why DTI matters here: several local costs count in your payment: * The city tax rate is among the higher ones in Clark County. * Some newer northern subdivisions carry SID assessments. * Many homes have master and sub-association HOA dues.
All of these land in your debt-to-income ratio. We put them in your numbers on day one. If you were denied elsewhere, I start by finding out exactly why. Collateral, income math, reserves and DTI are very different problems with different fixes.


Can I avoid a jumbo loan in North Las Vegas with a bit more down?
Often, yes. The line depends on your loan, not your price. Divide $832,750 by the share you finance to find the highest price that keeps a one-unit loan conforming.
| Down payment | Max loan-to-value | Highest conforming price |
|---|---|---|
| 3% | 97% | $858,505 |
| 5% | 95% | $876,579 |
| 10% | 90% | $925,278 |
| 15% | 85% | $979,706 |
| 20% | 80% | $1,040,938 |
| 25% | 75% | $1,110,333 |
| 30% | 70% | $1,189,643 |
3% down is only for eligible buyers and programs.
Conforming or jumbo? Your loan at common prices
| Price | 5% down | 10% down | 20% down | 25% down |
|---|---|---|---|---|
| $850,000 | $807,500: $25,250 under (conforming) | $765,000: $67,750 under (conforming) | $680,000: $152,750 under (conforming) | $637,500: $195,250 under (conforming) |
| $900,000 | $855,000: $22,250 over (jumbo) | $810,000: $22,750 under (conforming) | $720,000: $112,750 under (conforming) | $675,000: $157,750 under (conforming) |
| $950,000 | $902,500: $69,750 over (jumbo) | $855,000: $22,250 over (jumbo) | $760,000: $72,750 under (conforming) | $712,500: $120,250 under (conforming) |
| $1,000,000 | $950,000: $117,250 over (jumbo) | $900,000: $67,250 over (jumbo) | $800,000: $32,750 under (conforming) | $750,000: $82,750 under (conforming) |
| $1,100,000 | $1,045,000: $212,250 over (jumbo) | $990,000: $157,250 over (jumbo) | $880,000: $47,250 over (jumbo) | $825,000: $7,750 under (conforming) |
| $1,250,000 | $1,187,500: $354,750 over (jumbo) | $1,125,000: $292,250 over (jumbo) | $1,000,000: $167,250 over (jumbo) | $937,500: $104,750 over (jumbo) |
How to read it: * $900,000 home: 5% down ($45,000) gives a jumbo loan. 10% down ($90,000) keeps you conforming. * $1,000,000 home: you need 20% down ($200,000) to stay under the line. * $950,000 home: this sits under the 15%-down line of $979,706.
Trade-offs to weigh: * Conforming loans need mortgage insurance above 80% loan-to-value. Jumbo loans usually don't, and price that risk into the down payment and terms instead. * Some buyers pair a conforming first loan with a second lien. See jumbo vs piggyback in Las Vegas and Henderson. * Which path costs less depends on your credit, reserves, how long you'll keep the loan and that day's pricing. We lay out cash to close and fees for each option on Loan Estimates.
Near the line? Send us your price and your cash. We'll run conforming, jumbo and VA side by side. Call or text (702) 766-3744.


Can I use a VA loan above $832,750 near Nellis?
Often, yes. Veterans with full VA entitlement have no VA loan limit. That helps explain why most local jumbo loans were VA. In 2025, 11 of 14 were VA. Of the 11 jumbo loans in 2025 with a reported LTV, 8 were at 100%. VA is common here in general: it made up 25.0% of city purchase loans in 2025, vs 13.0% countywide.
| Year | City VA purchase loans | Share of city purchase loans | Clark County VA purchase loans | Share of county purchase loans | County VA loans above the conforming limit |
|---|---|---|---|---|---|
| 2024 | 863 | 21.8% | 3,443 | 11.6% | 146 |
| 2025 | 899 | 25.0% | 3,483 | 13.0% | 141 |
Points to check before you shop above the line: * Entitlement. If you already have a VA loan open, your limit may be tied to the $832,750 conforming figure. Whether you need a down payment then depends on your remaining entitlement. Bring your Certificate of Eligibility and we'll check it. See VA loan limits on VA.gov and restoring VA entitlement. * Lender caps. VA sets no limit with full entitlement, but individual lenders may set their own maximum loan amounts. As a broker, we compare several VA lenders. * The appraisal. A VA appraisal also checks minimum property standards. Comparable sales for high-priced homes here may be limited. See what to do after a failed VA appraisal. * The funding fee. It replaces monthly mortgage insurance and can be financed. Veterans who get VA disability compensation are usually exempt.
| Price | Loan at 0% down | vs $832,750 |
|---|---|---|
| $850,000 | $850,000 | $17,250 over |
| $900,000 | $900,000 | $67,250 over |
| $950,000 | $950,000 | $117,250 over |
| $1,000,000 | $1,000,000 | $167,250 over |
With full entitlement, being "over" doesn't block a VA loan. It does mean a conventional loan at the same price would be jumbo.
| Down payment | First use | After first use |
|---|---|---|
| Less than 5% | 2.15% | 3.3% |
| 5% or more | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
Video: Don't Make This $9,000 VA Funding Fee Mistake. I explain how the fee works, who is exempt and how a small down payment can lower the fee on a later VA loan.
Our VA track record: from 2019 through 2023 we closed 13 VA loans. Most were in Las Vegas, North Las Vegas and Henderson. They ranged from about $280,000 to about $625,000: 8 purchases and 5 refinances. None of them were jumbo-size. Past results do not guarantee future outcomes. See our VA loans page.

What if I'm buying a duplex to fourplex in North Las Vegas?
The jumbo line is higher for more units. * Two units: a loan up to $1,066,250 is conforming. That is $233,500 more room than a single-family home. * Three units: the limit is $1,288,800. * Four units: the limit is $1,601,750.
If you live in one unit: * FHA allows two to four units with 3.5% down, up to $693,050 for two units. * Lenders can count projected rent from the other units. * Three- and four-unit FHA buys must pass a self-sufficiency test. * VA allows up to four units for eligible veterans who live in one.
Investors who won't live there can look at DSCR loans, which are business-purpose loans only.
What does a true North Las Vegas jumbo loan require?
If your loan must go above the line, expect stricter rules than a conforming loan. Every lender writes its own. These are the typical ranges we see across the lenders we compare.
| Requirement | Typical range we see | What moves it |
|---|---|---|
| Jumbo threshold, 1 unit | Loan above $832,750 (FHFA 2026) | Set by FHFA each year |
| Down payment | Often 10-20% | Loan size, credit, property type, occupancy |
| Credit score | Many lenders start around 700 | Down payment and reserves |
| Debt-to-income | Commonly up to about 43%, some higher with strong reserves | Lender and program |
| Cash reserves after closing | Commonly 6-12 months of payments | Loan amount, number of properties owned |
| Appraisal | Full appraisal; a second appraisal is common on larger loans | Loan amount and lender |
| Income documents | Tax returns and W-2s, or bank statements, or asset depletion | Salaried vs self-employed; asset level |
Typical ranges, not a commitment to lend. Terms vary by lender.
Reserves are cash left after your down payment and closing costs. They are counted in months of your full housing payment: principal, interest, taxes, insurance and HOA dues. * Usually counts: checking, savings and brokerage accounts. Vested retirement accounts often count at a discount. * Usually doesn't count: gifts and borrowed money. * Seasoning: lenders want about two months of statements, and a paper trail for large deposits.
Income that doesn't fit a paycheck. Self-employed buyers can use bank-statement jumbo programs. Retirees and asset-rich buyers can use asset depletion. Both carry their own credit, down payment and reserve rules. Published wholesale jumbo programs extend to $5 million, with fixed, adjustable or interest-only options depending on the program.
From my desk
I started in mortgages in 2005 and have worked in tax preparation since 2008. That matters on jumbo files with complex income.
One of the most unusual clients I've worked with was a YouTube gamer buying a home in Henderson, not North Las Vegas, for roughly $3 million. Twenty years ago, a buyer at that price was probably a physician, an executive or a business owner with traditional statements. This buyer had built a career playing video games for an online audience. His team came back to me later about refinancing that home.
The challenge was making sure the lender saw the real financial picture, not just a job title. I won't quote a bank-versus-broker savings figure without comparing the actual offers.
I've also worked with a music producer and an Instagram influencer. That doesn't mean every dollar in the account counts. It means finding which receipts are eligible income, and a lender whose rules fit.
For more on luxury-tier jumbo loans across the valley, see our Las Vegas jumbo loan guide.
Is there a high-balance loan option in North Las Vegas?
No. Every Nevada county uses the national baseline limit in 2026, so there is no high-balance conforming tier. Any one-unit loan above $832,750 is jumbo.
That surprises buyers moving from coastal California. Los Angeles and Orange County allow conforming loans up to $1,249,125 in 2026, so a loan that was conforming there can be jumbo here. See jumbo vs high-balance loans in Nevada.
What costs hit North Las Vegas buyers near the jumbo line?
Transfer tax. Clark County charges $2.55 per $500 of value, rounded up. By local custom the seller pays it, but the contract controls.
| Price | Transfer tax |
|---|---|
| $832,750 | $4,248 |
| $850,000 | $4,335 |
| $900,000 | $4,590 |
| $950,000 | $4,845 |
| $1,000,000 | $5,100 |
| $1,100,000 | $5,610 |
| $1,250,000 | $6,375 |
Property tax. The North Las Vegas city rate is $3.3544 per $100 of assessed value for FY 2026-27. Assessed value is 35% of taxable value. That works out to about $1,174.04 per $100,000 of taxable value before the cap. It is higher than Henderson ($1,036.45) and the City of Las Vegas ($1,147.37). * The cap. On a primary home, the yearly increase is capped at 3% once you file the claim. * New construction gets no cap in its first year. * The Assessor's taxable value is often below the price you pay.
SIDs. Some newer northern subdivisions carry a special improvement district assessment. Lenders add it to your monthly payment, so it lowers how much home you qualify for. It can usually be paid off early. We pull the title report early. See Nevada SID and LID fees.
HOA dues. Aliante and newer communities often have a master and a sub-association. Both dues count in your ratios.
Is the address in the city? Some North Las Vegas mailing addresses are in unincorporated Clark County. That changes the tax rate. Check the Assessor's parcel record.

Can I refinance a North Las Vegas jumbo loan?
Yes. A few rules make it easier here: * The line is based on the new loan. If you've paid your balance down, or bring cash, a new loan at or under $832,750 can be conforming, even if your first loan was jumbo. * Your tax cap is safe. A refinance without a new ownership document does not affect your 3% property-tax cap. * VA borrowers have their own fees. An interest rate reduction refinance (IRRRL) has a 0.5% funding fee. A VA cash-out is 2.15% on first use and 3.3% after. * ARM borrowers should plan ahead. Before the fixed period ends, compare a new ARM, a fixed jumbo and a conforming loan with a paydown. * Cash-out is tighter. Lenders usually allow a lower max loan-to-value on a cash-out than on a rate-and-term refinance.
See our refinance page or call (702) 766-3744.
What documents do I need for a North Las Vegas jumbo loan or a VA loan above $832,750?
| Document | W-2 employee | Self-employed, full doc | Bank-statement jumbo | Asset-depletion jumbo | Active duty (Nellis) or veteran, VA |
|---|---|---|---|---|---|
| Government ID | Yes | Yes | Yes | Yes | Yes |
| Pay stubs and 2 years of W-2s | Yes | If any W-2 income | No | No | Leave and Earnings Statement, or job/retirement income documents |
| Personal tax returns | Often 2 years | Usually 2 years | Usually not | Usually not | If self-employed |
| Business tax returns | No | Usually 2 years | No | No | If self-employed |
| 12 or 24 months of bank statements | No | No | Yes | Statements for the qualifying assets | No |
| 2 months of asset statements for reserves | Yes | Yes | Yes | Yes, to calculate income | Yes |
| CPA letter or business license | No | Sometimes | Often | No | If self-employed |
| Certificate of Eligibility | No | No | No | No | Yes (we can request it) |
| DD-214 or orders | No | No | No | No | DD-214 for veterans; orders if relocating |
| Gift letter and donor statements | If gifted funds | If gifted funds | If gifted funds | If gifted funds | If gifted funds |
| Mortgage statement or sale contract on your current home | If you own | If you own | If you own | If you own | If you own |
How does a North Las Vegas jumbo loan work, step by step?
- Call first. Tell us the price, your cash and how you earn income. We check whether you can stay conforming, use VA or need a jumbo.
- Run the three paths. We compare a conforming loan with more down, VA (if eligible) and a jumbo side by side.
- Send your documents. Use the checklist above. A full package up front avoids surprises.
- Get pre-approved for your real loan amount. Your letter should match the loan you'll use, with reserves counted in dollars.
- Check the home before you offer. We look at comparable sales, SIDs, HOA dues and whether the parcel is in the city.
- Get your Loan Estimates. You receive them within 3 business days of a full application (Regulation Z).
- Order the appraisal right away. Larger loans may need a second one. VA appraisals also check property standards. You get a copy of each appraisal promptly on completion, or 3 business days before closing, whichever is earlier (Reg B, 12 CFR 1002.14).
- Clear underwriting. The lender reviews income, reserves, DTI and title. Fast answers keep the file moving.
- Review your Closing Disclosure. It arrives at least 3 business days before signing.
- Sign, fund and file your tax claim. After recording, claim the home as your primary residence so the 3% cap applies.
What do clients say about iQRATE Mortgages?
Real reviews, quoted word for word. They describe our team overall. None is confirmed to be a jumbo loan, and none is a promise about yours.
"David was very professional and went above and beyond to make sure I understand the loan procedure. In addition, he went with me to my closing because I expressed that I would be more comfortable with him there to explain the documents to me. He was there and ensured a smooth transaction. Everything completed as expected. I would definitely recommend him to my friends and family."
— Jasmin (Las Vegas, NV), 5-star review on Zillow.
"Well I've known David for many years. His office prepares my taxes. I had been putting off buying a home since I am a 1099 sales person. I thought mortgages were for wage earners. Never really thought I would qualify. They I mentioned to him in a conversation that I couldn't get a home, because of the type of income I have and all these reasons. In less than 10 minutes he had me qualified. Had to pay a couple of credit cards off, that was it, I own a home now. The only regret I have is not asking him sooner. This guy knows his numbers, taxes, rules and whatever else goes into that paperwork nightmare. Needless to say, I highly recommend him."
— garik 82 (Las Vegas, NV), 5-star review on Zillow.
"David's experience in the greater Las Vegas area has been a tremendous help in every aspect of buying my home. His work is quick, efficient, and reliable."
— eddieyervinyan (Las Vegas, NV), 5-star review on Zillow.
"iQrate Mortgage and all of their staff work very hard to make sure every single person that walks into their office leaves with ALL their questions answered. I just completed my refinance with iQRate Mortgage and I am extremely happy of the turnaround. They are fast, honest, and fair. I highly recommend everyone to their office, you will not regret it."
— Marine G. (South Shores, Las Vegas, NV), 5-star review on Yelp.
"David is amazing! He has our business for life! If you're looking for a mortgage company call David at iQRATE."
— Anita L., review on Google
Our ratings: Google 5.0 from 77 reviews. Yelp 5.0 from 51 reviews. Zillow 5.00 from 9 reviews. David is rated 5.0 stars from 87 reviews on Experience.com (October 2026). Read more reviews.
Which short videos help North Las Vegas buyers near the line?
Video: Stop Paying FHA Mortgage Insurance For 30 Years. I compare FHA and conventional loans, removing mortgage insurance and refinance options.
Video: Nevada Down Payment Help: Grant or Forgivable Loan? The two kinds of Nevada down payment help, and the rules that usually apply.
Where can I go deeper?
- Las Vegas jumbo loan guide (all of Clark County)
- Las Vegas jumbo loans: city loan data
- Henderson jumbo loans: city loan data
- North Las Vegas mortgage broker: FHA, VA and first-time buyers
- VA loans · FHA loans · Non-QM loans
- Las Vegas jumbo down payment and reserves 2026
- Mortgage calculators
Frequently asked questions
What is the jumbo loan limit in North Las Vegas for 2026?
A one-unit loan above $832,750 is jumbo. North Las Vegas uses the Clark County limit set by FHFA. For 2-4 units the limits are $1,066,250, $1,288,800 and $1,601,750.
How common are jumbo loans in North Las Vegas?
Rare. In 2025, 14 of 3,598 city home purchase loans were above that year's $806,500 limit (0.4%). Clark County was 4.0%. The count is small, so treat it as a snapshot.
What home price makes a North Las Vegas loan jumbo?
It depends on your down payment. The line is about $925,278 with 10% down and $1,040,938 with 20% down. Above that price, the loan is jumbo.
Can I stay conforming on a $900,000 home?
Yes, with 10% down. That is $90,000 down and an $810,000 loan, which is $22,750 under the limit. With 5% down the loan is $855,000, a jumbo.
Can I use a VA loan above $832,750 in North Las Vegas?
Often, yes. With full entitlement, VA has no loan limit. In 2025, 11 of the city's 14 jumbo loans were VA. Lenders may set their own caps, so we compare several.
Do I need a down payment on a VA loan above the limit?
Not with full entitlement, though some lenders set their own caps or terms. If you already have a VA loan open, your limit may tie to $832,750, and whether you need some down depends on your remaining entitlement. We check your Certificate of Eligibility.
What credit score do I need for a jumbo loan?
Many jumbo lenders start around 700. Some set higher minimums for bigger loans or smaller down payments. Terms vary by lender.
How much in reserves will a jumbo lender want?
Commonly 6 to 12 months of your full housing payment, left over after closing. Larger loans and more owned properties raise it.
Why do jumbo applications get denied in North Las Vegas?
In 2025, 8 of 24 were denied. The top reasons were collateral (appraisal or property) and DTI, three each. Limited comparable sales and local costs like SIDs and HOA dues can play a part.
Is there a high-balance loan in North Las Vegas?
No. No Nevada county is a high-cost area in 2026. Any one-unit loan above $832,750 is jumbo.
What is the conforming limit for a North Las Vegas duplex?
$1,066,250 for two units in 2026. That is $233,500 above the one-unit limit. FHA allows two units up to $693,050 with 3.5% down if you live in one.
How much is the transfer tax on a $900,000 North Las Vegas home?
$4,590. Clark County charges $2.55 per $500 of value, rounded up. The seller usually pays it here, but the contract controls.
Has iQRATE closed jumbo loans in North Las Vegas?
We have not published a North Las Vegas jumbo file. We have closed 13 VA loans from 2019 through 2023, mostly in Las Vegas, North Las Vegas and Henderson. Our valley-wide jumbo work is on our Las Vegas jumbo page. Past results do not guarantee future outcomes.
How do mortgage brokers get paid?
Either the lender pays the broker or you do, never both on one loan. Under Regulation Z, broker pay can't be based on your rate or loan terms. It appears on your Loan Estimate and Closing Disclosure.
Talk to David about your North Las Vegas jumbo question
Near the line, using VA, or truly jumbo? Tell me your price, your cash and how you earn income. I'll show you the conforming, VA and jumbo paths in writing.
- Call or text (702) 766-3744
- Apply now
- Contact us
iQRATE Mortgages, 6360 S Rainbow Blvd Ste 101, Las Vegas, NV 89118. Mon to Fri 9 am - 5 pm; weekends by appointment. Verify us on NMLS Consumer Access.
Where can I read more about North Las Vegas and Nevada jumbo loans?
These are our own guides. Each link opens a page on this site.
Which Southern Nevada city pages should I compare?
- North Las Vegas mortgage broker.
- Las Vegas jumbo loans (city loan data).
- Henderson jumbo loans (city loan data).
- Las vegas mortgage broker.
- Henderson mortgage broker.
- Summerlin mortgage broker.
- Nevada mortgage broker.
- Boulder city mortgage broker.
- Reno mortgage broker.
- Mesquite mortgage broker.
- Pahrump mortgage broker.
Which iQRATE loan program pages fit a buyer near the jumbo line?
- Jumbo loans in Nevada.
- VA loans.
- Bank statement.
- Non-QM.
- Asset depletion loans Nevada.
- DSCR.
- Investors.
- Calculators.
- Reviews.
- Apply now.
- Contact.
- Rates and how we quote.
- Guarantees.
Which Nevada jumbo and VA guides should I read?
- A guide to Las Vegas Reno rental portfolio blanket loans.
- A Nevada s corp guide to mortgage qualification.
- Bank statements vs tax returns for a Las Vegas mortgage.
- California to Las Vegas jumbo loan before selling your home.
- Consolidate Reno rentals with a DSCR portfolio loan.
- DSCR cash out refinance to scale a Las Vegas rental portfolio.
- Foreign national jumbo loans in Nevada a guide.
- Henderson jumbo loans macdonald highlands ascaya lake Las Vegas.
- How to buy more rentals in Nevada with a portfolio loan.
- Jumbo loans for a home in a trust in Las Vegas Nevada.
- Jumbo vs high balance loans in Nevada which is best.
- Jumbo vs piggyback loan in Las Vegas Henderson Nevada.
- Las vegas high rise condo jumbo loans and warrantability.
- Las vegas jumbo loan down payment and reserves 2026.
- Las vegas jumbo loans for new construction and custom homes.
- Navigating jumbo loan appraisal gaps in Reno Nevada.
- Nevada foreign investor portfolio loan Reno Las Vegas.
- Nevada mortgage after business change a self employed guide.
- Nevada portfolio loans for foreign investors guide.
- Nevada portfolio loans for your rental properties.
- Piggyback vs jumbo loan in Reno Nevada a cost guide.
- Portfolio loan risks in Reno and carson city Nevada.
- Portfolio loans for Las Vegas brrrr real estate investing.
- Portfolio loans for Nevada rentals a Las Vegas guide.
- Portfolio vs DSCR loans in Nevada for rental growth.
- Prep s corp taxes for Las Vegas jumbo loan approval.
- Qualify for a Las Vegas jumbo loan with no w 2s.
- Qualify for a Las Vegas mortgage as an s corp owner.
- Reno mortgage guide with less than 2 years self employed.
- Restore VA loan entitlement after divorce in Las Vegas.
- S corp mortgage guide for business owners in Nevada.
- S corp mortgage in Nevada get approved after a business change.
- S corp salary too low for a mortgage in Reno Nevada.
- S corp switch your Nevada mortgage how to get approved.
- Simplify Reno Las Vegas rentals with one portfolio loan.
- Use your portfolio for a Nevada jumbo loan in 2026.
- Using a VA loan to buy a Las Vegas condo in Nevada.
- Using part time income for a VA loan in Reno Nevada.
- Using s corp income for a mortgage in Nevada.
- VA cash out refinance vs heloc in Nevada a 2024 guide.
- VA condo approval in Las Vegas and Henderson Nevada.
- VA loan for Nevada veterans with a new business.
- VA loan with low credit in Las Vegas its possible.
- What to do after a failed VA appraisal in Nevada.
- When to apply for a self employed mortgage in Nevada.
Which North Las Vegas guides should I read?
Which Nevada VA loan guides help buyers near Nellis?
Which Southern Nevada guides cover down payment, credit, appraisal and refinance questions?
- 720 credit score but low cash in Nevada fha vs conventional.
- A DSCR loan for a Las Vegas non warrantable condo guide.
- A guide to de risking new construction loans in Nevada.
- A Nevada agents guide to appraisal defense systems.
- A proactive appraisal strategy for Nevada real estate agents.
- An agents guide to appraisal rebuttals in Nevada.
- Avoid closing costs on a Nevada home 2026 guide.
- Can a non relative gift my down payment in Nevada.
- Can manual underwriting save your Las Vegas fha loan app.
- Cash from a Nevada rental with a DSCR refinance.
- Clark county property tax and transfer tax on a Las Vegas DSCR rental.
- Cover fha closing costs with seller credits in Nevada.
- Covering an fha appraisal gap in Nevada without cash.
- Credit dispute halting your Las Vegas Nevada mortgage.
- Credit mistakes that kill a mortgage in Las Vegas Nevada.
- Dpa vs seller credits for a Las Vegas Nevada home loan.
- DSCR loan reserve rules in Las Vegas Nevada explained.
- DSCR loan reserves in Las Vegas Nevada a guide for investors.
- DSCR loans and high hoas in Las Vegas and Henderson.
- DSCR loans and hoa rules in Nevada a lenders guide.
- DSCR loans finance a Las Vegas condo hotel unit.
- DSCR loans for Las Vegas condo hotels your guide.
- DSCR loans for new construction rentals in Las Vegas.
- Fha 203k Renovation loans in Reno and sparks Nevada.
- Fha 90 day flip rule blocking your Nevada home loan.
- Fha credits vs conventional gifts for Nevada homebuyers.
- Fha loan denied in Las Vegas a manual underwrite can help.
- Fha multi family loan Nevada using future rent.
- Fha or conventional loan in Las Vegas for future buying.
- Fha or conventional with dpa in Las Vegas Henderson.
- Fha repair checklist for Reno carson city Nevada homes.
- Fha repairs for older homes in Reno Nevada.
- Fha vs 5 conventional loan in Nevada which builds equity faster.
- Fha vs conventional appraisal for older Nevada homes.
- Fha vs conventional for wealth building in Nevada.
- Fha vs conventional in Las Vegas which insurance is cheaper.
- Fha vs conventional in Las Vegas which needs less cash.
- Fha vs conventional in Nevada a 10 year wealth plan.
- Fha vs conventional in Nevada a long term wealth guide.
- Fha vs conventional loan for a Henderson Nevada home.
- Fha vs conventional loan for a Las Vegas condo.
- Fha vs conventional loan for your first Nevada home.
- Fha vs conventional loan in Nevada a total cost guide.
- Fha vs conventional loan in Nevada with a 620 credit score.
- Fha vs conventional loan Las Vegas 10 year cost comparison.
- Fha vs conventional loan with a 600 score in Nevada.
- Fha vs conventional loan with good credit in Nevada.
- Fha vs conventional loan with low credit in Nevada.
- Fha vs conventional loans in Nevada a 5 year cost guide.
- Fha vs conventional loans in Nevada which has hidden traps.
- Fha vs conventional mortgage insurance in Nevada.
- Fha vs conventional pmi in Nevada avoiding the cost trap.
- Financing a Las Vegas condo hotel with a DSCR loan.
- First time homebuyer in Las Vegas.
- Fix a credit error during your Las Vegas mortgage escrow.
- Fix a credit report error during escrow in Las Vegas.
- Fix credit report errors during a Las Vegas escrow.
- Get a Las Vegas mortgage with no credit score in Nevada.
- Get a mortgage in Henderson Reno with a thin credit file.
- Good credit but denied a Las Vegas Nevada mortgage why.
- Good credit denied mortgage in Las Vegas heres why.
- How hoa rules block DSCR loans in Las Vegas Nevada.
- How lenders average 1099 income in Las Vegas Reno.
- How lenders combine 1099 incomes in Las Vegas Reno.
- How to get a seller to pay fha costs in Nevada.
- How to read Nevada hoa docs for a condo loan.
- How to refinance in Nevada to buy out your spouse.
- How to speed up your Las Vegas DSCR loan refinance.
- How to use a gift of equity in Nevada for a mortgage.
- Is fha mortgage insurance in Reno Nevada a waste of money.
- Las vegas duplex triplex and fourplex DSCR loans.
- Las vegas fha loan denied with a 600 score heres why.
- Las vegas lender credits vs seller credits which is better.
- Low credit score how to buy a home in Reno Las Vegas.
- Mortgage recast vs refinance in Nevada which saves more.
- Mortgage shopping in Las Vegas will it hurt your credit.
- Nevada 1099 mortgage guide for gig worker income.
- Nevada condo hotel financing a guide to DSCR loans.
- Nevada fha or conventional with 5 down a 640 score.
- Nevada fha self sufficiency test for multi family homes.
- Nevada fha vs conventional loan with a 630 credit score.
- Nevada fha vs conventional which loan is cheaper.
- Nevada heloc vs cash out refinance fund your next home.
- Nevada mortgage guide for thin credit files.
- Nevada non recurring closing costs explained for homebuyers.
- Nevada sid and lid fees explained for homebuyers.
- Parents credit wrecked my Las Vegas mortgage heres a fix.
- Passing an fha appraisal on a Nevada fixer upper.
- Protect your credit score during escrow in Las Vegas Nevada.
- Refinance fha to conventional loan in Nevada.
- Save plan your Nevada fha loan will you get approved.
- Summerlin jumbo loans for guard gated and golf course homes.
- Systematize appraisals for success in Las Vegas Nevada.
- Tap Nevada rental equity without a cash out refinance.
- Thin credit mortgage in Las Vegas Henderson Nevada guide.
- Using a 401k loan for a down payment in Nevada.
- Using gift funds for closing costs in Reno Nevada.
- Using lender credits on a Nevada mortgage.
- Using seller credits in Las Vegas to win your offer.
- What is a rate and term refinance in Las Vegas Nevada.
- Why credit disputes halt fha loans in Las Vegas Nevada.
- Why fha condo loans are denied in Las Vegas Nevada.
- Why your fha loan was denied in Nevada with a 620 score.
- Why your good credit gets denied for a Las Vegas mortgage.
- Why your Nevada fha condo loan request was denied.
Sources
- FHFA, conforming loan limit values for 2026
- HUD Mortgagee Letter 2025-23, 2026 FHA limits
- FFIEC HMDA Data Browser, 2024 and 2025 loan-level files for Clark County. City figures are iQRATE's analysis of 59 in-city census tracts (computed November 5, 2026).
- VA, loan limits
- VA, funding fee and closing costs
- Nevada Department of Taxation, real property transfer tax
- Clark County Treasurer, tax rates by district, FY 2026-2027
- NRS 361.4723, property-tax cap
- Clark County Assessor
- Nevada Real Estate Group, North Las Vegas market report September 2026 (GLVAR MLS data)
- Zillow Research, ZHVI by ZIP code
- CFPB, 12 CFR 1026.19 (Loan Estimate and Closing Disclosure timing)
- CFPB, 12 CFR 1026.36 (loan originator compensation)
- NMLS Consumer Access
Dollar figures on this page are sample math from published limits and public data. They are not a quote, an offer or a prediction. No interest rate, APR or payment is shown because pricing depends on your file, fees and that day's market. Down payment, reserve, credit and DTI requirements vary by lender and change often. Not all borrowers will qualify. HMDA counts on this page are small; read them as counts, not stable percentages.
Broker compensation: iQRATE Mortgages is a mortgage broker, not a lender, and does not make credit decisions. We are paid either by the lender or by you, never both on the same loan. Our pay is not based on your interest rate or loan terms. It is shown on your Loan Estimate and Closing Disclosure.
This is not a commitment to lend. All loans are subject to credit, property and underwriting approval. Investor loans are for business purposes only. Past results do not guarantee future outcomes. Equal Housing Opportunity. iQRATE Mortgages LLC, NMLS 1862492. David Ghazaryan, Mortgage Broker, NMLS 1486726. 6360 S Rainbow Blvd Ste 101, Las Vegas, NV 89118. (702) 766-3744. Updated November 5, 2026.