Short answer: - The 2026 conforming loan limit for a one-unit home in Washoe County is $832,750, set by the Federal Housing Finance Agency (FHFA). It is the same in Sparks and Reno. - A loan above that amount is a jumbo loan. - Jumbo loans are rare in the City of Sparks, about 1 in 100 purchase loans in 2025 (City of Sparks tracts). - Most Sparks-area jumbo loans are in 89436 and on the Spanish Springs side (89441).
By David Ghazaryan, NMLS 1486726, iQRATE Mortgages (NMLS 1862492). Updated November 5, 2026.
Call or text (702) 766-3744. Tell us the price, the area and how you earn your income. We will tell you if your loan is jumbo, or if more down keeps it conforming.
How we got the Sparks numbers. - We used public loan-level data from the FFIEC HMDA Data Browser for Washoe County, 2024 and 2025. - We counted originated, first-lien home purchase loans that HMDA flags as above the conforming limit. - The limit was $766,550 in 2024 and $806,500 in 2025. - We show two areas, and we name them every time: - City of Sparks is 23 census tracts whose center lies inside city limits, using Census TIGERweb maps. Their combined population equals about 87.1% of the city's residents; edge tracts can include some land outside city limits. - Sparks-address ZIP area is 31 tracts in ZIPs 89431, 89434, 89436 and 89441. It adds unincorporated Spanish Springs, which has a Sparks mailing address but sits outside city limits. - Reno is not in either figure.
Read these numbers with care: - The counts are small, and percentages built on a handful of loans are rough. - HMDA counts loans. It does not count cash buyers.
Key facts: Sparks jumbo loans in 2026
- 2026 one-unit conforming limit, Washoe County: $832,750 (FHFA). It rose $26,250 (3.3%) from 2025.
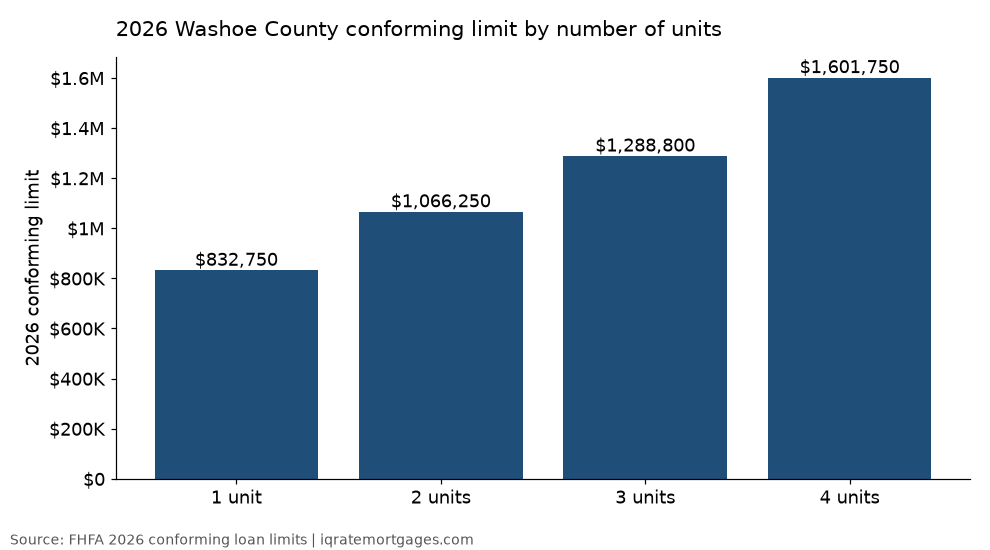
- Jumbo line for 2-4 units: $1,066,250, $1,288,800 and $1,601,750.
- There is no high-balance tier in Nevada. Above $832,750 on one unit means jumbo.
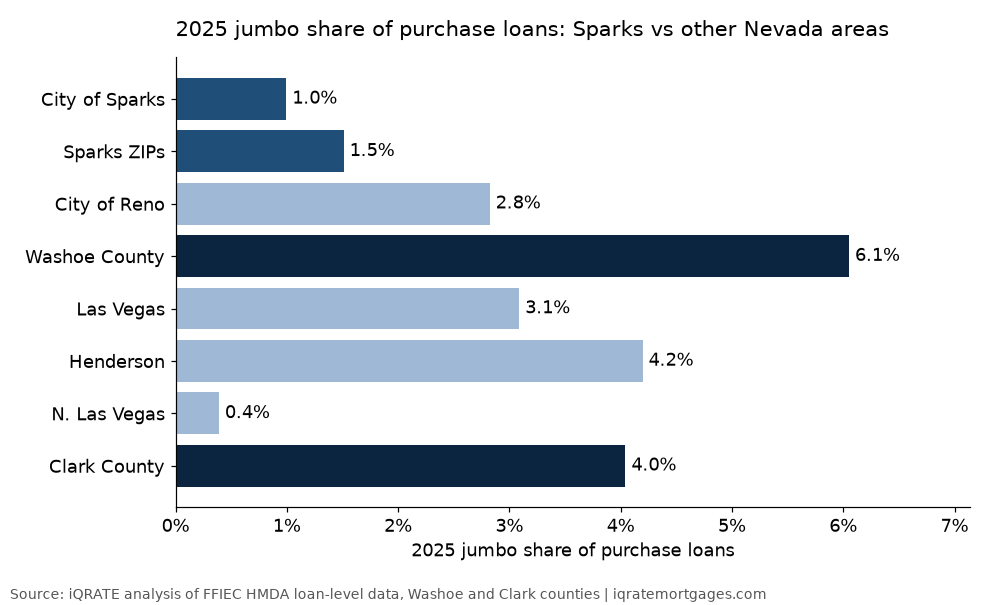
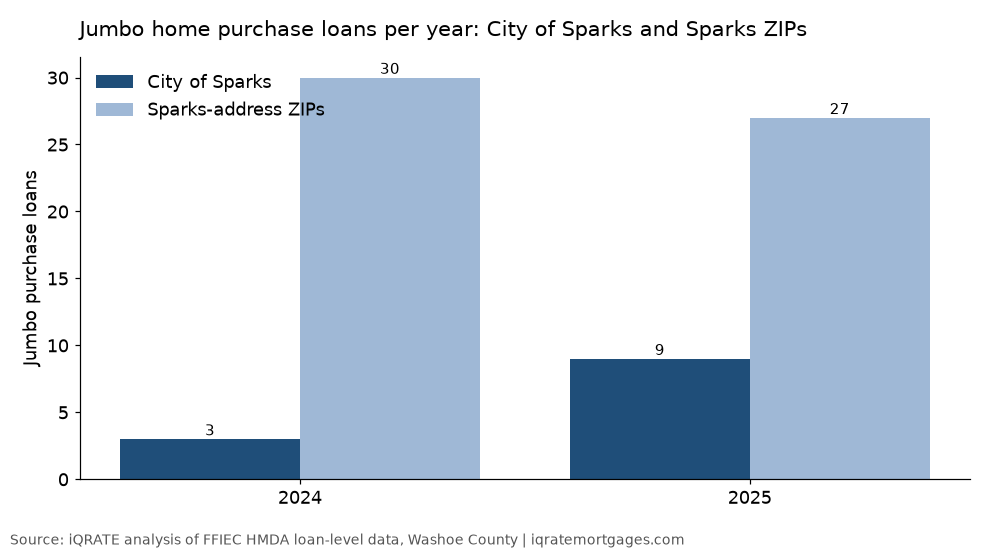
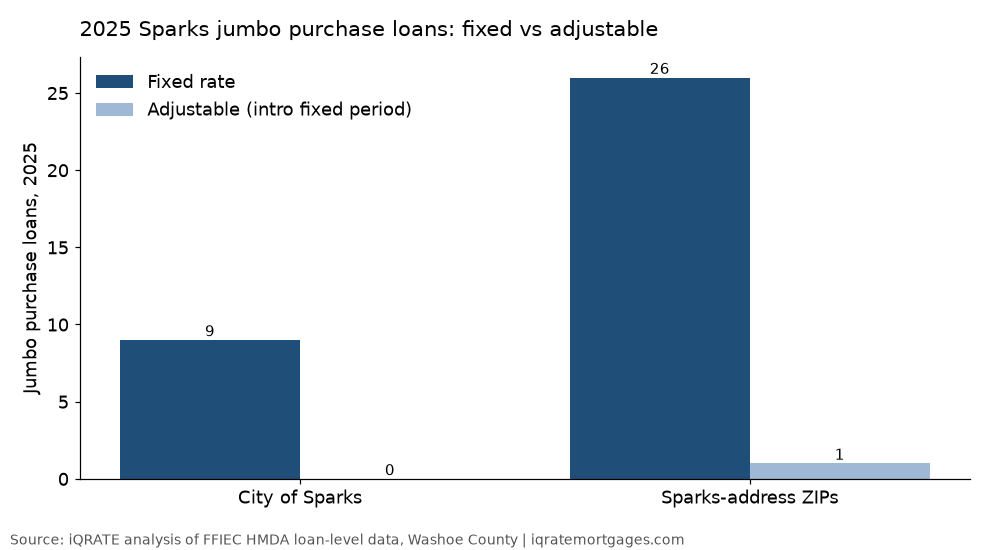
- City of Sparks, 2025: 9 of 905 purchase loans were jumbo (1.0%). All 9 were in 89436.
- Sparks-address ZIP area, 2025: 27 of 1,788 purchase loans were jumbo (1.5%).
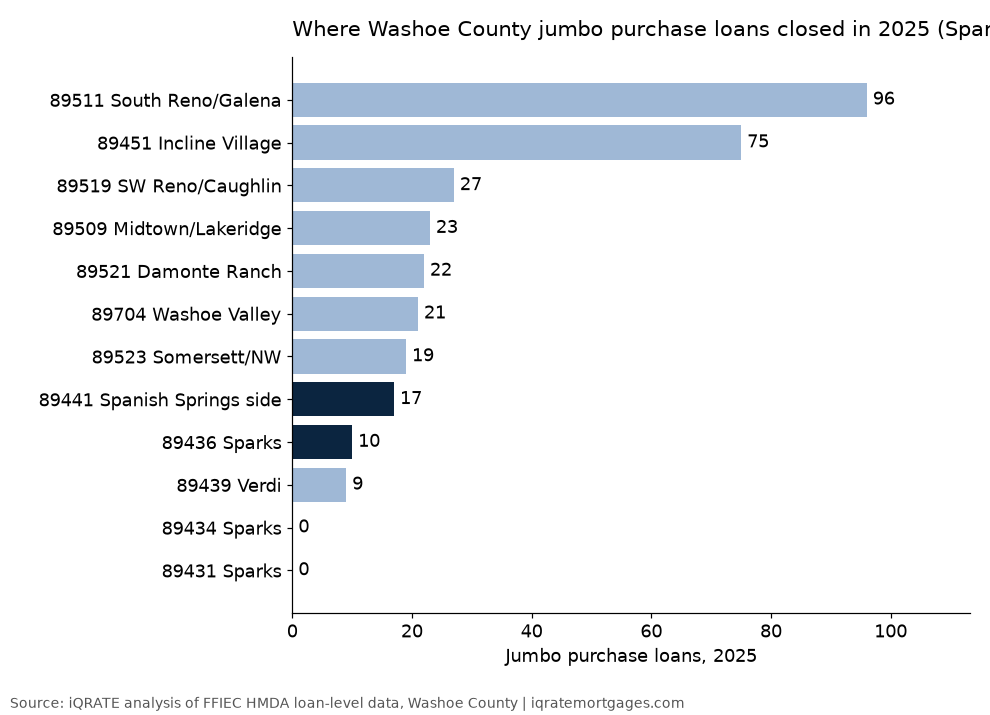
- Spanish Springs side (89441), 2025: 17 jumbo loans out of 373. That is more than the whole City of Sparks.
- Median City of Sparks jumbo loan, 2025: $955,000, on a median home value of $1,195,000.
- Many lenders made these loans. Eight different lenders made the 9 City of Sparks jumbo loans in 2025. Sixteen lenders made the 27 in the ZIP area.
Is my Sparks loan a jumbo loan?
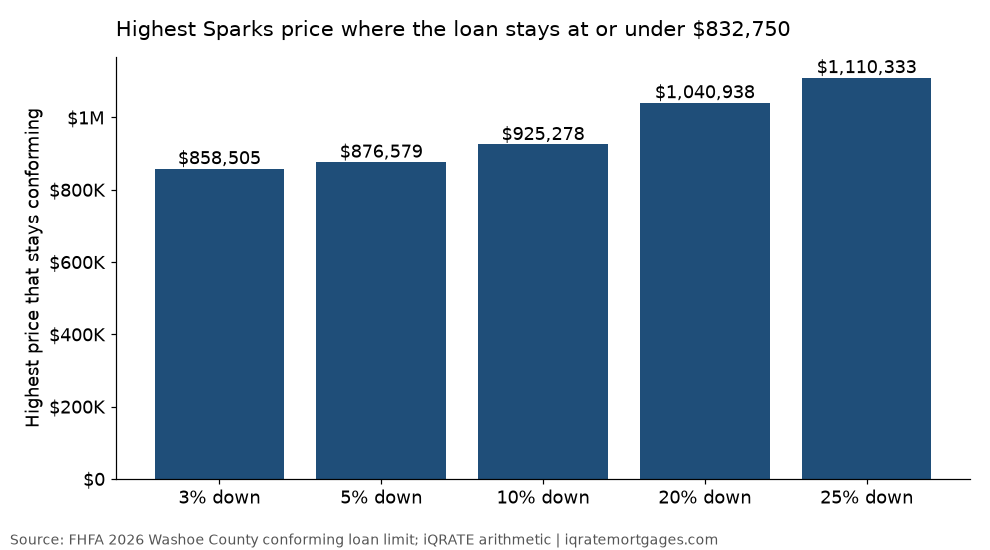
The limit applies to the loan amount, not the price. A home over $832,750 can still carry a conforming loan if you put more down.
Highest price that stays conforming, by down payment (one unit, 2026)
| Down payment | Loan-to-value | Highest price with a loan at or under $832,750 |
|---|---|---|
| 3% | 97% | $858,505 |
| 5% | 95% | $876,579 |
| 10% | 90% | $925,278 |
| 15% | 85% | $979,706 |
| 20% | 80% | $1,040,938 |
| 25% | 75% | $1,110,333 |
| 30% | 70% | $1,189,643 |
Math: $832,750 ÷ (1 − down payment). Each lender sets its own minimum down payment.
Conforming or jumbo? Sparks-area prices near the line
| Price | Down | Down payment | Loan amount | Result |
|---|---|---|---|---|
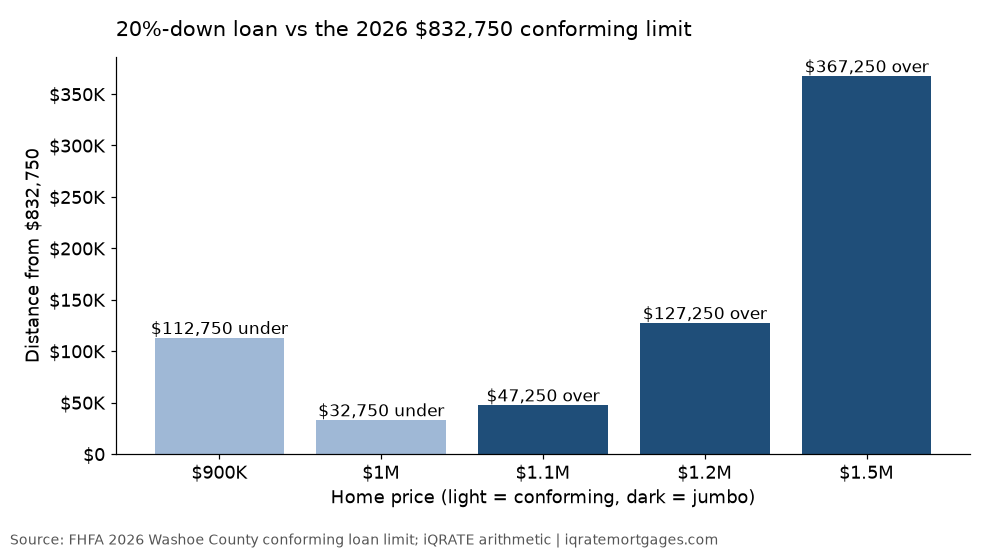
| $850,000 | 5% | $42,500 | $807,500 | Conforming, $25,250 under |
| $850,000 | 10% | $85,000 | $765,000 | Conforming, $67,750 under |
| $900,000 | 5% | $45,000 | $855,000 | Jumbo, $22,250 over |
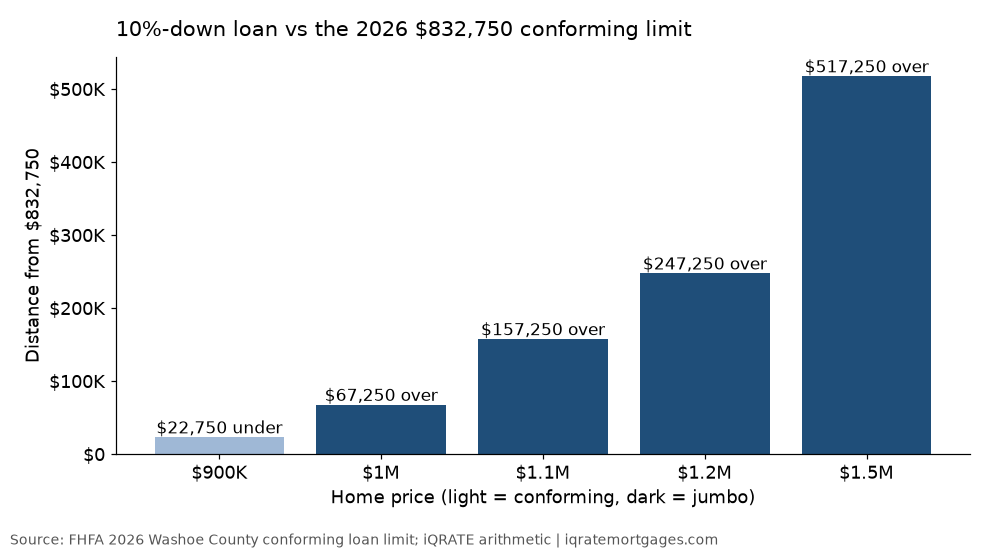
| $900,000 | 10% | $90,000 | $810,000 | Conforming, $22,750 under |
| $1,000,000 | 10% | $100,000 | $900,000 | Jumbo, $67,250 over |
| $1,000,000 | 20% | $200,000 | $800,000 | Conforming, $32,750 under |
| $1,100,000 | 20% | $220,000 | $880,000 | Jumbo, $47,250 over |
| $1,100,000 | 25% | $275,000 | $825,000 | Conforming, $7,750 under |
| $1,200,000 | 20% | $240,000 | $960,000 | Jumbo, $127,250 over |
| $1,200,000 | 25% | $300,000 | $900,000 | Jumbo, $67,250 over |
| $1,500,000 | 20% | $300,000 | $1,200,000 | Jumbo, $367,250 over |
| $1,500,000 | 25% | $375,000 | $1,125,000 | Jumbo, $292,250 over |
Simple math. It is not a quote or an offer.

How many Sparks buyers use jumbo loans?
Very few inside the city. More just outside it.
Jumbo share of home purchase loans (HMDA, same method for every area)
| Area | 2024 purchase loans | 2024 jumbo | 2024 share | 2025 purchase loans | 2025 jumbo | 2025 share |
|---|---|---|---|---|---|---|
| City of Sparks | 797 | 3 | 0.4% | 905 | 9 | 1.0% |
| Sparks-address ZIP area (incl. Spanish Springs) | 1,629 | 30 | 1.8% | 1,788 | 27 | 1.5% |
| City of Reno | 2,010 | 66 | 3.3% | 2,161 | 61 | 2.8% |
| Washoe outside Sparks and Reno city tracts | 2,077 | 243 | 11.7% | 2,338 | 257 | 11.0% |
| Washoe County | 4,884 | 312 | 6.4% | 5,404 | 327 | 6.1% |
| City of Las Vegas | 6,867 | 207 | 3.0% | 6,154 | 190 | 3.1% |
| City of Henderson | 5,626 | 255 | 4.5% | 5,195 | 218 | 4.2% |
| City of North Las Vegas | 3,967 | 3 | 0.1% | 3,598 | 14 | 0.4% |
Source: iQRATE analysis of FFIEC HMDA data.
How these counts compare with our Sparks broker page. This page uses HMDA's own 2025 jumbo flag, which was set at the $806,500 limit. That is why it counts 327 Washoe jumbo loans. Our Sparks mortgage broker page counts 2025 loans above the 2026 limit of $832,750, which gives 306 of 5,134. Both counts are correct for their own limit.
What it means: - The City of Sparks made 16.7% of Washoe purchase loans in 2025, but only 2.8% of its jumbo loans (9 of 327). - City of Sparks buyers mostly use conforming, FHA and VA loans. In 2025 the city had 602 conventional, 199 FHA and 104 VA purchase loans. - The median City of Sparks purchase loan was $415,000.


Where in Sparks do jumbo loans happen?
Sparks-address ZIP area by ZIP (all Washoe tracts in each ZIP)
| ZIP | Area | 2024 purchase loans | 2024 jumbo | 2025 purchase loans | 2025 jumbo | 2025 share |
|---|---|---|---|---|---|---|
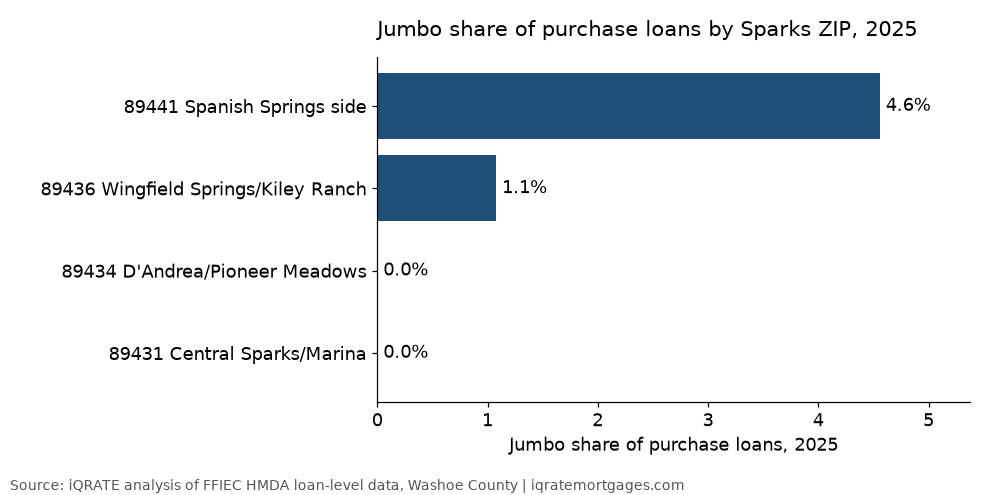
| 89436 | Wingfield Springs, Kiley Ranch, Foothills (also part of Spanish Springs) | 836 | 4 | 928 | 10 | 1.1% |
| 89441 | Spanish Springs side, north of Sparks (largely unincorporated) | 334 | 23 | 373 | 17 | 4.6% |
| 89434 | D'Andrea, Pioneer Meadows, Stonebrook, Vista Highlands | 229 | 2 | 223 | 0 | 0.0% |
| 89431 | Central Sparks, Sparks Marina, Victorian Square | 230 | 1 | 264 | 0 | 0.0% |
Here is what the table shows: - Inside City of Sparks tracts, every 2025 jumbo purchase loan was in 89436. That was 9 of 453 loans there. - 89431 and 89434 had no jumbo purchase loans in 2025, out of 487 loans combined. - The Spanish Springs side (89441) had more jumbo loans than the whole City of Sparks in both years.
Check whether the home is in the city. A Sparks mailing address does not mean the home is in the City of Sparks. Much of Spanish Springs is unincorporated Washoe County. - The loan limit is the same either way. - The tax district is not the same, and neither are the rental rules.

What does a typical Sparks jumbo loan look like?
Profile of jumbo purchase loans (HMDA)
| Measure | City of Sparks 2024 | City of Sparks 2025 | Sparks-address ZIPs 2024 | Sparks-address ZIPs 2025 |
|---|---|---|---|---|
| Jumbo purchase loans | 3 | 9 | 30 | 27 |
| Median jumbo loan | $915,000 | $955,000 | $860,000 | $955,000 |
| Median home value | $965,000 | $1,195,000 | $890,000 | $1,155,000 |
| Median loan-to-value | 89.2% | 80% | 95% | 81.2% |
| Median reported income | $328,000 | $354,000 | $241,000 | $346,000 |
| Adjustable-rate | 1 of 3 | 0 of 9 | 3 of 30 | 1 of 27 |
| Interest-only | 1 | 1 | 2 | 1 |
| Primary residence | 3 of 3 | 9 of 9 | 29 of 30 | 26 of 27 |
| VA loans above the limit | 0 of 3 | 2 of 9 | 15 of 30 | 10 of 27 |
| Conventional jumbo | 3 of 3 | 7 of 9 | 15 of 30 | 17 of 27 |
| Different lenders | 3 | 8 | 17 | 16 |
In plain words: - A Sparks jumbo loan is modest in size. The 2025 City of Sparks median of $955,000 is $122,250 above the 2026 limit. - All 9 City of Sparks jumbo loans in 2025 were fixed-rate. All were primary homes, and all were one unit. - No City of Sparks jumbo purchase loan in 2025 was above $1,500,000. - One of the nine was small enough that a loan that size would be conforming in 2026. This is approximate, because HMDA reports loans in $10,000 bands.
Jumbo loans by size
| Loan amount | City of Sparks 2024 | City of Sparks 2025 | Sparks-address ZIPs 2024 | Sparks-address ZIPs 2025 |
|---|---|---|---|---|
| Above the limit to under $1,000,000 | 3 | 5 | 27 | 16 |
| $1,000,000 to under $1,500,000 | 0 | 4 | 2 | 11 |
| $1,500,000 to under $2,000,000 | 0 | 0 | 0 | 0 |
| $2,000,000 to under $3,000,000 | 0 | 0 | 1 | 0 |
Jumbo loans by loan-to-value
| Loan-to-value | City of Sparks 2024 | City of Sparks 2025 | Sparks-address ZIPs 2024 | Sparks-address ZIPs 2025 |
|---|---|---|---|---|
| Over 50% to 70% | 0 | 0 | 2 | 0 |
| Over 70% to 80% | 1 | 5 | 5 | 13 |
| Over 80% to 90% | 1 | 2 | 3 | 5 |
| Over 90% | 1 | 2 | 20 | 9 |
In the Sparks-address ZIP area, most loans over 90% LTV above the limit were VA (15 of 30 jumbo-flagged loans were VA in 2024, 10 of 27 in 2025).
City of Sparks jumbo loans by debt-to-income, 2025 (9 loans)
| DTI reported | Loans |
|---|---|
| 20% to under 30% | 1 |
| 30% to under 36% | 1 |
| 36% to under 43% | 5 |
| 43% to under 50% | 1 |
| 50% to 60% | 1 |
Seven of the nine were under 43%. Two were at 43% or higher. A higher ratio can be approved at some lenders, but nine loans is a small sample.


Can you stay conforming instead of going jumbo?
This is the most common Sparks question.
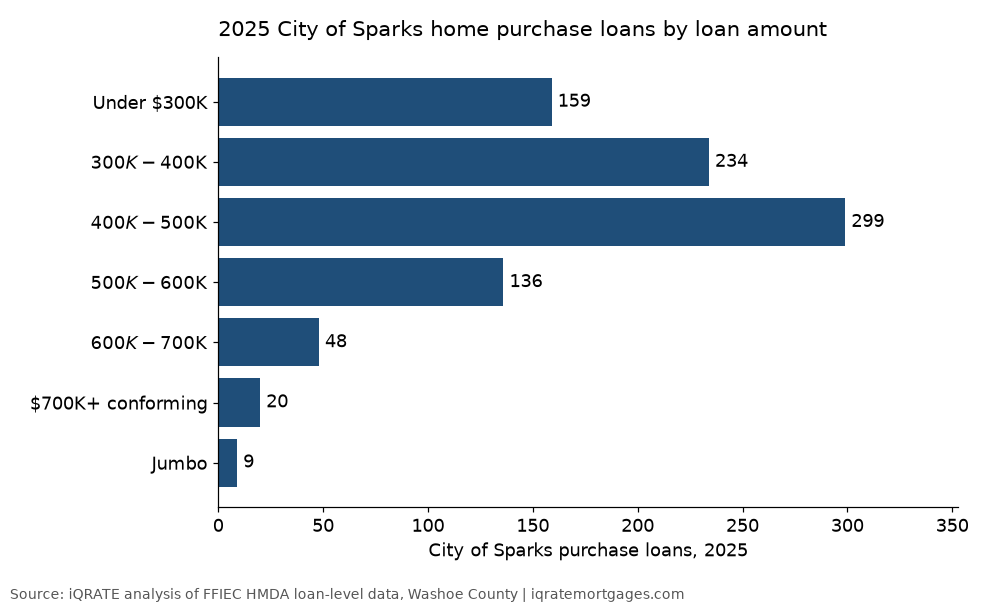
In 2025, 53 City of Sparks purchase loans were on homes valued at $800,000 or more. Only 9 of those buyers took a jumbo loan. The other 44 kept the loan at or under the limit. City of Sparks buyers also closed 20 conforming loans of $700,000 or more in 2025, which is more than twice the 9 jumbo loans.
All City of Sparks purchase loans by home value
| Home value | 2024 | 2025 |
|---|---|---|
| Under $400,000 | 158 | 170 |
| $400,000 to under $500,000 | 288 | 296 |
| $500,000 to under $600,000 | 197 | 246 |
| $600,000 to under $800,000 | 121 | 136 |
| $800,000 to under $1,000,000 | 22 | 38 |
| $1,000,000 to under $1,500,000 | 4 | 12 |
| $1,500,000 or more | 1 | 3 |
All City of Sparks purchase loans by loan amount
| Loan amount | 2024 | 2025 |
|---|---|---|
| Under $300,000 | 154 | 159 |
| $300,000 to under $400,000 | 225 | 234 |
| $400,000 to under $500,000 | 255 | 299 |
| $500,000 to under $600,000 | 109 | 136 |
| $600,000 to under $700,000 | 36 | 48 |
| $700,000 and up, within the limit | 15 | 20 |
| Above the limit (jumbo) | 3 | 9 |
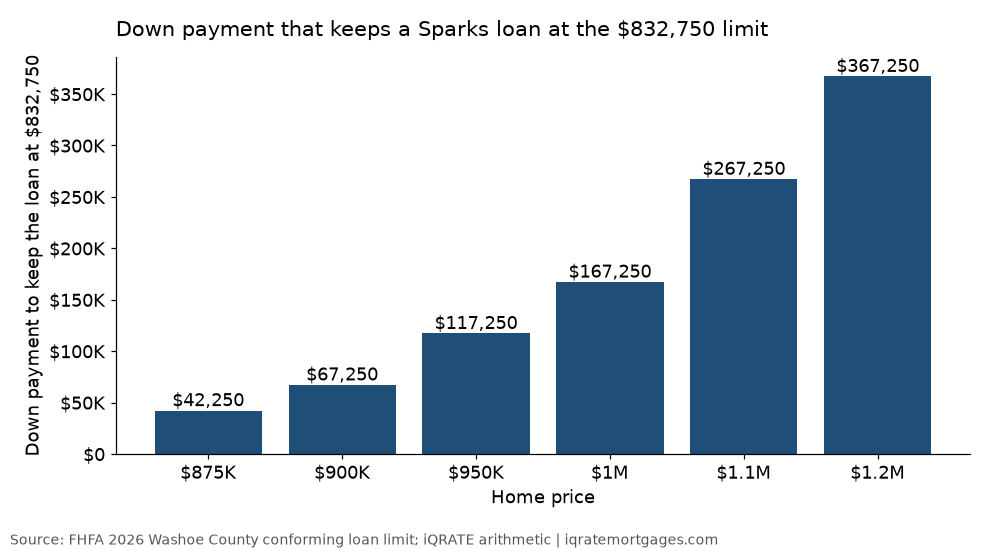
Down payment that keeps the loan at $832,750
| Price | Down payment to stay conforming | Share of price |
|---|---|---|
| $875,000 | $42,250 | 4.8% |
| $900,000 | $67,250 | 7.5% |
| $950,000 | $117,250 | 12.3% |
| $1,000,000 | $167,250 | 16.7% |
| $1,100,000 | $267,250 | 24.3% |
| $1,200,000 | $367,250 | 30.6% |
Which route costs less depends on several things: your credit, your reserves, how long you keep the loan and that day's pricing. We lay out cash to close and fees for each option side by side. Some buyers also compare a conforming first loan with a second lien.
Near the line? Call (702) 766-3744 before you write an offer.


Sparks jumbo check: is your loan above the Washoe County limit?
Enter a price, a down payment and the number of units. The tool does arithmetic only. It uses the 2026 Washoe County conforming limits from FHFA ($832,750 for one unit, $1,066,250 for two, $1,288,800 for three and $1,601,750 for four). It also shows the Washoe County transfer tax at $2.05 per $500 of value. It does not quote a rate or a payment. VA has no loan limit for borrowers with full entitlement. The tool shows the conforming test only.
How it works: - Veterans with full entitlement have no VA loan limit. - There is no monthly mortgage insurance. - A VA funding fee may apply: - 2.15% of the loan on first use with no down payment - 3.3% on later use with no down payment - 1.5% on first use with 5% down - Veterans with a service-connected disability rating are exempt. - Some lenders set their own maximum VA loan amount. That is one more reason to shop.
Compare a VA loan with a conventional jumbo before you choose. See our VA loans page and the VA loan limits page.
Video: Don't Make This $9,000 VA Funding Fee Mistake. David Ghazaryan explains how the funding fee works, who is exempt, and how a small down payment can lower it.

Moving from California or the Bay Area to Sparks?
The limit drops when you cross the state line. In 2026, conforming loans in San Francisco, Santa Clara, Alameda, Los Angeles and Orange counties go up to $1,249,125. In Washoe County, jumbo starts at $832,750. A loan that was conforming in the Bay Area can be jumbo in Sparks. Sacramento uses the same $832,750 limit as Washoe.
In my experience with Californians relocating to Las Vegas, the work centers on three things: - proceeds from the prior home - reserves - whether the job continues after the move
Here are the common options for buying before you sell: - a bridge loan - a HELOC on the California home - qualifying with both housing payments
Which one fits depends on your equity, income and reserves. It also varies by lender.
iQRATE is licensed in Nevada and California, so one team can work both sides of the move.
Self-employed, retired, or paid in RSUs and bonuses?
I started in the mortgage industry in 2005. I have also worked in tax preparation since 2008. That mix helps on files where income is real but hard to read.
Self-employed and content creators. I've worked with a music producer and an Instagram influencer. One of the most unusual clients was a YouTube gamer buying a home in Henderson for roughly $3 million. That was a Southern Nevada file, not Sparks. A bank's standard tax-return math is not always the best way to qualify. We cannot count every dollar that hits the account. We find which receipts count as income, then find a lender whose rules fit. Options include: - 12- or 24-month bank-statement loans - 1099 or CPA-prepared P&L options
Retirees and high-net-worth buyers. Some people have millions invested but little paycheck income. Asset-depletion and asset-utilization programs can sometimes solve that mismatch.
Bonus, incentive pay and RSUs. Pay can include bonuses, commissions and equity awards. We confirm which parts the lender will count and how it will count them. Expect to show a history that the income is likely to continue.
What programs can I arrange? Published wholesale jumbo programs extend to $5 million. Separate bank-statement and asset-utilization products exist too. Some allow fixed, adjustable or interest-only payments. Others have strict reserve rules or limits on investment property. Non-QM programs usually need more down and more reserves than full-doc jumbo loans. See non-QM loans.
Buying a 2-4 unit property in Sparks?
The jumbo line is higher for more units: - 2 units: $1,066,250, which is $233,500 above the one-unit limit - 3 units: $1,288,800 - 4 units: $1,601,750
No City of Sparks jumbo purchase loan in 2024 or 2025 was on a 2-4 unit property.
Short-term rentals. If you plan to rent units, check the rules first. Washoe County says it cannot issue short-term rental permits inside Sparks. Unincorporated Spanish Springs falls under Washoe County's permit rules.
Why do Sparks jumbo applications get denied?
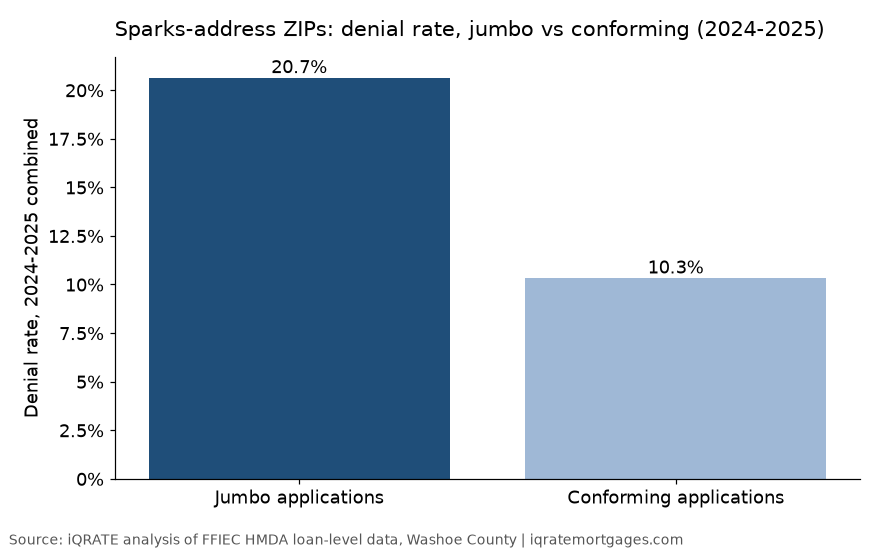
In the Sparks-address ZIP area, 19 of 92 decided jumbo applications were denied over 2024 and 2025. That is 20.7%, versus 10.3% for conforming applications.
Decided jumbo applications (all loan purposes; small counts, treat as rough)
| Area, year | Decided jumbo | Denied | Denial rate | Decided conforming | Denied | Denial rate |
|---|---|---|---|---|---|---|
| City of Sparks, 2024 | 9 | 3 | 33.3% | 1,290 | 169 | 13.1% |
| City of Sparks, 2025 | 15 | 4 | 26.7% | 1,517 | 162 | 10.7% |
| Sparks-address ZIPs, 2024 | 45 | 8 | 17.8% | 2,441 | 264 | 10.8% |
| Sparks-address ZIPs, 2025 | 47 | 11 | 23.4% | 2,800 | 278 | 9.9% |
Main reason for the 19 denied jumbo applications, Sparks-address ZIPs, 2024-2025
| Reason | Denials |
|---|---|
| Debt-to-income ratio | 9 |
| Collateral (appraisal or property) | 3 |
| Credit history | 3 |
| Application incomplete | 2 |
| Insufficient cash | 1 |
| Other | 1 |
Debt-to-income was the top reason. Those are very different problems, and some can be fixed with documentation or a different program.
When another lender can't approve a file, I don't assume it made a mistake. I find out exactly why it said no: - income calculation - reserves - restricted stock - a debt-to-income limit - the appraisal
Those are very different problems. Then we decide whether documents fix it, or whether you need a different program.
Video: Bank Denied Your Loan? Do This Instead. David Ghazaryan explains what to do after a bank says no, and why a broker can shop other lenders.

How do I compare jumbo lenders and brokers in Sparks?
A ranked list of lenders cannot tell you if a lender fits your file. Every jumbo lender writes its own rules. The 2025 data shows how spread out the market is: - City of Sparks: 8 lenders made 9 jumbo purchase loans. - Sparks-address ZIP area: 16 lenders made 27.
The loans were spread across many lenders. A broker can shop your file with many lenders, more than 100 on complex files in our case.
| What to check | Why it matters | Question to ask |
|---|---|---|
| Nevada license | Only Nevada-licensed companies and loan officers can originate your loan | What are your company and personal NMLS numbers? |
| Correct limit | Some pages still use $766,550 or $806,500 | What is the 2026 Washoe one-unit limit? ($832,750) |
| Number of lenders | Rules on credit, reserves and LTV differ by lender | How many jumbo lenders will see my file? |
| Program range | Self-employed, retired and VA buyers need options | Can you do full-doc, bank-statement, asset-depletion and VA? |
| Reserve plan | Short reserves force late restructuring | How many months, in dollars, and which accounts count? |
| Appraisal plan | Only 15 City of Sparks purchase loans in 2025 were on homes valued at $1,000,000 or more (HMDA; excludes cash sales) | Will this loan need a second appraisal? |
| Fees in writing | A verbal quote is not binding | Will I get Loan Estimates I can compare line by line? |
| Closing reliability | Late surprises sink contracts | What usually delays your jumbo files, and how do you prevent it? |
| Speed | Federal rules require a Loan Estimate within 3 business days of application | When will I have every Loan Estimate in hand? |
| Compensation | Broker pay must be disclosed | How are you paid on this loan? |
How to compare fees. Get official Loan Estimates from each option on the same day, for the same loan. Compare the lender charges, points and credits line by line.
How to judge reliability. - Ask for a fully documented pre-approval. - Ask how the lender will calculate your income. - Get the reserve figure in dollars before you write an offer.
Red flags: - a quote that uses the 2025 or 2024 limit - a price quoted before anyone reviews your income and assets - pressure to commit before you compare Loan Estimates - one program offered as the only option
Want your file shopped? Call (702) 766-3744 or apply now.

What do Washoe taxes and costs look like near the jumbo line?
Transfer tax. Washoe County charges $2.05 per $500 of value, rounded up. That is the $1.95 state rate plus $0.10 for Washoe. The contract decides who pays.
| Price | Washoe transfer tax | Same price in Clark County |
|---|---|---|
| $832,750 | $3,415 | $4,248 |
| $900,000 | $3,690 | $4,590 |
| $1,000,000 | $4,100 | $5,100 |
| $1,200,000 | $4,920 | $6,120 |
| $1,500,000 | $6,150 | $7,650 |
Property tax. - The City of Sparks rate is about $3.66 per $100 of assessed value for FY 2026-27. - Assessed value is 35% of taxable value. That works out to about $1,281 a year per $100,000 of taxable value, before the cap. - Unincorporated parcels in Truckee Meadows Fire area 4000 pay $3.2402. Sun Valley pays $3.4698. - Check the tax district on the Washoe County Assessor parcel record. - File the primary-home claim after closing to keep the 3% cap.
Closing costs. For iQRATE clients, Nevada closing costs typically run about $6,000 to $8,000 on full-documentation loans. Some non-QM loans run about $15,000. Your Loan Estimate itemizes them. Larger loans may also add a second appraisal.

Can I refinance a Sparks jumbo loan?
Yes. The same tiered rules apply as on a purchase.
- Cash-out has tighter limits. Lenders usually allow a lower maximum loan-to-value on a cash-out refinance than on a rate-and-term refinance.
- The line moves with your balance. It is based on the new loan amount. If you've paid down your balance, or bring cash, a new loan at or under $832,750 can be conforming.
- Your tax cap is safe. A refinance with no ownership change does not affect your 3% property tax cap.
- ARM borrowers should plan ahead. Before the fixed period ends, compare a new ARM, a fixed jumbo, and a conforming loan with a paydown.
See refinance options.
Which documents do I need for a Sparks jumbo loan?
| Document | W-2 employee | Self-employed, full doc | Bank-statement jumbo | Asset-depletion jumbo | Relocating from California |
|---|---|---|---|---|---|
| Government ID | Yes | Yes | Yes | Yes | Yes |
| Pay stubs and W-2s | Yes | If any W-2 income | No | No | Yes if employed |
| Bonus or RSU history | If used to qualify | If used to qualify | No | No | If used to qualify |
| Personal tax returns | Often 2 years | Usually 2 years | Usually not | Usually not | Yes if full doc |
| Business tax returns | No | Usually 2 years | No | No | If self-employed |
| 12 or 24 months of bank statements | No | No | Yes | For the qualifying assets | If using bank-statement income |
| Brokerage and retirement statements | For reserves | For reserves | For reserves | Yes, to figure income | Yes |
| CPA letter or business license | No | Sometimes | Often | No | If self-employed |
| Current home mortgage statement or sale contract | If you own | If you own | If you own | If you own | Yes |
| Gift letter and donor statements | If gifted | If gifted | If gifted | If gifted | If gifted |
Requirements vary by lender. Explain any large deposits before you apply.
How does a Sparks jumbo loan work, step by step?
- Call first. Tell us the price, the area and how you earn. We check if more down keeps you conforming.
- Send documents. We review income, assets and credit up front.
- Shop lenders. We compare full-doc, bank-statement, asset-based and VA options in writing.
- Get pre-approved. Your letter goes with your offer.
- Review your Loan Estimate. It comes within 3 business days of application.
- Go under contract and signal intent to proceed. The appraisal is ordered after the Loan Estimate and your intent to proceed. A larger loan may need two.
- Clear conditions. The underwriter checks income, reserves and title. Quick answers keep it moving.
- Review the Closing Disclosure. You get it at least 3 business days before signing.
- Close with Washoe County escrow. The loan funds and records.
How does Sparks compare with Reno for jumbo loans?
The limit is the same, $832,750. The markets are not. - City of Reno: 2.8% of 2025 purchase loans were jumbo, about 2.8 times the City of Sparks share. - South Reno (89511): 96 of 283 purchase loans were jumbo in 2025 (33.9%). That is more than 3 times the whole Sparks-address ZIP area (27). - Loan type: About a third of City of Reno jumbo loans were adjustable. All 9 City of Sparks jumbo loans were fixed.
Buying in Reno? See Reno jumbo loans: Washoe County loan data.
What jumbo experience do we have?
We are a Las Vegas-based Nevada brokerage. We serve Sparks remotely. Sparks loans close with a Washoe County title and escrow company.
We don't have a Sparks or Washoe County jumbo closing to show you. Here are jumbo files from elsewhere (details on our jumbo loan guide): - A roughly $2.45M owner-occupied Nevada jumbo purchase, closed in summer 2025, application to funding in about nine weeks. - A Las Vegas content creator who bought a home near $2.7 million in spring 2026 with a jumbo loan near $2 million, 25% down. It closed in about a month. - A Las Vegas 15-year jumbo refinance that went from submission to clear to close in about 12 days.
Past results do not guarantee future outcomes.
Local loan data for other Nevada cities: - Las Vegas city jumbo data - Henderson jumbo loans - North Las Vegas jumbo loans
What do clients say about iQRATE Mortgages?
These are real 5-star reviews, quoted word for word. They describe our team overall. None is confirmed to be a jumbo loan, and none is a promise about yours.
"A few months ago we bought our first house. We were so fortunate to have David. He explained so many things that we did not understand, literally took the time to explain our options and why they would or would not work for us. He made us feel comfortable with our decision. We definitely would recommend his entire team, everyone was so wonderful and helpful."
— Jael O., 5-star review on Google.
"Very efficient and transparent service. They go above and beyond to deliver the loan closure on time even in a very tight time line. Also very resourceful and knowledgeable staff. I'll go to them again next time I need a loan."
— Rita S. (Los Angeles, CA), 5-star review on Yelp.
"Well I've known David for many years. His office prepares my taxes. I had been putting off buying a home since I am a 1099 sales person. I thought mortgages were for wage earners. Never really thought I would qualify. They I mentioned to him in a conversation that I couldn't get a home, because of the type of income I have and all these reasons. In less than 10 minutes he had me qualified. Had to pay a couple of credit cards off, that was it, I own a home now. The only regret I have is not asking him sooner. This guy knows his numbers, taxes, rules and whatever else goes into that paperwork nightmare. Needless to say, I highly recommend him."
— garik 82 (Las Vegas, NV), 5-star review on Zillow.
"I highly reccomend David. He treated my loan process in the same manner as he would of had if it's his own. David walked me through the process from the beginning to the end. He was always available when i called, even on weekends and holidays, especially when he had a family tragedy he still made my loan a priority and finished it on time as promised."
— Yelena M. (Henderson, NV), 5-star review on Zillow.
"David's experience in the greater Las Vegas area has been a tremendous help in every aspect of buying my home. His work is quick, efficient, and reliable."
— eddieyervinyan (Las Vegas, NV), 5-star review on Zillow.
Our ratings: Google 5.0 from 77 reviews. Yelp 5.0 from 51 reviews. Zillow 5.00 from 9 reviews. Read more reviews.
Frequently asked questions
What is the jumbo loan limit in Sparks, NV for 2026?
It is $832,750 for a one-unit home in Washoe County, per FHFA. A loan above that is jumbo. For 2-4 units the limits are $1,066,250, $1,288,800 and $1,601,750.
Is the jumbo limit different in Sparks, Reno or Spanish Springs?
No. All of Washoe County uses the same limits. Spanish Springs uses them too, even where it is unincorporated.
How many Sparks buyers use jumbo loans?
Few. In 2025, 9 of 905 City of Sparks purchase loans were jumbo (1.0%). Across the Sparks-address ZIP area it was 27 of 1,788 (1.5%). HMDA does not count cash buyers.
How much down payment do I need for a jumbo loan in Sparks?
Often 10-20%, depending on the lender. The median City of Sparks jumbo loan-to-value in 2025 was 80%. VA buyers with full entitlement may put less down.
Can I avoid a jumbo loan on a $1,000,000 Sparks home?
Yes. A down payment of $167,250 or more keeps the loan at $832,750. With 20% down, the loan is $800,000, which is conforming.
What credit score do I need?
Many jumbo lenders start around 700. Some want more for larger loans or smaller down payments.
How many months of reserves do I need?
Commonly 6-12 months of full housing payments after closing. Larger loans and other financed properties raise it.
What debt-to-income ratio do jumbo lenders allow?
Commonly up to about 43%. Some allow more with strong reserves. In 2025, two of the nine City of Sparks jumbo loans were at 43% or higher.
Do I need two appraisals?
Sometimes. A second appraisal or review is common on larger loans. Ask early, because it adds time.
Do jumbo loans have PMI?
Most do not use standard private mortgage insurance. Lenders usually ask for more down instead.
Are jumbo rates higher than conforming rates?
It depends on the lender and the day. We do not post rates here. Compare official Loan Estimates on the same day.
Are Sparks jumbo loans fixed or adjustable?
All 9 City of Sparks jumbo loans in 2025 were fixed-rate. Adjustable and interest-only programs exist at some lenders.
Can I get a jumbo loan if I'm self-employed?
Yes. Bank-statement, 1099, P&L and asset-depletion programs can qualify you without standard tax-return income. They often need more down and more reserves.
Can I use a VA loan above $832,750 in Sparks?
Often, yes. Veterans with full entitlement have no VA loan limit. VA loans were 10 of the 27 loans above the limit in the Sparks-address ZIP area in 2025. Some lenders cap the amount.
Why are jumbo applications denied in Sparks?
Debt-to-income was the top reason, cited in 9 of 19 Sparks-address ZIP area denials in 2024-2025. Collateral (appraisal or property) and credit history followed, with 3 each.
How long does a jumbo loan take to close?
It depends on the lender, the appraisal and your documents. The Loan Estimate comes within 3 business days of application. The Closing Disclosure comes at least 3 business days before closing.
Can I refinance a jumbo into a conforming loan?
Yes, if the new loan is $832,750 or less on one unit. Paying down the balance or bringing cash can get you there.
What is the transfer tax on a $1,000,000 home in Sparks?
It is $4,100, at Washoe County's rate of $2.05 per $500. The contract decides who pays.
Is Spanish Springs part of the City of Sparks?
Not all of it. Spanish Springs has a Sparks mailing address, but much of it is unincorporated Washoe County. The 89441 side had 17 jumbo purchase loans in 2025, more than the 9 inside City of Sparks tracts. The loan limit is the same: $832,750 for one unit.
Which Sparks ZIP codes had jumbo loans in 2025?
In the Sparks-address ZIP area, 89441 had 17 and 89436 had 10. ZIPs 89431 and 89434 had none. Inside City of Sparks tracts, all 9 jumbo purchase loans were in 89436.
What is the jumbo limit for a duplex or fourplex in Sparks?
The 2026 Washoe County limits are $1,066,250 for 2 units, $1,288,800 for 3 units and $1,601,750 for 4 units. A loan above the limit for its unit count is jumbo. No City of Sparks jumbo purchase loan in 2024 or 2025 was on a 2-4 unit property.
How big is a typical Sparks jumbo loan?
The median City of Sparks jumbo purchase loan in 2025 was $955,000, on a median home value of $1,195,000. The median loan-to-value was 80%. No City of Sparks jumbo purchase loan in 2025 was above $1,500,000.
How many lenders make jumbo loans in Sparks?
Eight different lenders made the 9 City of Sparks jumbo purchase loans in 2025. Sixteen lenders made the 27 in the Sparks-address ZIP area. A broker can shop your file with many lenders.
Is a jumbo loan more common in Sparks or Reno?
Reno. In 2025, 2.8% of City of Reno purchase loans were jumbo, versus 1.0% inside City of Sparks tracts. See Reno jumbo loans for the Reno data.
Do most Sparks buyers of $800,000+ homes need a jumbo loan?
No. In 2025, 53 City of Sparks purchase loans were on homes valued at $800,000 or more. Only 9 were jumbo. The other 44 kept the loan at or under the limit.
Where can I read more about Sparks, Reno and Nevada jumbo loans?
These are our own guides. Each link opens a page on this site.
Which Nevada city pages should I compare?
- Sparks mortgage broker (Sparks loan limits, taxes, ZIP market data).
- Reno jumbo loans (City of Reno and Reno ZIP loan data).
- Reno mortgage broker (Washoe loan limits, taxes, market data).
- Carson city mortgage broker.
- Las Vegas jumbo loans (city loan data).
- Henderson jumbo loans (city loan data).
- North Las Vegas jumbo loans (city loan data).
- Nevada mortgage broker.
- Las Vegas mortgage broker.
- Henderson mortgage broker.
- Summerlin mortgage broker.
Which iQRATE loan program pages fit a buyer near the jumbo line?
- Jumbo loans in Nevada.
- Bank statement loans.
- Non-QM loans.
- Asset depletion loans in Nevada.
- DSCR loans.
- Investor loans.
- VA loans.
- Mortgage calculators.
- Client reviews.
- Apply now.
- Contact us.
- Rates and how we quote.
- Our written guarantees.
Which Sparks, Reno and Northern Nevada guides should I read?
Which Nevada jumbo, self-employed and high-income guides help?
- A guide to California jumbo Renovation loans.
- A Nevada S-Corp guide to mortgage qualification.
- Bank statements vs tax returns for a Las Vegas mortgage.
- California investors buying Las Vegas rentals with a DSCR loan.
- California to Las Vegas jumbo loan before selling your home.
- Foreign national jumbo loans in Nevada a guide.
- Henderson jumbo loans macdonald highlands ascaya lake Las Vegas.
- How Nevada lenders calculate overtime & bonus income.
- Jumbo loans for a home in a trust in Las Vegas Nevada.
- Jumbo vs high balance loans in Nevada which is best.
- Jumbo vs piggyback loan in Las Vegas & Henderson Nevada.
- Las Vegas high rise condo jumbo loans and warrantability.
- Las Vegas jumbo loan down payment and reserves 2026.
- Las Vegas jumbo loans for new construction and custom homes.
- Nevada mortgage after business change a self employed guide.
- Prep S-Corp taxes for Las Vegas jumbo loan approval.
- Qualify for a Las Vegas jumbo loan with no W-2s.
- Qualify for a Las Vegas mortgage as an S-Corp owner.
- S corp mortgage guide for business owners in Nevada.
- S corp mortgage in Nevada get approved after a business change.
- S corp switch & your Nevada mortgage how to get approved.
- Use your portfolio for a Nevada jumbo loan in 2026.
- Using S-Corp income for a mortgage in Nevada.
- When to apply for a self employed mortgage in Nevada.
Which Nevada guides cover reserves, appraisals, credit, gifts and refinancing?
- Avoid closing costs on a Nevada home 2026 guide.
- Buying a home from a trust in Las Vegas a guide.
- Can a non relative gift my down payment in Nevada.
- Cash from a Nevada rental with a DSCR refinance.
- Clark county property tax and transfer tax on a Las Vegas DSCR rental.
- DSCR cash out refinance to scale a Las Vegas rental portfolio.
- DSCR loan reserve rules in Las Vegas Nevada explained.
- DSCR loan reserves in Las Vegas Nevada a guide for investors.
- Get a Las Vegas mortgage with no credit score in Nevada.
- Get a mortgage on a home in a trust in Nevada.
- How to refinance in Nevada to buy out your spouse.
- How to speed up your Las Vegas DSCR loan refinance.
- How to use a gift of equity in Nevada for a mortgage.
- Mortgage recast vs refinance in Nevada which saves more.
- Nevada 1099 mortgage guide for gig worker income.
- Nevada HELOC vs cash out refinance fund your next home.
- Nevada non recurring closing costs explained for homebuyers.
- Protect your credit score during escrow in Las Vegas Nevada.
- Summerlin jumbo loans for guard gated and golf course homes.
- Systematize appraisals for success in Las Vegas Nevada.
- Tap Nevada rental equity without a cash out refinance.
- VA cash out refinance vs HELOC in Nevada a 2024 guide.
- What is a rate and term refinance in Las Vegas Nevada.
- What to do after a failed VA appraisal in Nevada.
Which other Nevada home loan guides might help?
Sources
- FHFA, conforming loan limits for 2026
- FFIEC HMDA Data Browser, Washoe County loan-level data, 2024-2025
- CFPB, about HMDA data
- CFPB, Loan Estimate and Closing Disclosure timing, 12 CFR 1026.19
- CFPB, Loan Estimate explainer
- Census Bureau TIGERweb (tract and place boundaries)
- Nevada Department of Taxation, real property transfer tax
- Washoe County Treasurer, tax rates
- Washoe County Assessor
- Washoe County Recorder
- VA, funding fee and closing costs
- VA, loan limits
- NRS 361.4723, property tax cap
Checked November 5, 2026.
Talk to a jumbo broker about your Sparks home
Call or text (702) 766-3744, apply now or contact us. Tell us the price, the ZIP and how you earn. We will show you whether a larger down payment keeps you conforming, and compare jumbo options in writing.
More: Sparks mortgage broker · Jumbo loans · Reno jumbo loans · Calculators
By David Ghazaryan, NMLS 1486726, iQRATE Mortgages (NMLS 1862492). Updated November 5, 2026.
iQRATE Mortgages LLC, NMLS 1862492, 6360 S Rainbow Blvd Ste 101, Las Vegas, NV 89118. David Ghazaryan, Mortgage Broker, NMLS 1486726. Verify licensing at NMLS Consumer Access.
iQRATE is a mortgage broker, not a lender, and does not make credit decisions. Broker compensation is disclosed on your Loan Estimate and Closing Disclosure.
This page is general information. It is not a loan offer and not a commitment to lend. All loans are subject to credit, property and underwriting approval. Rates, terms, down payment, reserve and credit requirements vary by lender and change daily. Not all borrowers will qualify. Dollar figures are simple math from public rules and data, not a quote.
HMDA figures are iQRATE's analysis of public data. The counts are small, so read percentages as rough. Local tax facts are not legal or tax advice. Investor loans are for business purposes only.
Equal Housing Opportunity.
Take the Next
Step Today